
ADMA Biologics (ADMA) Stock Still Looks Cheap Next To Its Earnings
ADMA Biologics has given long term holders a very large 5 year gain, yet recent share price weakness raises a sharper question about what investors are currently paying for its earnings. With the stock at US$10.31 after a mixed run that includes a steep year to date decline, the issue is whether that earlier success still lines up with the profits the business is generating today.
- Over the past 5 years the share price has delivered a very large return, which puts real pressure on whether the current valuation can still be explained by the company’s earnings power.
- For a plasma based therapeutics business like ADMA Biologics, expectations around how efficiently it can turn collections and manufacturing capacity into sustainable profits may support or cap what investors are willing to pay for each dollar of earnings.
- There is a second opinion on ADMA Biologics worth weighing. See what analysts think ADMA Biologics's shares could be worth.
The stock’s next move may depend on whether its recent price still lines up with what Fair Ratio implies about ADMA Biologics’ earnings valuation.
If you want to test the same earnings valuation question that hangs over ADMA Biologics against a broader set of stocks, spend a few minutes with 32 high quality undervalued stocks.
Is ADMA Biologics a Bargain on Earnings?
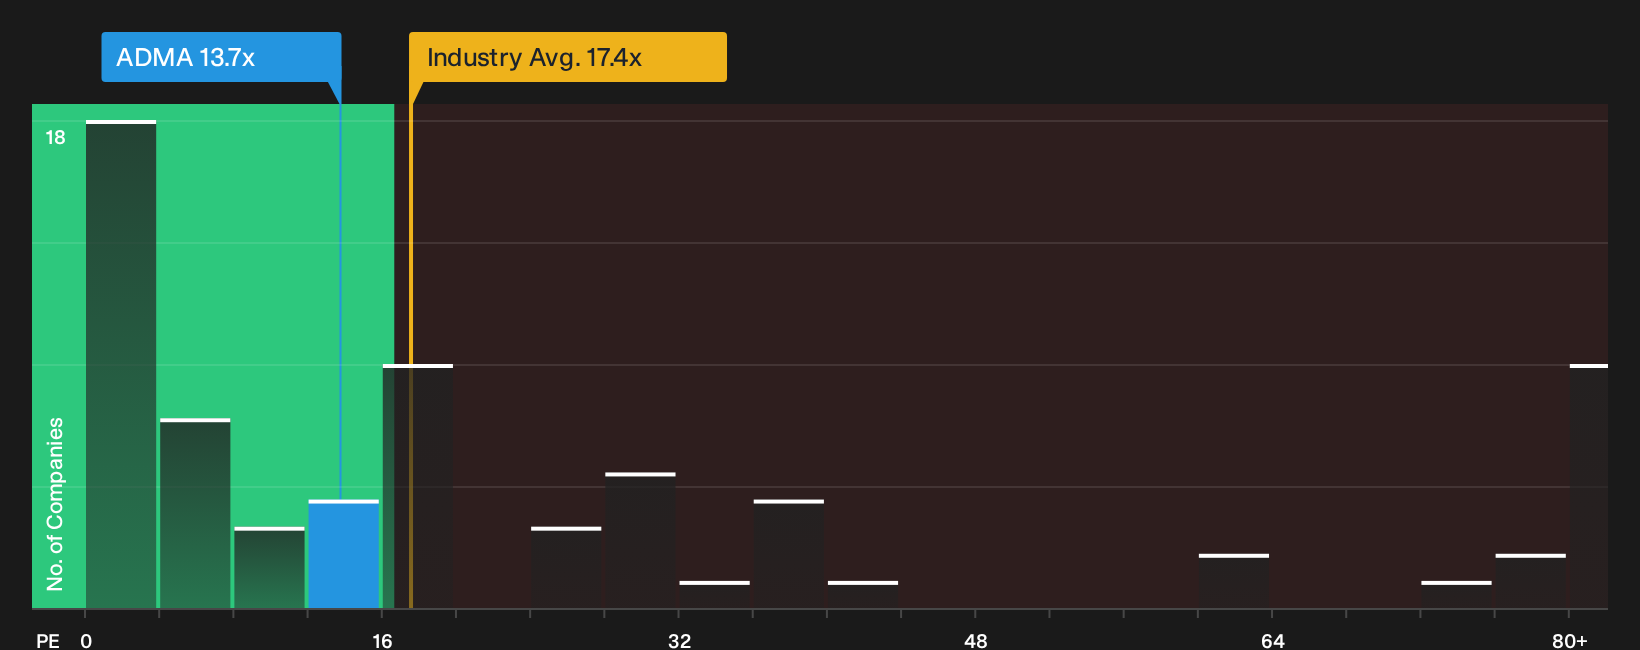
P/E tends to matter most for a business like ADMA Biologics that is already generating earnings rather than just sales. On this earnings yardstick, the stock trades on a P/E of about 13.7x, which is below both the wider biotech group on roughly 17.4x and a peer set closer to 32.8x. That trio of numbers suggests investors are paying less for each dollar of ADMA Biologics’ profit than they are for many comparable plasma or biotech players.
The Fair Ratio, which blends in factors such as growth expectations, profitability profile, size and risk, points to a higher P/E than where the shares change hands today. That gap implies the market multiple currently prices ADMA Biologics at a discount to what this tailored yardstick suggests could be justified if its earnings profile holds together. For anyone weighing the stock, the question is whether that discount reflects caution that may persist or an opportunity if the earnings base proves resilient. Explore the numbers behind ADMA Biologics's P/E valuation.
The ADMA Biologics Narrative: What Would Justify Today's Price?
Narratives for ADMA Biologics pick up where the P/E and Fair Ratio leave off by spelling out the specific growth, margin and earnings paths that would need to play out for the stock to be worth materially more or materially less than today's price on Simply Wall St's Community page. They turn a single valuation number into a set of concrete future assumptions that you can watch over time and test against how ADMA Biologics' actual results evolve.
One of the top community narratives on ADMA Biologics: 39% undervalued
"The main factor that would need to go right is continued ASCENIV adoption and margin strength that can offset weakness in BIVIGAM…"
Discover why this Narrative puts ADMA Biologics at 39% undervalued.
One more angle on ADMA Biologics that could change how you see the stock
Analyst models sketch out where earnings and the business profile might sit a few years from now. This gives you one more lens to compare against today’s pricing. Explore where analysts expect ADMA Biologics to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com