
Best Buy (BBY) After The LG Ad Solutions Deal And The Question Of Valuation
Why the LG Ad Solutions Deal Matters for Best Buy
Best Buy (BBY) just expanded its retail media reach through a fresh partnership with LG Ad Solutions, giving advertisers access to LG TV Home Screen inventory through Best Buy Ads.
The agreement connects Best Buy shopper audiences with premium connected TV placements, using Magnite for programmatic buying and Best Buy’s closed-loop tools to link ad exposure with sales outcomes.
Investors have been rewarding Best Buy’s push into higher margin services, with the share price at US$87.96 and a year to date share price return of 27.15% that reflects building momentum despite a softer 1 month share price return of a 3.13% decline. Over a longer horizon, total shareholder return of 19.99% over 1 year and 43.31% over 3 years points to a story that has already created meaningful value, even though the 5 year total shareholder return shows a 2.49% decline that reminds you this is still a cyclical retailer at its core.
Scan how other retailers building ad networks compare to Best Buy by reviewing the hand picked 32 high quality undervalued stocks that combine cash generation with more resilient balance sheets.
Best Buy now trades a touch above the average analyst target, yet screens at a 52% discount on some intrinsic value estimates. Is the market ahead of itself or still underpricing this shift into retail media?
Most Popular Narrative: 1% Overvalued
Best Buy’s most followed narrative pegs fair value at $86.95, just below the last close of $87.96. This frames the stock as essentially fully priced on these assumptions, while still leaning on new profit streams like advertising and marketplace.
Scaling of Best Buy Ads, with ad collections targeted to grow 10% on top of approximately US$900m last year and future integration with Amazon Ads technology, together with Marketplace GMV that is expected to reach about US$1.3b this year, is adding higher margin revenue streams that can support gross profit rate and operating margin.
See why 63 investors see Best Buy as 1% overvalued.
Result: Fair Value of $86.95 (ABOUT RIGHT)
Still, the Best Buy narrative could wobble if shoppers keep trading down in core tech categories, or if Best Buy Ads and Marketplace fail to cover rising SG&A.
Find out about the key risks to this Best Buy narrative.
Another View: What Multiples Say About Best Buy
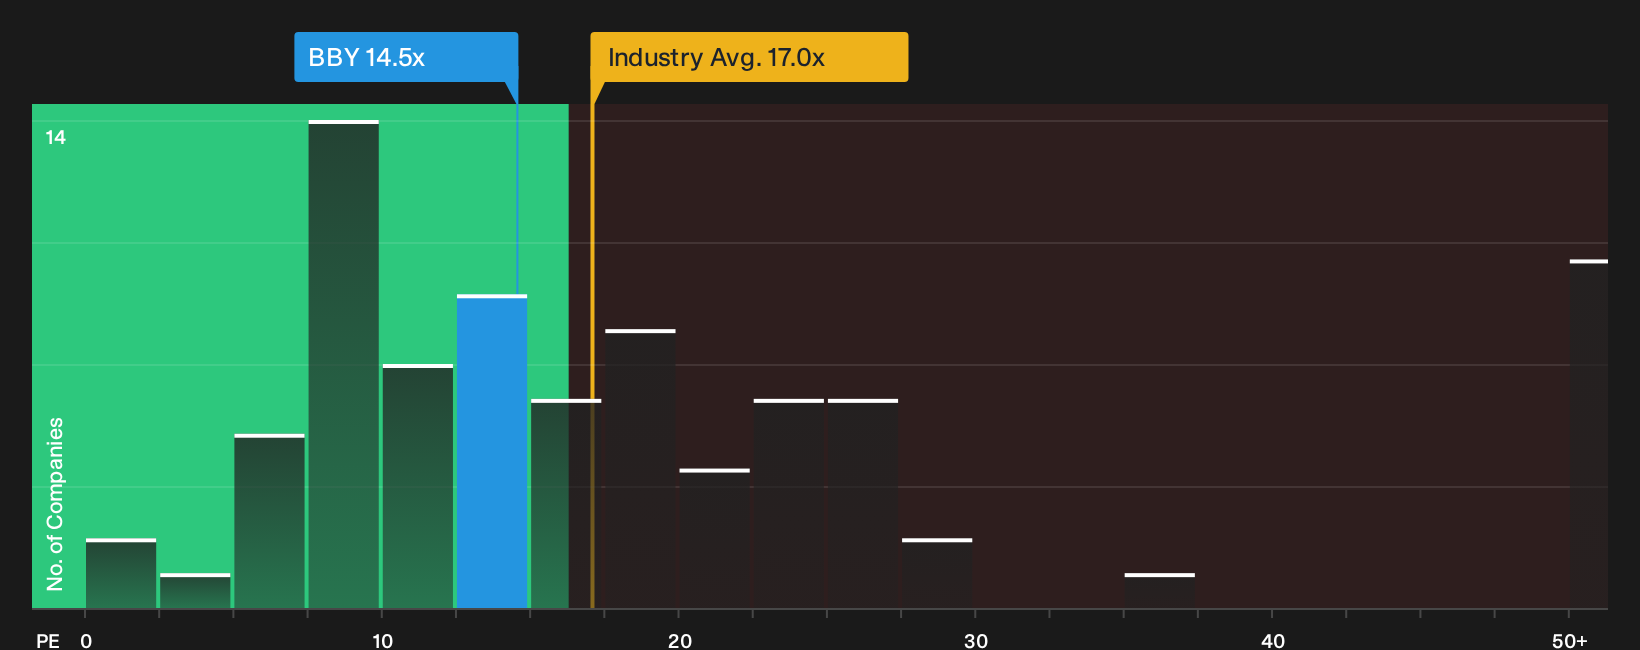
On simple yardsticks, Best Buy looks cheaper than both its own fair ratio and its peer group. The stock trades on a P/E of 14.5x, compared with an estimated fair ratio of 15.8x and a 17x average for US Specialty Retail, which points to some valuation cushion if sentiment stays supportive.
That gap could reflect genuine opportunity or just investor caution about slower forecast revenue and earnings growth. The question for you is whether this discount is enough compensation for those softer growth expectations over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Best Buy so far. If you want to move quickly and rely on your own judgement, start with the 5 key rewards and 1 important warning sign.
Looking for more Best Buy style investment ideas?
If Best Buy’s setup interests you, do not stop here. Use targeted screeners to quickly surface other opportunities that fit your risk and income goals.
- Target resilient compounding potential by scanning a curated 32 resilient stocks with low risk scores that keeps business quality and downside risk front and centre.
- Hunt for strong cash generation at appealing prices by running through the 32 high quality undervalued stocks before other investors catch on.
- Build a portfolio that pays you regularly by focusing on a hand picked 8 dividend fortresses that aims for dependable income with higher yields.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com