
Surprised By Maanshan Iron & Steel's Slide? What Investors Missed
If you had glanced at Maanshan Iron & Steel in October 2025 and decided to sit it out, that choice now looks less painful than it might have then. For Maanshan Iron & Steel shareholders, the loss over the past year was 46.8%, including dividends. With Q2 2026 showing revenue at CN¥19,506.2m but a swing into a CN¥112.3m net loss, what signals or assumptions available back in October 2025 might have prompted a harder look at the bullish story?
If the move has made Maanshan Iron & Steel harder to judge, start where the gap is still open and scan 187 high quality undervalued stocks.
The Two Maanshan Iron & Steel Stories Investors Were Weighing
The shares cost HK$2.6 at the start of the period, and anyone looking at Maanshan Iron & Steel then was really choosing between two clean but very different stories.
The bullish camp saw a Fair Value of HK$2.8, meaning a price they felt the assumptions justified, anchored on revenue growth of 4.5% a year and profit margins moving to 5.5% as special steel volumes and cost reforms took effect.
The more cautious view pointed to a Fair Value of HK$2.4, built on slower 1.1% annual revenue growth, profit margins at 4.7%, and concerns that overcapacity and high raw material costs could eat into earnings.
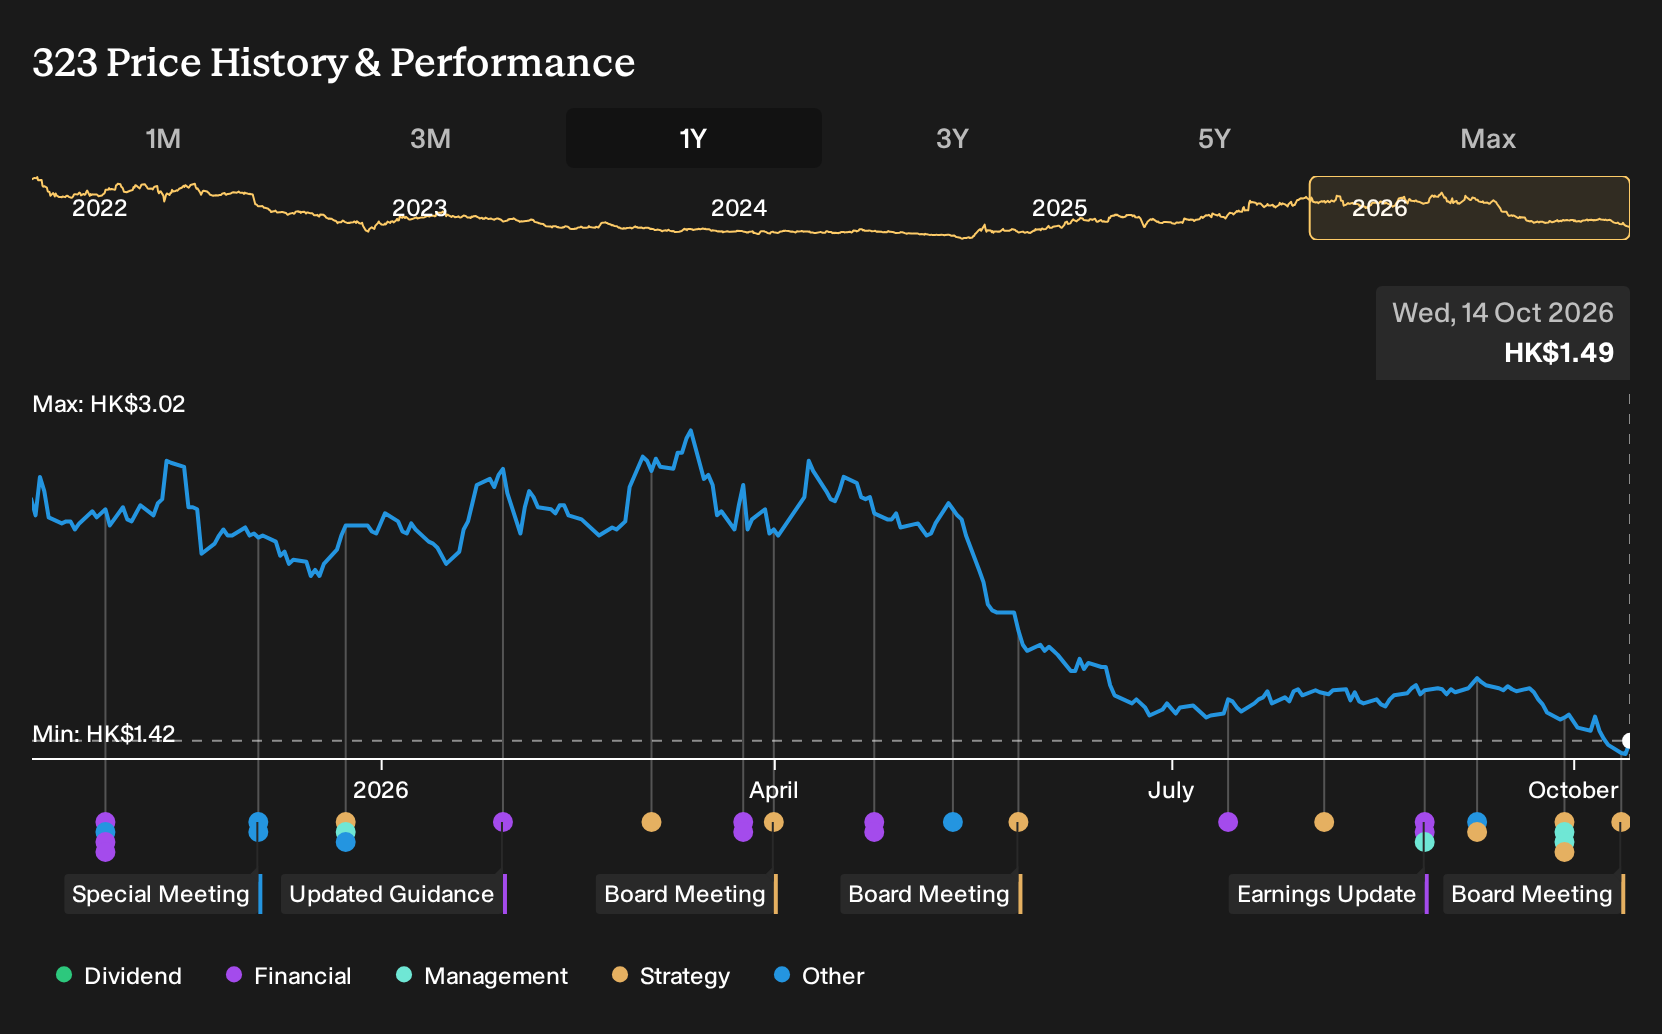
What The Q2 Results Did To The Maanshan Iron & Steel Story
The clearest new fact was Maanshan Iron & Steel posting Q2 2026 revenue of CN¥19,506.2m and a net loss of CN¥112.3m, compared with Q2 2025 revenue of CN¥18,650.6m and net income of CN¥69.3m. Net margin moved from 0.4% to a loss margin of 0.6%. That shift challenged both the bullish and cautious profitability paths.
The lesson is simple. When a thesis hinges on margin repair, watch net margin in each report rather than only headline revenue and long range P/E stories.
What Maanshan Iron & Steel's Lower Price Now Asks You To Believe
Maanshan Iron & Steel now trades at HK$1.49, after a 46.8% loss over the past year. The selected Narrative's Fair Value sits above that level, reflecting more confidence in the business than the current quote implies.
The Narrative leans on faster improvement in product mix and costs than many expect. For its higher figure to be reached, a buyer today would need to believe high margin special steels and cost cuts materially lift net margins and cash generation.
"Key Takeaways: Rapid expansion into high-margin, specialized steels and aggressive cost reforms position Maanshan for swift gains in pricing power, net margins, and operating cash flow. Strong alignment with infrastructure and renewables demand, product innovation, and strategic divestments set the stage for sustained revenue growth and increased market share."
The price and this Narrative do not agree. → Uncover what this Narrative says Maanshan Iron & Steel is actually worth
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 46% below our estimate - target gamblers shifting online with owned tech and easing tax burdens.
- Company 2 - 32% below our estimate - lean into higher priced hardware tied to immersive devices and creators.
- Company 3 - 33% below our estimate - use an entrenched nutrition brand to expand into premium products and exports.
That is three of the list. See every one of the 202 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com