
Does Full Study Enrollment Change The Bull Case For Teleflex (TFX)?
- Teleflex reported that patient enrollment in the BIOMAG-LL Clinical Study is now complete, covering 35 mm and 40 mm Freesolve resorbable magnesium scaffolds for treating long de novo coronary lesions.
- The focus on longer scaffold lengths for challenging coronary cases highlights Teleflex's effort to build clinical evidence around PCI solutions that could broaden its interventional cardiology portfolio.
- This development provides additional context for evaluating how Teleflex's investment narrative is influenced by BIOMAG-LL reaching full enrollment for longer Freesolve scaffold lengths.
Compare Teleflex's cardiology focus with other device makers aiming for procedure simplification by scanning our curated list of 33 healthcare AI stocks that could be shaping the next wave of hospital technology.
Teleflex Investment Narrative Recap
To own Teleflex, you need to believe that a more focused RemainCo can turn higher R&D and a reshaped portfolio into steadier earnings after a tough stretch for the Interventional segment. The completion of BIOMAG LL enrollment looks important for that story, but it does not change the near term reality of muted guidance and integration work that still needs fixing.
The main near term swing factor remains execution on Interventional and progress on the multiyear restructuring program, which is meant to offset stranded costs and lift margins. The biggest risk is that integration friction and cost savings slip against expectations, which would leave operating leverage weaker while the business remains unprofitable at the net income line.
The BIOMAG LL study reaching full enrollment ties directly into one of the clearer operational catalysts for Teleflex. Management is emphasizing a deeper cardiology pipeline, including Freesolve and products like EZPLAZ freeze dried plasma, to support future procedure volumes and pricing as the company concentrates on higher acuity hospital settings.
For you, the key link is between BIOMAG LL and the BIOTRONIK Vascular Intervention integration that has weighed on Interventional guidance. Successful longer lesion data could help Teleflex make better use of that acquired coronary and peripheral platform over time, though the near term test still centers on resolving order to cash issues and delivering the planned cost savings.
Teleflex earnings setup behind the BIOMAG LL story
Teleflex's narrative projects US$2.5b revenue and US$374.2 million earnings by 2029. That profile lines up with analyst assumptions for 3.9% yearly revenue growth and an earnings increase of about US$399.3 million from a loss of US$25.1 million today.
What sits behind the clinical headlines is a fairly specific earnings path that analysts are using to frame Teleflex today. The BIOMAG LL enrollment milestone plugs into that setup because the consensus view already assumes more profitable cardiology procedures can support a move from a loss of US$25.1 million to US$374.2 million in earnings by 2029, with margins rising from a loss making 1.1% to 14.8% over roughly three years.
Those targets lean on several levers that matter directly for your Teleflex thesis. The forecasts build in roughly 3.9% annual revenue growth, a gradual reduction in share count of about 4.12% per year, and a shift to a P/E multiple of 19.7x on those 2029 earnings. That multiple sits below the current US Medical Equipment sector average of 24.5x cited in the report.
Put into one picture, the analyst model assumes that the RemainCo portfolio, a heavier R&D mix in cardiology, and restructuring savings together get Teleflex to about US$2.5b of sales and US$374.2 million of earnings by 2029. For you, the key link back to BIOMAG LL is simple. Longer lesion data for Freesolve is already embedded in that earnings bridge, so any upside or shortfall in Interventional execution, including integration of BIOTRONIK Vascular Intervention, could tilt the path toward or away from those 2029 numbers.
Uncover how Teleflex's fair value indicates a 24% potential upside to its current price. This suggests a discount that could close sooner than many investors expect.
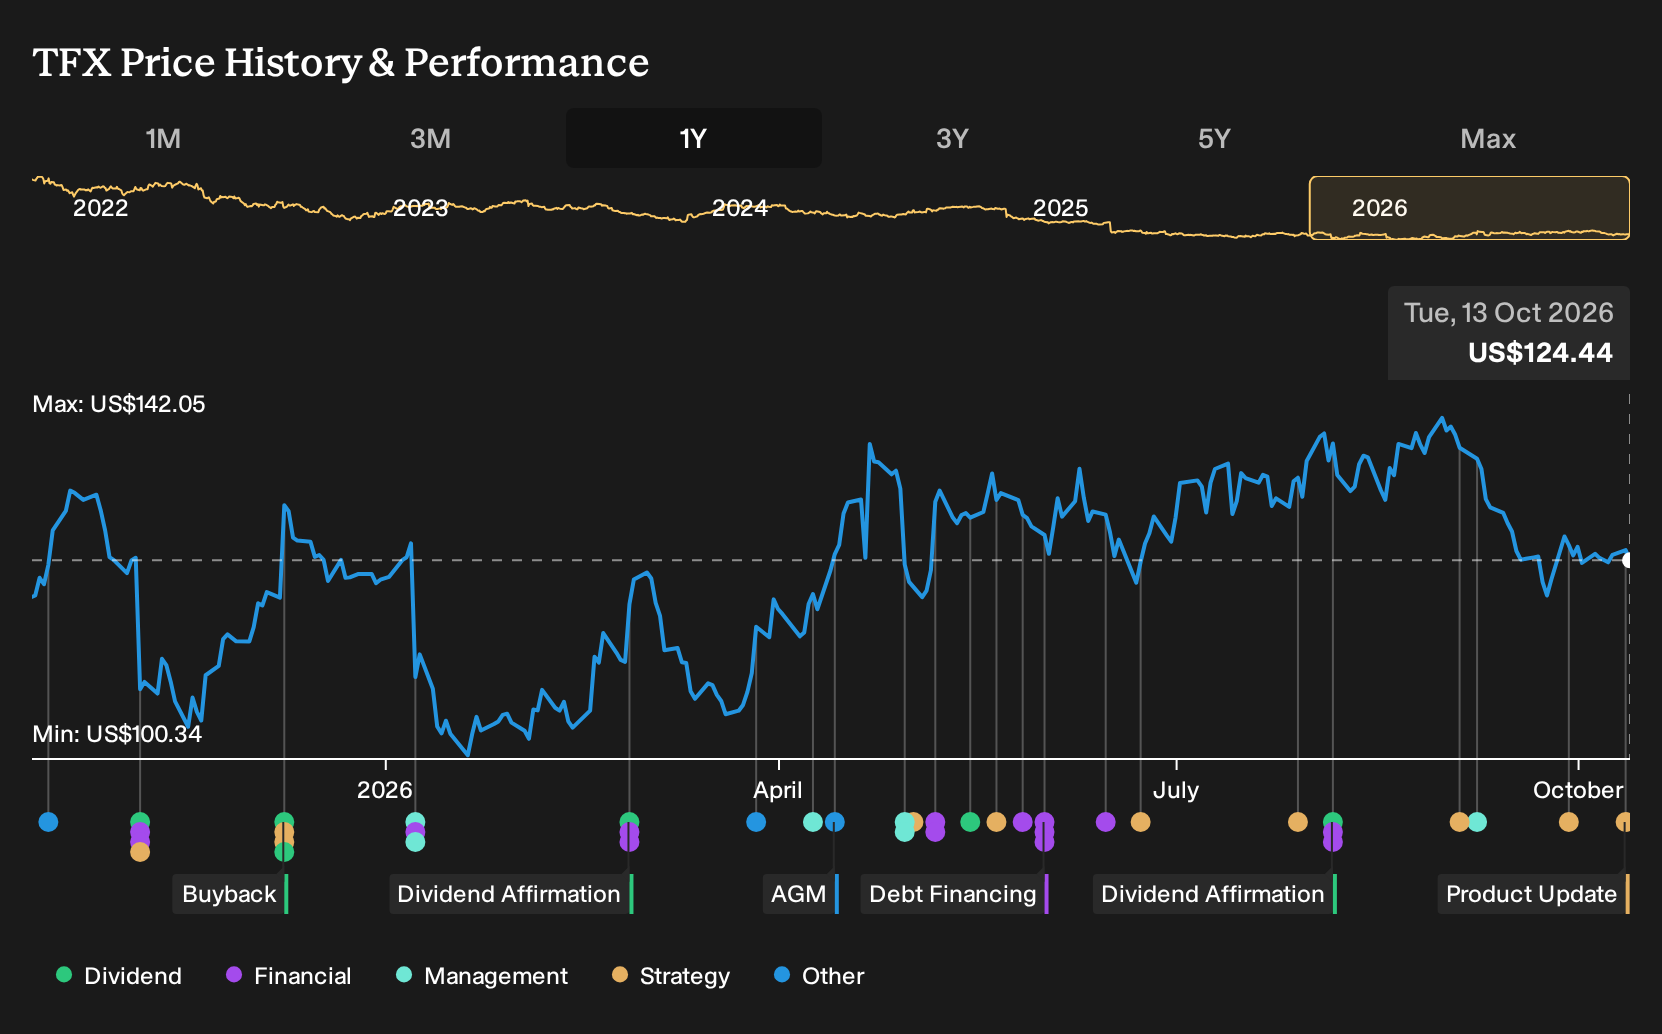
Exploring Other Perspectives
Some of the most optimistic analysts already penciled in a faster Interventional recovery for Teleflex, with revenue growing about 4.6% a year and earnings reaching roughly US$545.4 million by 2029. You now have this BIOMAG LL enrollment milestone on top. Those pre news forecasts may look conservative or aggressive once cardiology data arrive.
Explore 3 other Teleflex fair value estimates, including one that suggests as much as 102% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Teleflex research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teleflex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teleflex's overall financial health at a glance.
Looking for more Teleflex sized investment ideas?
Once you have a view on Teleflex, it can help to line it up against other opportunities using the Simply Wall St Screener so you see where it really fits in your wider watchlist.
- If capital preservation sits high on your list, consider starting with 32 resilient stocks with low risk scores that have historically steadier profiles and fewer red flags on core risk checks.
- If you prefer quality at a discount, use our screener showing 20 high quality undiscovered gems that combine solid fundamentals with less crowded coverage from the market.
- If balance sheet strength is non negotiable for you, focus on the list of solid balance sheet and fundamentals (25 results) to zero in on companies with cleaner debt metrics and healthier financial cushions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com