
Is Sugi HoldingsLtd (TSE:7649) Fairly Valued As Lower Profit Guidance Clouds Sales Growth?
Sugi HoldingsLtd guidance revision and what it means for investors
Sugi HoldingsLtd (TSE:7649) has trimmed its profit outlook for the year to February 2027 after weaker seasonal merchandise sales, even as it projects higher net sales helped by newly consolidated subsidiary Seki Yakuhin.
Recent trading tells a cautious story. The share price is at ¥1,217.0 after falling 16.62% over the past 90 days and 33.59% year to date, while the 3 year total shareholder return of 32.43% contrasts with a weaker 1 year total shareholder return that is down 27.62%. This suggests earlier momentum has faded as investors reassess Sugi HoldingsLtd after the revised guidance.
Spot fresh ideas alongside Sugi HoldingsLtd by scanning our hand picked list of 15 high quality undervalued stocks.Bulls point to Sugi HoldingsLtd’s revenue growth and consolidation of Seki Yakuhin, while bears focus on the profit downgrade and sharp share price decline. Which side does the current valuation actually support?
Price-to-earnings of 15.4x for Sugi HoldingsLtd: Is it justified?
Sugi HoldingsLtd trades on a P/E of 15.4x, which is higher than both its peer group on 14.3x and the broader JP Consumer Retailing sector on 12.8x. That valuation sits against a last close of ¥1,217 and reflects how the market is weighing its guidance revision against its track record.
The P/E ratio compares the current share price to earnings per share. For a retailer like Sugi HoldingsLtd, investors often use this metric to judge how much they are paying for each unit of profit, particularly when earnings are forecast to grow but margins have recently softened.
Here, the stock looks expensive relative to direct peers and the industry, suggesting buyers are paying more for each yen of earnings than for comparable retailers. At the same time, the fair P/E estimate of 17.2x points to a level the market could move towards if the business delivers on its earnings growth forecasts and maintains what are described as high quality earnings.
Explore the SWS fair ratio for Sugi HoldingsLtd.
Result: Price-to-earnings of 15.4x (OVERVALUED).
Still, the profit downgrade and weak recent share performance could pressure sentiment if softer trading conditions persist or if the integration of Seki Yakuhin proves more complex than expected.
Find out about the key risks to this Sugi HoldingsLtd narrative.
Another view on Sugi HoldingsLtd: cash flows tell a different story
The P/E ratio presents Sugi HoldingsLtd as expensive, but the SWS DCF model suggests a different perspective. At ¥1,217, the shares trade about 51% below an estimated future cash flow value of ¥2,482.78. That gap suggests the market is pricing recent margin pressure much more harshly than the model.
For anyone weighing which signal to prioritize, the choice comes down to a simple question. Do you think Sugi HoldingsLtd’s future cash generation will align with the assumptions in that DCF, or do you place more weight on the more cautious message from the earnings multiple?
Look into how the SWS DCF model arrives at its fair value.
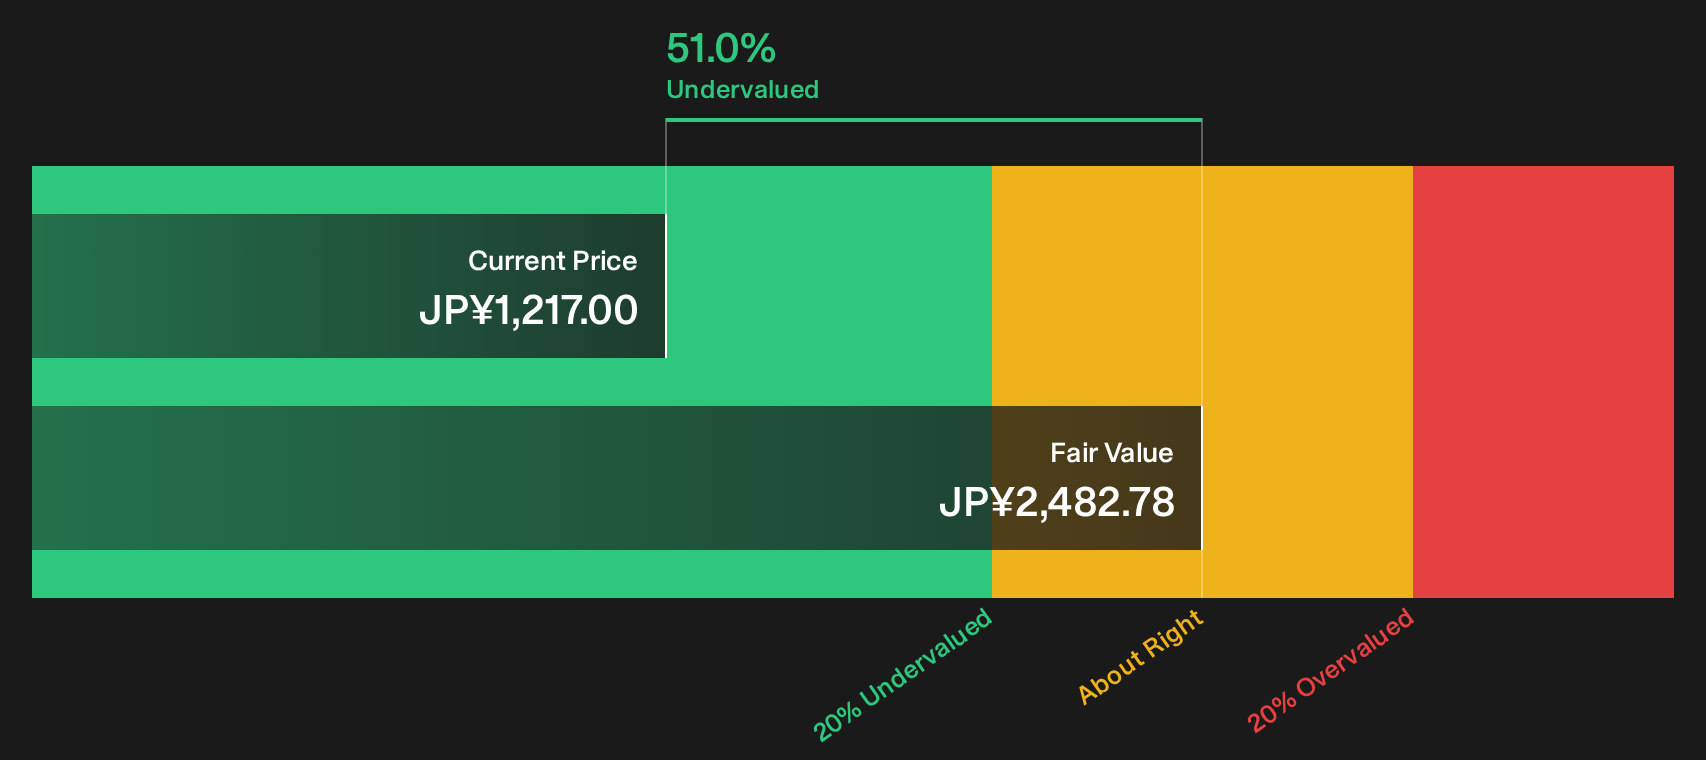
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sugi HoldingsLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Sugi HoldingsLtd is clearly split, which means your own take matters more than any single metric or model. To weigh both sides properly, start with the headline risks and potential upsides captured in these 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sugi HoldingsLtd?
If Sugi HoldingsLtd has you thinking harder about price, quality, and risk, let that momentum work for you by lining up a few fresh candidates through targeted screeners that match how you like to invest.
- Target reliable cash generators by scanning a list of solid balance sheet and fundamentals (21 results) that can help you focus on businesses with sturdier financial foundations.
- Hunt for mispriced opportunities with a 73 high quality undiscovered gems so you do not miss smaller companies that may sit off the usual radar.
- Dial back portfolio stress by filtering for a 23 resilient stocks with low risk scores and let potential candidates come to you instead of chasing every headline.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com