
What Unicaja Banco Shareholders Got Right
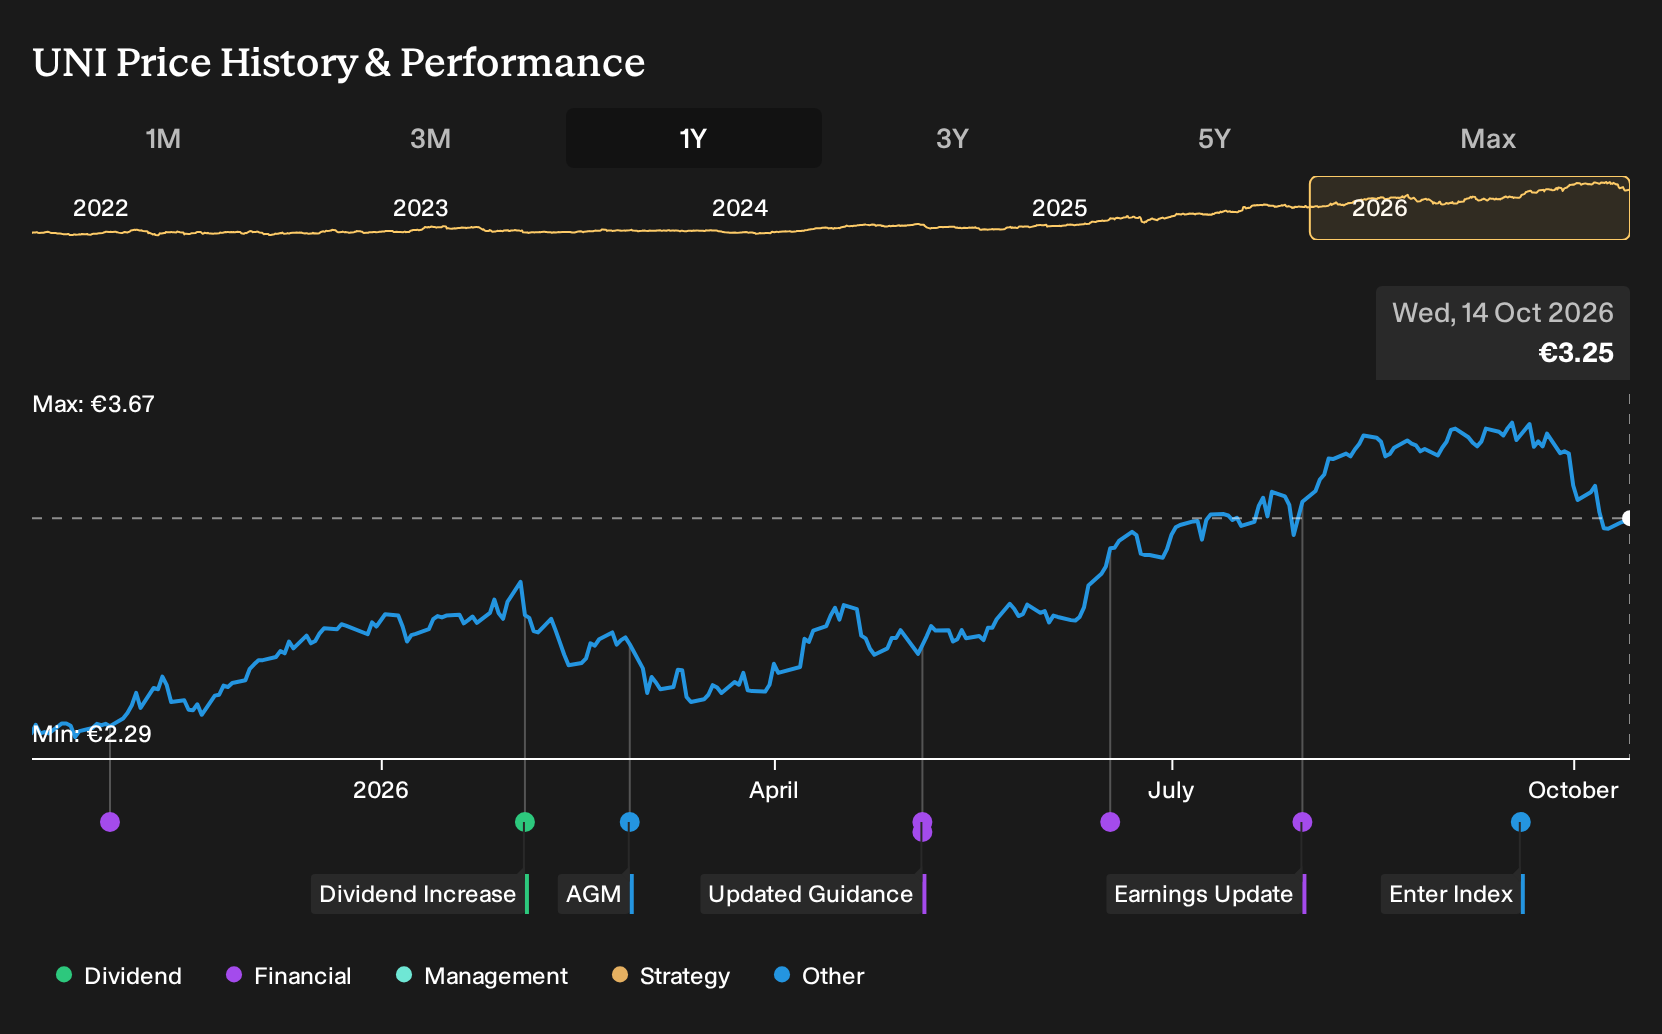
Unicaja Banco did not spend the past year standing still. It launched a buyback of €500 million in green senior non preferred notes and later reported fresh activity under its share liquidity contract, quietly reshaping its balance sheet while keeping trading orderly. For Unicaja Banco shareholders, the return over the past year was 48.1%, including dividends. If you were evaluating the situation in October 2025, what would have needed to be true about these moves to view buying in as a reasonable decision at that time?
If the move has made Unicaja Banco harder to judge, start where the gap is still open and scan 187 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Unicaja Banco
The shares cost €2.35 at the start of the period, and anyone looking at Unicaja Banco then had to decide which story about its future felt more believable.
The bullish view saw a Fair Value of €2.9, a price implied by expectations. This view was built on the idea that lending, deposits and fee income in under-banked regions would expand as digital channels and the Liberbank merger supported higher margins and recurring revenue.
The cautious narrative pointed to a Fair Value of €2.02, grounded in concerns that net interest margins could compress. At the same time, heavy spending on technology and a branch-heavy network might keep the efficiency ratio under pressure.
What The Facts Did To The Unicaja Banco Argument
Unicaja Banco’s €500 million green note buyback tied to a new issue backed the cautious case because it prioritised liability management and regulatory buffers rather than clear top line expansion. At the same time, reported revenue of €555.262 million and net income of €193.647 million in Q2 2026, with net margin at 34.9%, gave the bullish side firmer profitability evidence. Overall, the period cut both ways.
The key assumption investors needed to test was whether healthier net margins were coming from durable economics or just balance sheet tuning. For any bank you assess next, track the mix of recurring operating income versus funding and capital actions in the results commentary and segment notes.
What Unicaja Banco’s Run Already Prices In
Unicaja Banco now trades at €3.25. The selected Narrative’s Fair Value sits below the current price, reflecting a view that recent gains already embed strong beliefs about profitability, fee growth and capital strength.
On this reading, a buyer today would effectively be assuming that digital and fee growth keep earnings resilient. The key question is how rising costs and richer customer incentives affect that bet.
"The main factor that needs to go right is that Unicaja Banco converts its growth in mutual funds, insurance fees and digital channels into lasting profitability improvements that justify current payout plans and recent share price gains. The current valuation suggests that the share price already reflects strong capital ratios, high dividend payouts and mid-single-digit net profit growth, which may limit further upside if execution or the operating environment weakens."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 28% below our estimate - targets adviser and retail investors consolidating activity onto one integrated platform.
- Company 2 - 45% below our estimate - pushes deeper into bricks-and-clicks retail as new flagship locations support demand.
- Company 3 - 19% below our estimate - scales automated in-house production to broaden supplement ranges for distributor partners.
Three companies from the same screener. Open all 202 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com