
Why Johnson Controls International (JCI) Is Back In The Spotlight
Recent reports on the global data center chillers market put cooling capacity in the spotlight, and Johnson Controls International (NYSE:JCI) features as a key supplier to hyperscale, AI, and GPU-rich facilities.
That focus on data center cooling is landing at a time when Johnson Controls International’s share price has climbed to US$156.47, with a 30 day share price return of 7.16% contributing to a 27.93% year to date move and a 1 year total shareholder return of 46.83% that follows a 3 year gain of more than 3x.
Scan beyond Johnson Controls International and see which other data center infrastructure players are gaining traction in our curated list of 43 power grid technology and infrastructure stocks.
After a 3x three year run and a recent surge that still leaves Johnson Controls International at a discount to analyst targets, is this caution pricing in real risks, or undervaluing the data center opportunity before it is fully tested?
Most Popular Narrative: 6% Undervalued
Johnson Controls International’s most followed narrative pegs fair value at $165.80, above the last close at $156.47. This frames the recent surge as still short of that narrative anchor while data center expectations build into the story.
The main factor that has to go right is continued execution on service attach and productivity, so that stronger equipment demand in areas like North America and data centers ultimately translates into the more profitable, higher margin mix the business system is designed to support.
See why 25 investors see Johnson Controls International as 6% undervalued.
Result: Fair Value of $165.80 (UNDERVALUED)
Still, the Johnson Controls International narrative depends on simplifying a complex product set and avoiding weakness in Fire and Security that could reduce earnings momentum.
Find out about the key risks to this Johnson Controls International narrative.
Another View: Johnson Controls International Through The P/E Lens
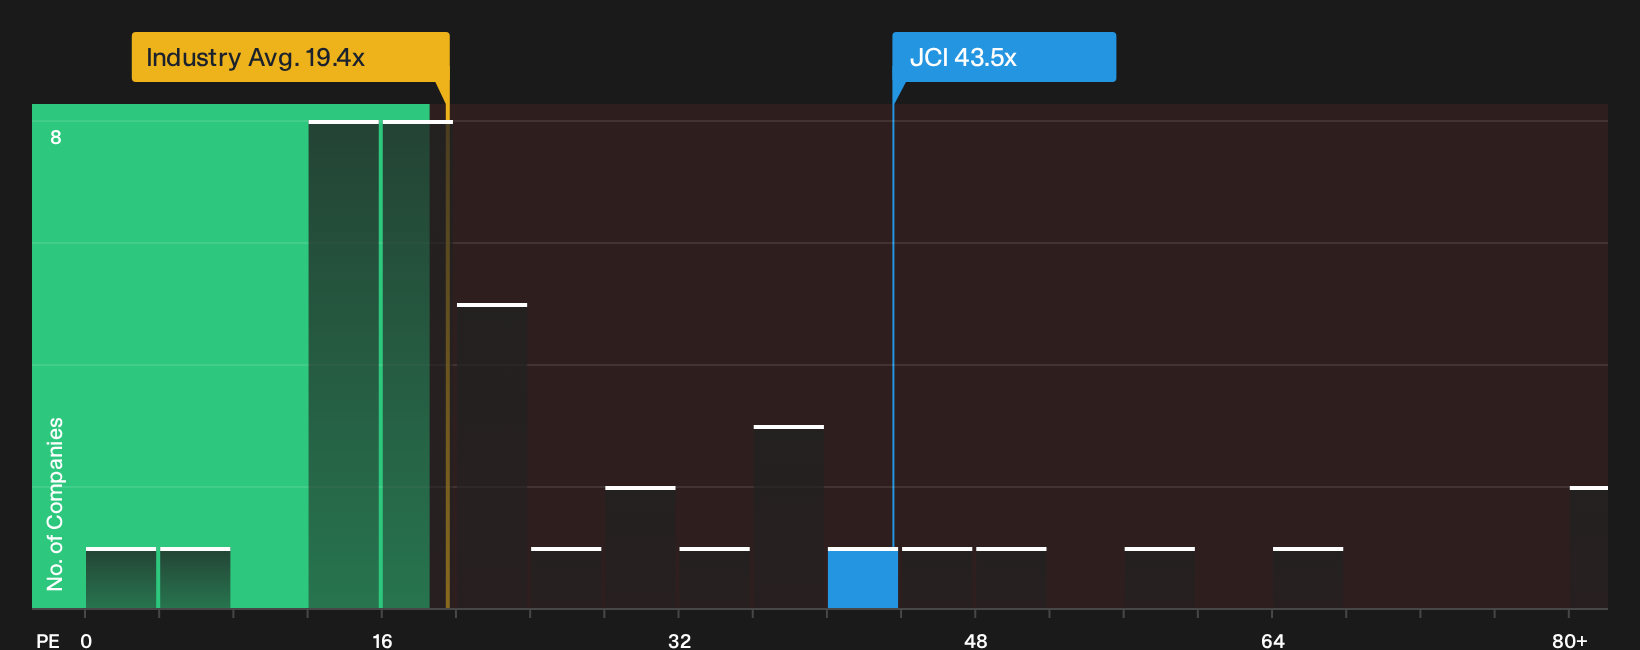
On the story-led fair value, Johnson Controls International looks 6% undervalued. On plain P/E math, it goes the other way. The stock trades around 43.5x earnings, compared with 19.4x for the US Building industry and a fair ratio of 35.1x, which points to valuation risk if sentiment cools.
That is a wide gap for you to weigh. It raises a simple question: Is the premium for data center cooling and services fully justified by future delivery, or is optimism getting ahead of itself?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all feels finely balanced between optimism and caution, that is the point. It is why you should review the data and sentiment yourself, weigh what worries and excites investors today, then anchor your next move on the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Johnson Controls International?
Do not let your research stop with Johnson Controls International. Fresh opportunities keep surfacing, and the next idea that fits your plan will not wait.
- Target steadier compounding potential by reviewing a 32 resilient stocks with low risk scores that screens for companies with more resilient profiles and lower risk scores.
- Hunt for pricing gaps by scanning a 32 high quality undervalued stocks that highlights businesses combining stronger balance sheets with attractive valuations.
- Spot tomorrow's leaders early by combing through a 20 high quality undiscovered gems focused on under-the-radar stocks with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com