
Should Raised Earnings Estimates Require Action From Stanley Black & Decker (SWK) Investors?
- Stanley Black & Decker is drawing attention after analysts lifted the Zacks Consensus Estimate for full-year earnings by 4.2%, reflecting a more constructive view on how the tool and equipment maker is executing its business plan.
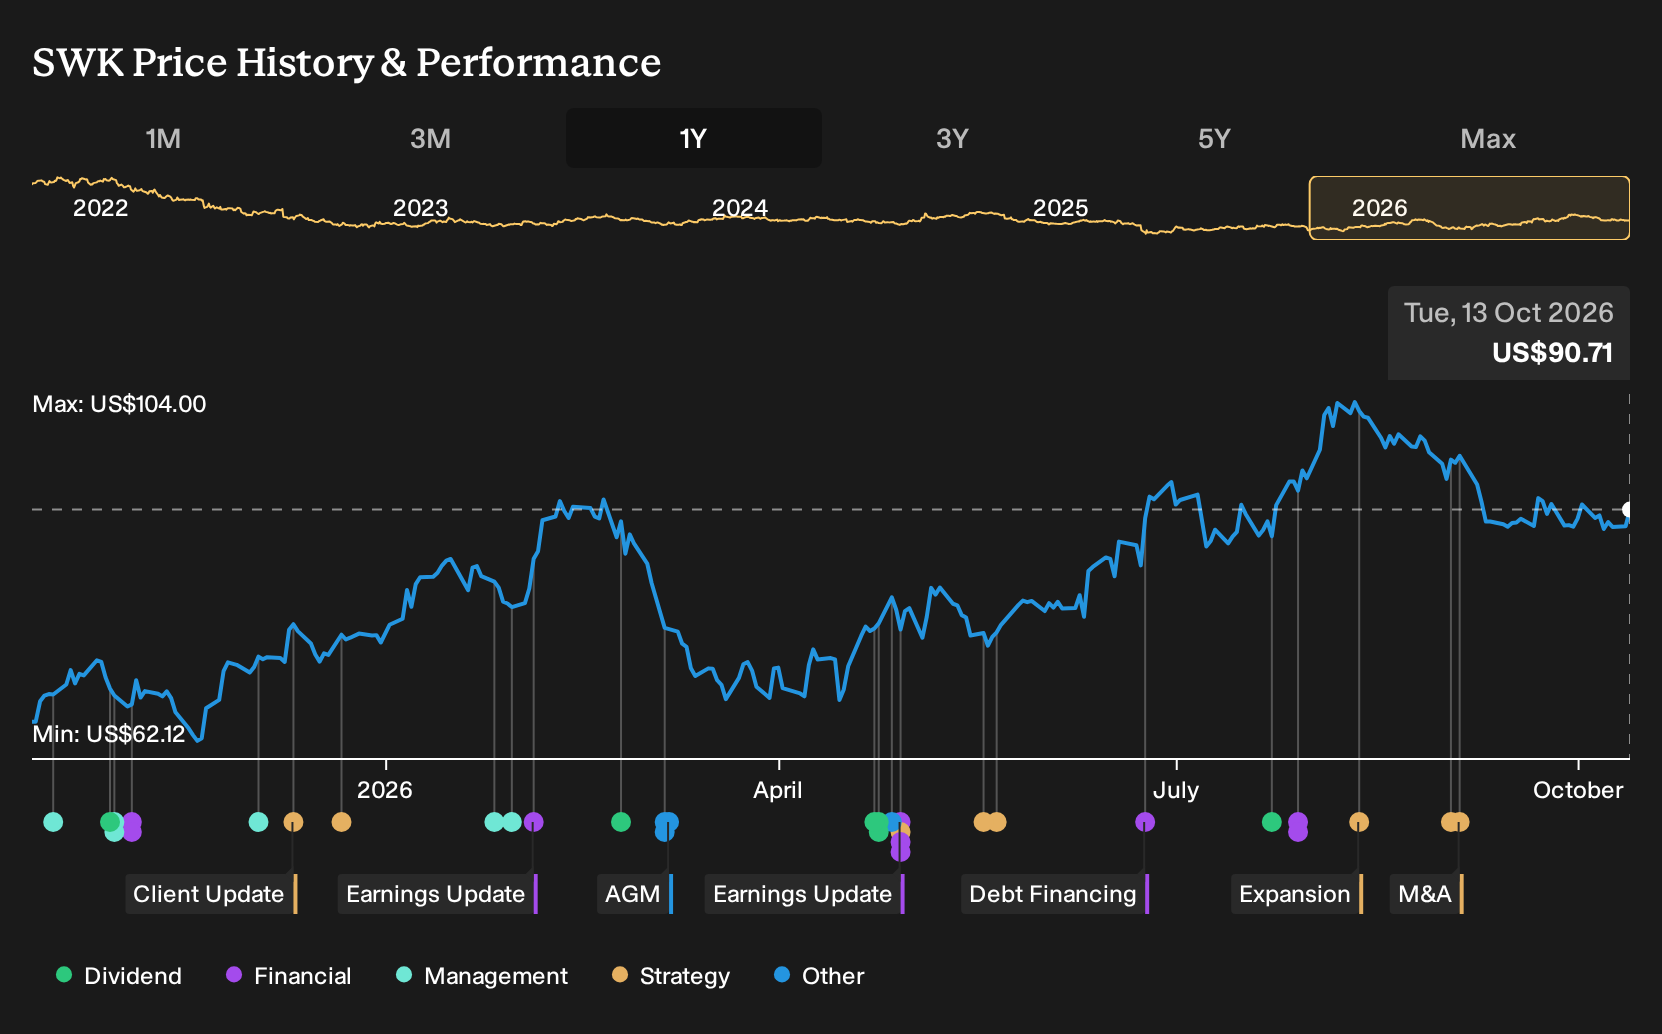
- The company’s roughly 19.2% year-to-date return versus 12.6% for the wider Industrial Products sector hints that investors are rewarding expectations for better profitability and operational follow-through rather than simply reacting to sentiment shifts.
- Next, the focus turns to how this improved earnings outlook for Stanley Black & Decker could reshape the broader investment narrative around the stock.
Scan how analysts are rewarding execution strength at Stanley Black & Decker, then compare it with other hand picked industrials on our list of solid balance sheet and fundamentals (25 results).
Stanley Black & Decker Investment Narrative Recap
To own Stanley Black & Decker, you need to believe the tools and outdoor platform can convert its supply chain work, product investment, and international reach into steadier earnings, even with modest end market growth. The latest earnings upgrade points to analysts seeing more consistent execution, but it does not erase the reality of soft DIY demand and pressure in key retail channels.
In the short term, the key swing factor is how effectively the supply chain transformation captures cost savings without hurting service levels. The main risk is that heavy reliance on pricing to offset tariffs continues to weigh on volumes, especially with channel concentration at retailers that have strong bargaining power and growing private label offerings.
Among recent developments tied most closely to this, the focus on multi year supply chain changes is central. Management is working to streamline manufacturing and distribution, with the aim of recurring cost reductions and more flexibility around tariffs and logistics. For you, the near term question is whether these efforts keep product availability high while still protecting margins.
This same program cuts both ways for the investment case. If execution stays on track, it can support the improved earnings outlook that analysts are now incorporating into their models and help offset limited growth in DIY and Outdoor demand. If savings are slower to materialize or further trade costs emerge, the combination of high debt and price sensitive customers could quickly become a headwind.
Stanley Black & Decker's current earnings of $620.5 million are projected by analysts to reach $1.1b by 2029, implying an earnings increase of roughly $479.5 million. Their models assume revenue will grow to $16.4b by the same year, based on a 2.5% yearly revenue growth rate.
Uncover why Stanley Black & Decker's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on demographic risk. In that storyline, aging US and European populations cap long run demand for Stanley Black & Decker, with bearish analysts assuming revenues of about $15.4b by 2029 and a P/E of 15.6x. Those estimates, set before this earnings upgrade, reflect a clearly more cautious stance. Readers like you can weigh these contrasts and see how opinions might shift as fresh data comes through.
Explore 3 other Stanley Black & Decker fair value estimates, including one that suggests it could be worth just $93.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your Stanley Black & Decker research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Stanley Black & Decker. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Stanley Black & Decker's overall financial health at a glance.
Looking for more Stanley Black & Decker style ideas?
If the Stanley Black & Decker story has sharpened your thinking, you can use that same lens across the wider market and let the Simply Wall St Screener surface companies that better fit your return and risk preferences.
- If capital preservation matters most to you, start with a focused group of companies that screen as 32 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, use the screener to zero in on 32 high quality undervalued stocks that pair cash generation with disciplined balance sheets.
- If you are comfortable casting a wider net in less followed corners of the market, the screener can highlight 20 high quality undiscovered gems that meet your fundamental criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com