
Record Silver Output Could Reshape The Case For Hecla Mining Stock
- Hecla Mining reported second quarter 2026 revenue of US$334 million, record silver output of 1.5 million ounces at Lucky Friday, lower all in sustaining cost guidance for silver and quarter end cash of US$483 million after redeeming its remaining senior notes.
- The combination of record mine performance, reduced cost expectations and a debt free balance sheet backed by a new US$500 million credit facility may influence how investors view Hecla Mining’s operational resilience and financial flexibility.
- We will look at how Hecla Mining’s record Lucky Friday silver production may reshape the investment narrative built around efficiency and cash generation.
Compare Hecla Mining's combination of record output, lower cost guidance and a debt free balance sheet with a curated group of precious metal producers screened from 10 top silver producer stocks.
Hecla Mining Investment Narrative Recap
To own Hecla Mining, you need to believe the portfolio can keep turning strong silver assets into consistent cash while managing higher costs and permitting demands. The latest quarter leans in that direction. Record Lucky Friday output and lower silver cost guidance point to tighter operations, which matters if industry wide capital needs at Keno Hill and elsewhere keep rising.
In the short term, the key swing factor is whether this operating momentum at Greens Creek, Lucky Friday and Keno Hill can offset analyst expectations for declining earnings over the next few years. The biggest near term risk remains heavier capital and regulatory pressure that could squeeze free cash flow if execution slips or silver prices soften.
The most relevant update for that catalyst story is the new US$500 million revolving credit facility. Together with US$483 million of quarter end cash and the redemption of senior notes, Hecla Mining now reports liquidity that gives management optionality on mine development, technology spending and tailings infrastructure without relying solely on fresh equity.
That facility does not remove risk. It mainly shifts the debate toward how efficiently that borrowing capacity is used and whether new projects earn more than their capital and compliance burden. For you as a shareholder, the question is whether this balance sheet flexibility supports the production ramp and cost profile that analysts currently expect to weaken.
Hecla Mining's narrative projects US$1.5b revenue and US$539.3 million earnings by 2029. This assumes revenue declines of 4.6% per year and a US$13.2 million earnings decrease from current earnings of US$552.5 million.
Uncover how Hecla Mining's fair value indicates a 42% potential upside to its current price, which could narrow quickly if market expectations catch up.
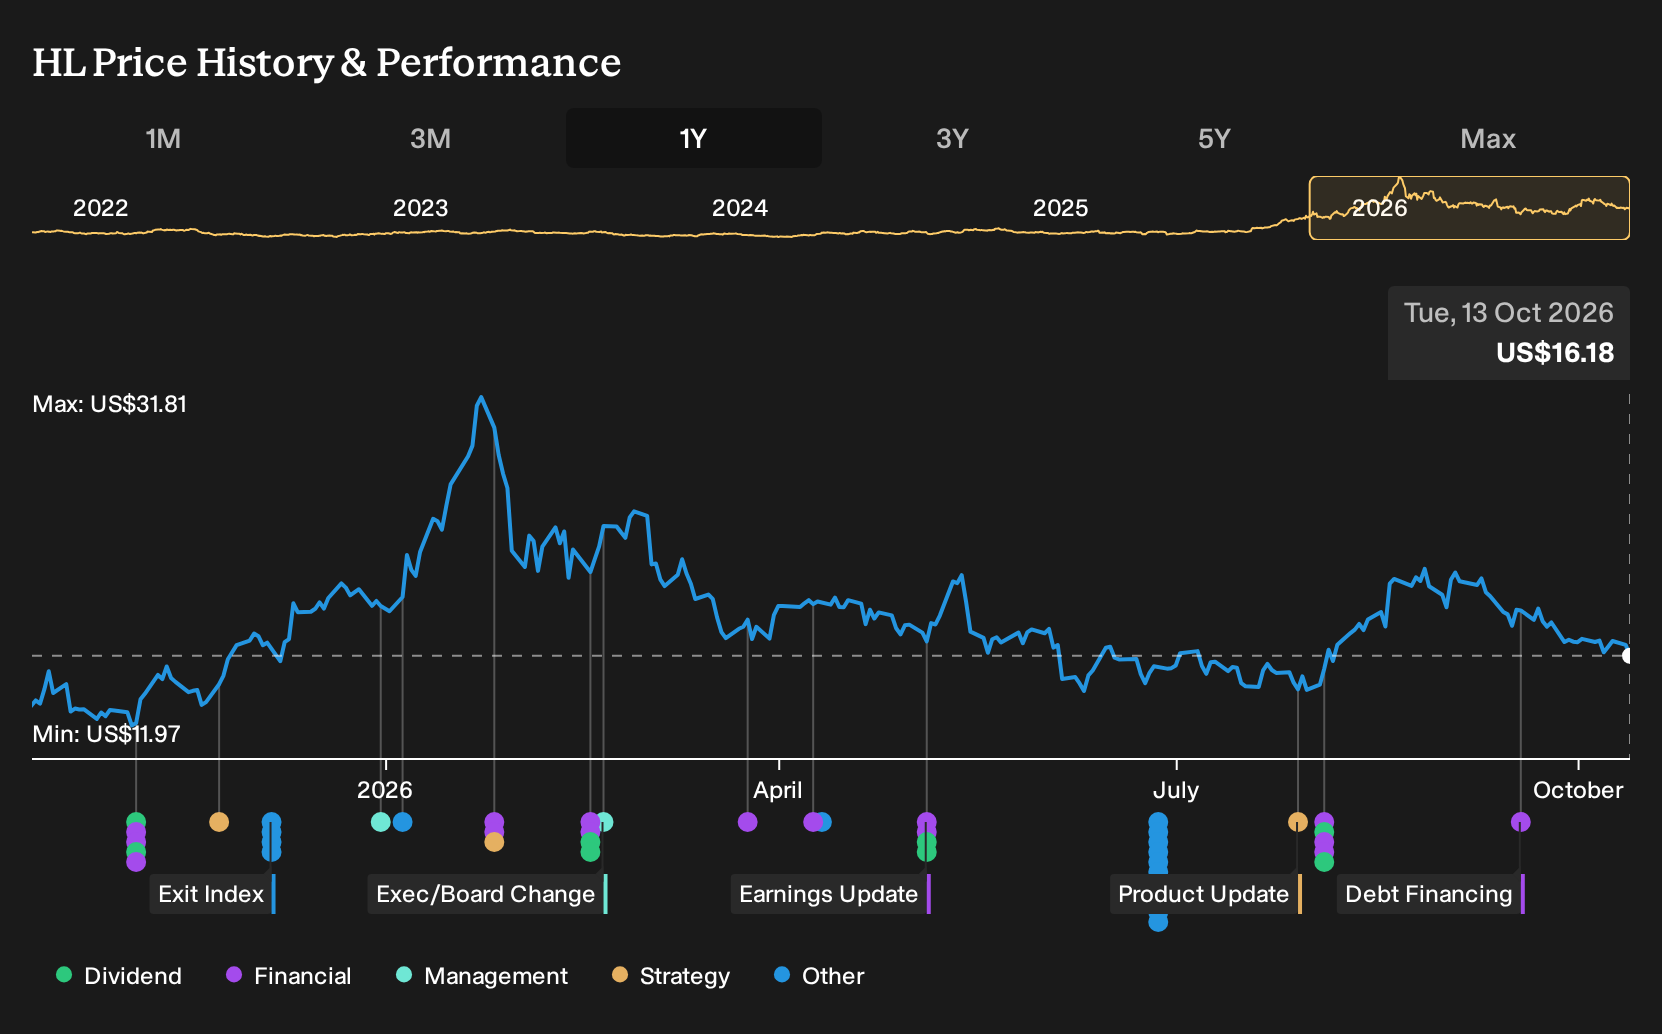
Exploring Other Perspectives
One big swing factor in the alternate Hecla Mining story is sector consolidation. The most optimistic analysts were already sketching a future built on acquisitions and larger reserves, with 2029 revenue pencilled at about US$1.7b and earnings near US$928.3 million. Those projections came before this production update, so opinions may shift and widen from here.
Explore 5 other Hecla Mining fair value estimates, including one that suggests there could be as much as 98% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Hecla Mining research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hecla Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hecla Mining's overall financial health at a glance.
Looking for more investment ideas beyond Hecla Mining?
If the Hecla Mining story has you rethinking how you build your portfolio, it can help to line it up against a broader set of opportunities that fit different risk and income profiles.
- For investors who want potential upside without stretching on balance sheet quality, scan a list of solid balance sheet and fundamentals (25 results) that can serve as the core of a more resilient portfolio.
- If you are hunting for mispriced opportunities with room for sentiment to shift, sort through a 32 high quality undervalued stocks that matches stronger fundamentals with more modest expectations.
- For readers who care most about income today, focus on a 8 dividend fortresses that screens for higher yields combined with stability filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com