
Is Ollie's Bargain Outlet Holdings (OLLI) Undervalued After Its $500 Million Buyback?
Ollie's Bargain Outlet Holdings (OLLI) just rolled out a fresh share repurchase authorization of up to $500 million, with no set end date, alongside management commentary on steadier comparable-sales trends.
The new US$500 million buyback lands as Ollie's Bargain Outlet Holdings trades at US$88.33, with a 1 month share price return of 20.08% and a 3 month share price return of 34.94%. This comes even though the year to date share price return is down 20.65% and the 1 year total shareholder return is down 31.53%, while the 3 year and 5 year total shareholder returns of 21.17% and 33.13% suggest longer term holders have still seen gains. The recent rebound hints that investors are again responding positively to the stabilized sales story and ongoing merchandising work.
Scan how management-backed buybacks and resilient business models compare across retail by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
After a 35% three month jump and a fresh buyback plan, Ollie's Bargain Outlet Holdings now trades at a double digit discount to analyst targets, but at a premium to some intrinsic estimates. Where does fair value really land?
Most Popular Narrative: 10.6% Undervalued
Against the last close at $88.33, the most followed narrative for Ollie's Bargain Outlet Holdings pegs fair value at $98.78. That gap frames the buyback, the recent share recovery, and the comp story in a different light.
The dominant narrative architecture of the September call is trifurcation, weather, consumer pressure, and a promotional environment presented simultaneously as three separable but overlapping headwinds, any one of which is "transitory" and none of which management claims to parse with precision. This structure is defensible, Rob Helm said plainly, "it''s hard for us to parse out how much of that was weather versus promotional environment versus state of the consumer", but it also immunizes the narrative against accountability for any single factor.
See why 2 investors see Ollie's Bargain Outlet Holdings as 11% undervalued.
Result: Fair Value of $98.78 (UNDERVALUED)
Still, the Ollie's Bargain Outlet Holdings story leans heavily on tariff refund benefits and weather explanations, so a tougher promotional backdrop or weaker comps could undermine that confidence.
Find out about the key risks to this Ollie's Bargain Outlet Holdings narrative.
Another View: Ollie's Bargain Outlet Holdings Through Earnings Ratios
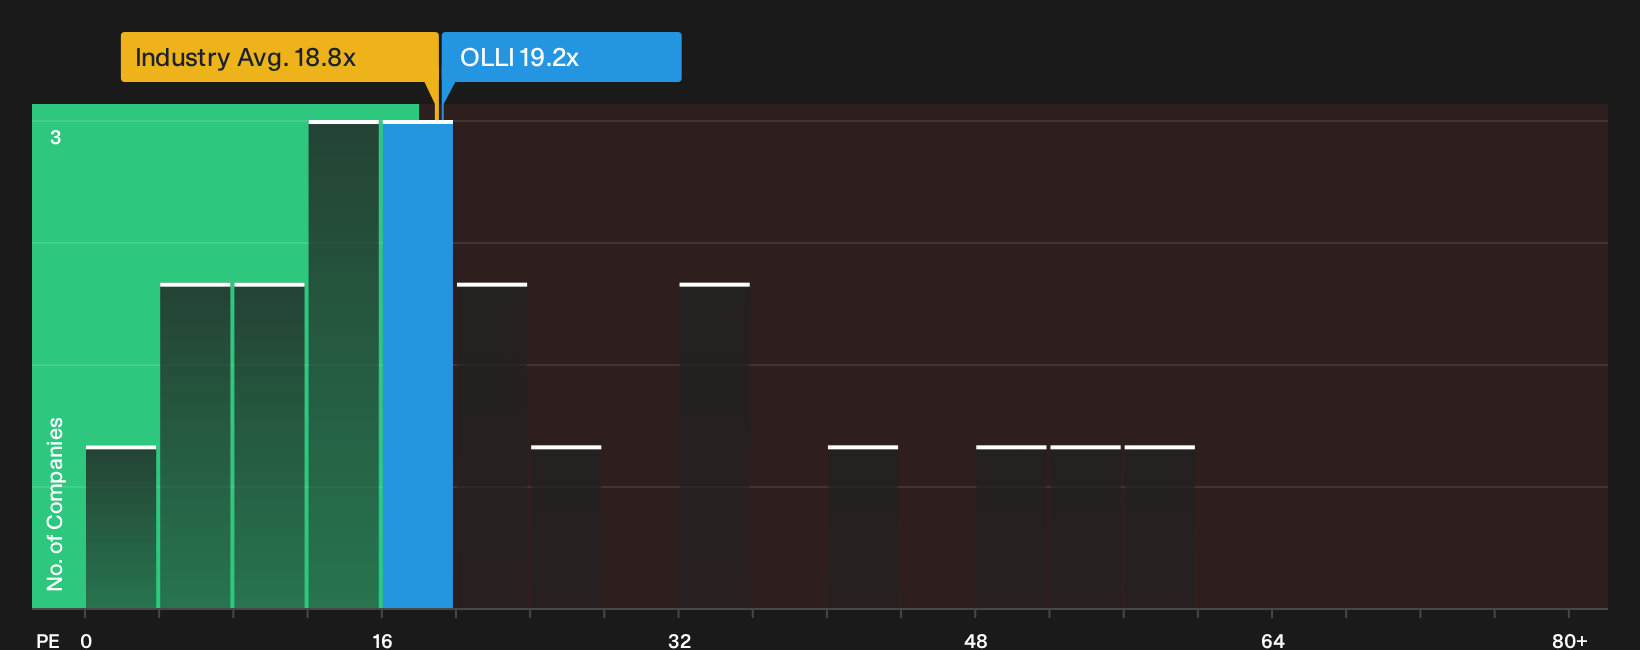
The SWS fair ratio tells a different story for Ollie's Bargain Outlet Holdings. The current P/E sits at 19.2x while the fair ratio is 13.3x, the US Multiline Retail industry trades around 22x, and close peers average 18.7x. That mix points to a richer earnings tag than the fair ratio suggests, so investors may want to consider how much comfort they take from the 10.6% undervaluation narrative.
To see how that earnings multiple compares in more detail, review the valuation breakdown built around the fair ratio context See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling uncertain after all those mixed signals around Ollie's Bargain Outlet Holdings and its valuation stories? Act while the data is fresh and pressure test the optimistic angles yourself by checking out the 3 key rewards.
Looking for more Ollie's Bargain Outlet Holdings sized opportunities?
If Ollie's Bargain Outlet Holdings has you thinking harder about price, quality, and risk, do not stop at a single ticker when there are broader ideas on the table.
- Target stronger balance sheets and steadier fundamentals by running your filters through our list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by scanning companies that score well on both valuation and fundamentals with the 20 high quality undiscovered gems.
- Secure more predictable profiles by screening for businesses with sturdier risk metrics using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com