
How Phase 2 Lupus Data At Biogen (BIIB) Has Changed Its Investment Story
- Biogen reported 52 week Phase 2 data from the AMETHYST trial of litifilimab in cutaneous lupus erythematosus, showing sustained skin disease improvements, a generally well tolerated safety profile and supporting its FDA Breakthrough Therapy Designation.
- The litifilimab readout points to a potential first in class, once monthly therapy that may broaden Biogen's pipeline beyond multiple sclerosis into dermatology and autoimmune care.
- We will now look at how Biogen's investment narrative is shaped by litifilimab's Phase 2 durability data in cutaneous lupus erythematosus.
Track how Biogen’s litifilimab story fits into the wider autoimmune and healthcare opportunity set by scanning our hand picked 33 healthcare AI stocks featuring emerging treatment platforms and data driven drug pipelines.
What Is Biogen's Investment Narrative?
Owning Biogen means believing this research engine can convert a concentrated neurology portfolio into a broader autoimmune and specialty care platform. The litifilimab Phase 2 data in cutaneous lupus erythematosus supports that idea by reinforcing a potential once-monthly, first-in-class asset that sits outside multiple sclerosis and Alzheimer’s. In the near term, the big swing factors still appear tied to execution on Leqembi uptake, ZURZUVAE positioning and maintaining reasonable resilience in existing MS therapies.
Operationally, Biogen has to juggle funding late-stage trials, managing a P/E of 40.5x and working through choppy profitability, with net margins at 8.3% and affected by one-off items. The litifilimab readout supports the autoimmune story but does not remove the risk that revenue growth, forecast at 2.6% a year, remains modest if flagship launches underperform.
That said, the outlook changes quickly once you consider ...
There's only one way to know the right time to buy, sell or hold Biogen. Head to Simply Wall St's company report for the latest analysis of Biogen's Fair Value.
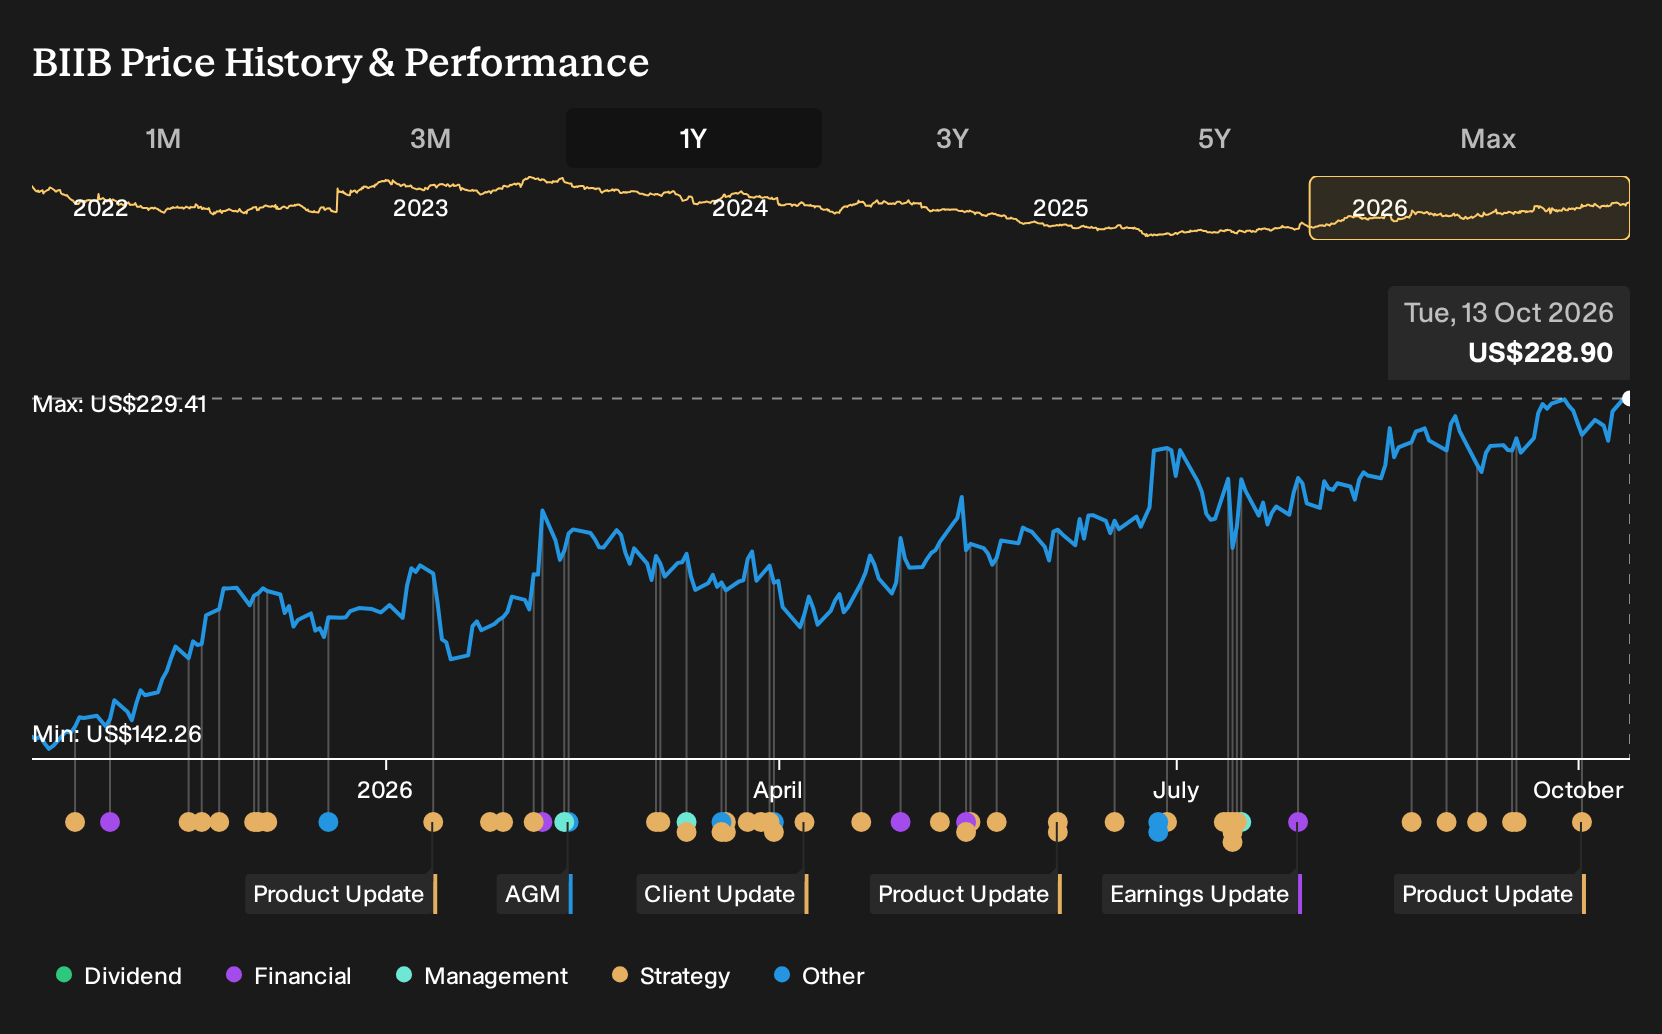
Exploring Other Perspectives
Some of the lowest Biogen analysts worry that lupus and Alzheimer’s programs will not offset pricing and reimbursement pressure. Before this litifilimab update, they were penciling in roughly flat revenue near US$10.3b by 2029 and earnings of about US$1.7b. Use that more cautious script as a foil and explore how views might shift.
Explore 4 other Biogen fair value estimates, including one that suggests as much as 19% downside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Biogen research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Biogen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Biogen's overall financial health at a glance.
Looking For More Biogen-Sized Investment Ideas?
If Biogen has you thinking about where to find the next opportunity, it helps to scan a wider field of candidates that match your own risk and return preferences.
- If you want potential mispricing with fundamentals in mind, start with our hand picked 32 high quality undervalued stocks that screen for quality alongside attractive pricing signals.
- If income is a priority, focus on stability and payout strength through a curated set of 8 dividend fortresses that have yields above 5% and an emphasis on resilience.
- If balance sheet strength matters most to you, filter for companies with cleaner leverage and funding profiles using our list of solid balance sheet and fundamentals (25 results) to narrow the universe to financially robust candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com