
How Investors Are Reacting To Sumitomo Chemical (TSE:4005) CO2 Membrane Trial
- Sumitomo Chemical has been testing a new CO2 separation membrane at a Kawasaki waste incinerator under a NEDO backed program to move carbon capture technologies from pilot to commercial use, targeting lower cost and energy needs for mid sized emitters.
- The project underlines Sumitomo Chemical's effort to turn climate focused materials technology into a commercial offering that could reshape how mid scale industrial sites handle emissions and potentially widen the addressable market for its Essential & Green Materials segment.
- This report examines how Sumitomo Chemical's investment narrative intersects with this CO2 membrane initiative and its broader decarbonisation strategy.
Scan for other decarbonisation plays beside Sumitomo Chemical by reviewing our hand picked 43 power grid technology and infrastructure stocks that could benefit as carbon capture and energy infrastructure buildouts progress.
Sumitomo Chemical Company Investment Narrative Recap
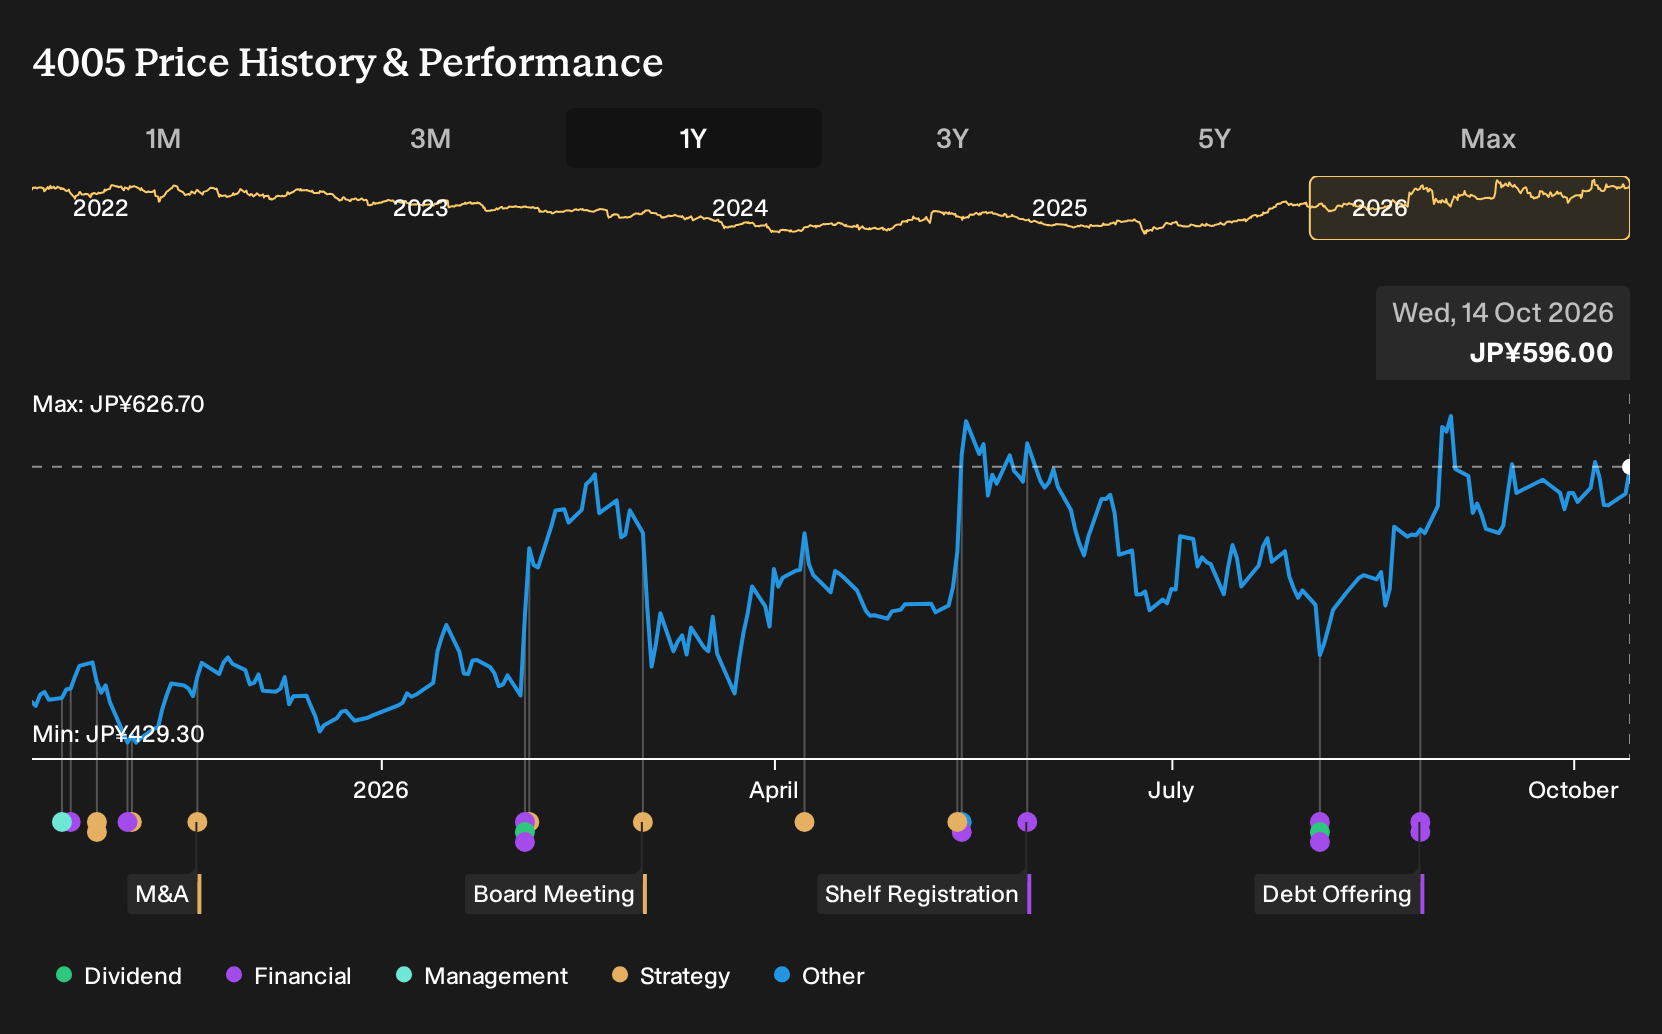
To own Sumitomo Chemical, you need to believe the portfolio shift toward Agro & Life Solutions, ICT & Mobility Solutions and greener materials can offset pressure in petrochemicals and working capital. The most important near term catalyst remains execution on that earnings mix shift while keeping debt and cash generation under control after free cash flow turned more negative in Q1 FY2026.
The biggest risk still sits in margin pressure from naphtha linked petrochemicals and slow clearing of crop protection inventories, which could weigh on earnings and limit dividend flexibility. The CO2 membrane news is directionally aligned with the green materials push but looks incremental rather than a near term financial swing factor.
There have been no fresh company specific announcements tied directly to this CO2 membrane trial, so the most relevant reference point remains Sumitomo Chemical’s existing emphasis on Essential & Green Materials and process licensing. That framework helps place the Kawasaki pilot as another potential building block in a higher margin, IP heavy revenue mix.
For you as an investor, the interest is less about one incinerator test and more about proof that climate focused materials can scale into a real earnings stream. If the firm can turn membrane know how into commercial contracts or licensing over time, it would support the current catalyst of improving segment profitability while still leaving balance sheet and cash flow execution as key watch points.
Sumitomo Chemical Company's current analyst script points to revenues of ¥2,561.6b and earnings of ¥101.1b by 2029, based on 2.5% yearly revenue growth and an earnings decline of ¥5.2b from ¥106.3b today.
Uncover why Sumitomo Chemical Company's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into the CO2 story. Bullish analysts frame Sumitomo Chemical as a future climate solutions platform, not just a chemicals group. They were already pencilling in ¥2,814.1b of revenue and ¥141.5b of earnings by 2029. Those expectations came before this NEDO backed membrane trial, so your own view may shift as the decarbonisation angle evolves.
Explore another Sumitomo Chemical Company fair value estimate, including one that suggests as much as 41% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own well-researched view.
- A great starting point for your Sumitomo Chemical Company research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sumitomo Chemical Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sumitomo Chemical Company's overall financial health at a glance.
Looking for more investment ideas beyond Sumitomo Chemical Company?
If the Sumitomo Chemical story has sparked fresh questions about where to allocate capital next, it can help to look across a wider set of opportunities that match your preferred balance of quality, risk and income potential.
- For investors who want strong fundamentals paired with meaningful upside potential, review a curated set of 73 high quality undiscovered gems that might not yet be widely followed by the market.
- If capital preservation and steadier profiles matter most to you, filter for 23 resilient stocks with low risk scores that align with stricter risk controls and more resilient business profiles.
- For those who care about balance sheet strength and durability through cycles, focus on a list of solid balance sheet and fundamentals (21 results) to anchor your watchlist in financially robust companies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com