
Barclays Just Downgraded DELL Stock. Here's Why.
Dell Technologies (DELL) stock ended lower on Wednesday after Barclays questioned whether its extraordinary year-to-date rally had outpaced the business outlook. In his research note, analyst Tim Long downgraded DELL to “Equal Weight” and trimmed his price target to $574, matching the price at which the company closed its most recent session.
Despite today’s decline, Dell stock is trading at about 4x its price at the start of this year.
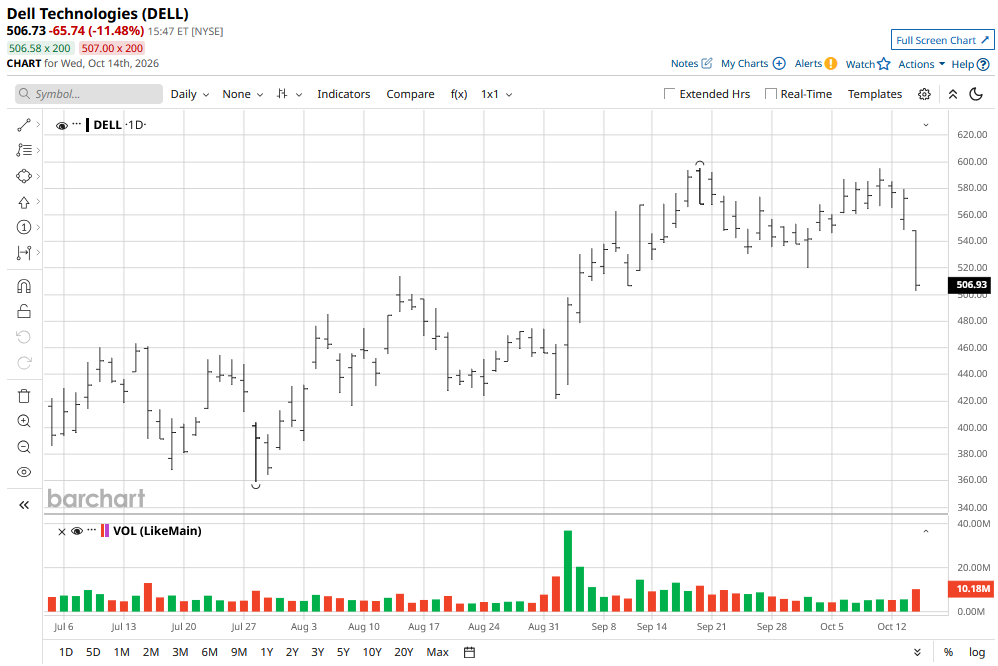
What Made Barclays Downgrade Dell Stock
Long downgraded DELL stock due to concerns about the quality of enterprise hardware growth. According to the analyst, higher component costs have helped lift revenue, but a meaningful acceleration in enterprise AI spending has yet to emerge. He sees stronger enterprise sales as reflecting memory prices more than a broad shift toward AI infrastructure.
That distinction matters for investors. Passing higher input costs through to customers can increase reported sales without producing a comparable improvement in underlying demand or profitability.
In short, Barclays’ argument is that investors are likely assigning too much value to an anticipated AI hardware refresh before the spending evidence supports that optimism.
Why Else Barclays Advises Caution When It Comes to Dell
Barclays expects Dell's artificial intelligence server revenue to roughly triple in the current year to $75 billion, with operating margins near 5%. It also estimates operating expenses will come in at 8% of revenue in fiscal 2027, down from about 15.6% in fiscal 2024.
However, Long anticipates slower growth over the next two years and smaller earnings upgrades. For shareholders, the implication is that strong results alone may become less effective at driving Dell shares higher. After such a substantial rally, the company needs to exceed increasingly demanding expectations.
Barclays’ downgrade signals reduced confidence in the magnitude of those future surprises, even as its forecasts still anticipate substantial AI server sales.
DELL Shares Remain Buy-Rated Among Wall Street Firms
Other Wall Street firms seem to disagree with Barclays on Dell Technologies, though.
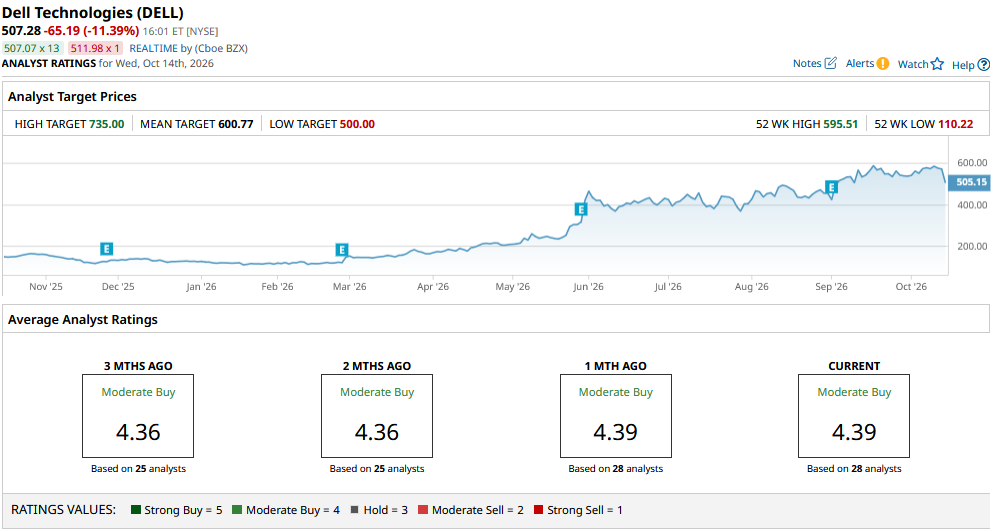
The consensus rating on DELL shares remains at “Moderate Buy,” with the mean price target of about $600 indicating potential upside of nearly 20% from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.