
Domino's Pizza (DPZ) Could Be 27% Undervalued As Earnings Beat Meets Valuation Debate
Domino's Pizza (DPZ) just reported third quarter numbers, pairing an earnings beat with a new US$1.99 per share dividend declaration and an active buyback program that keeps capital returns in focus.
Despite the earnings beat and fresh capital return plans, Domino's Pizza shares fell 4.8% on the day to US$296.10, extending a year-to-date share price decline of 30.4% and a 1-year total shareholder return decline of 28.7%. This points to fading momentum as investors weigh slower same-store sales growth, leadership changes, and the ongoing buyback and dividend stream against the current valuation.
Scan how Domino's Pizza compares with other consumer stocks under pressure on returns and capital allocation by reviewing our hand picked 32 high quality undervalued stocks.
After a 30% slide this year, Domino's Pizza now pairs modest same store sales trends with solid earnings and steady cash returns. Does that reset leave the risk reward skewed in buyers' favour or not?
Most Popular Narrative: 27% Undervalued
Against the latest close at $296.10, the most followed valuation narrative on Domino's Pizza anchors fair value at $408.07, which implies a material discount and frames the recent share price slide very differently from the headline reaction to quarterly numbers.
Domino's Pizza is a great brand, enjoying a wide moat that results in an operating margin of around 20%. Given the maturity of the business, its revenue growth is below 10% but still modestly above the economy growth rate. Its franchise business model and disciplined capital allocation decisions also result in a stellar ROIC around 10 times its cost of capital. The reduction in shares outstanding over the last five years has also increased each shareholder's ownership stake ("pizza slice") in the company.
See why 12 investors see Domino's Pizza as 27% undervalued.
Result: Fair Value of $408.07 (UNDERVALUED)
Still, the Domino's Pizza story can shift quickly if same store sales growth slows further, or if buybacks and dividends absorb cash that might be needed elsewhere.
Find out about the key risks to this Domino's Pizza narrative.
Another View: Domino's Pizza Through A Cash Flow Lens
The popular community narrative points to a fair value for Domino's Pizza near $408.07, yet the Simply Wall St DCF model points in a different direction. On that framework, DPZ at $296.10 trades slightly above an estimated future cash flow value of $291.45, which frames the stock as modestly overvalued instead of discounted.
Both approaches lean on detailed forecasts but they weigh cash flows, margins and terminal assumptions differently, so the gap between $408.07 and $291.45 is really a question of which inputs you trust more and how much uncertainty you are willing to carry into your own model.
To see how that model is built and pressure test those assumptions yourself, take a closer look at the SWS DCF model output for Domino's Pizza, starting with Look into how the SWS DCF model arrives at its fair value..
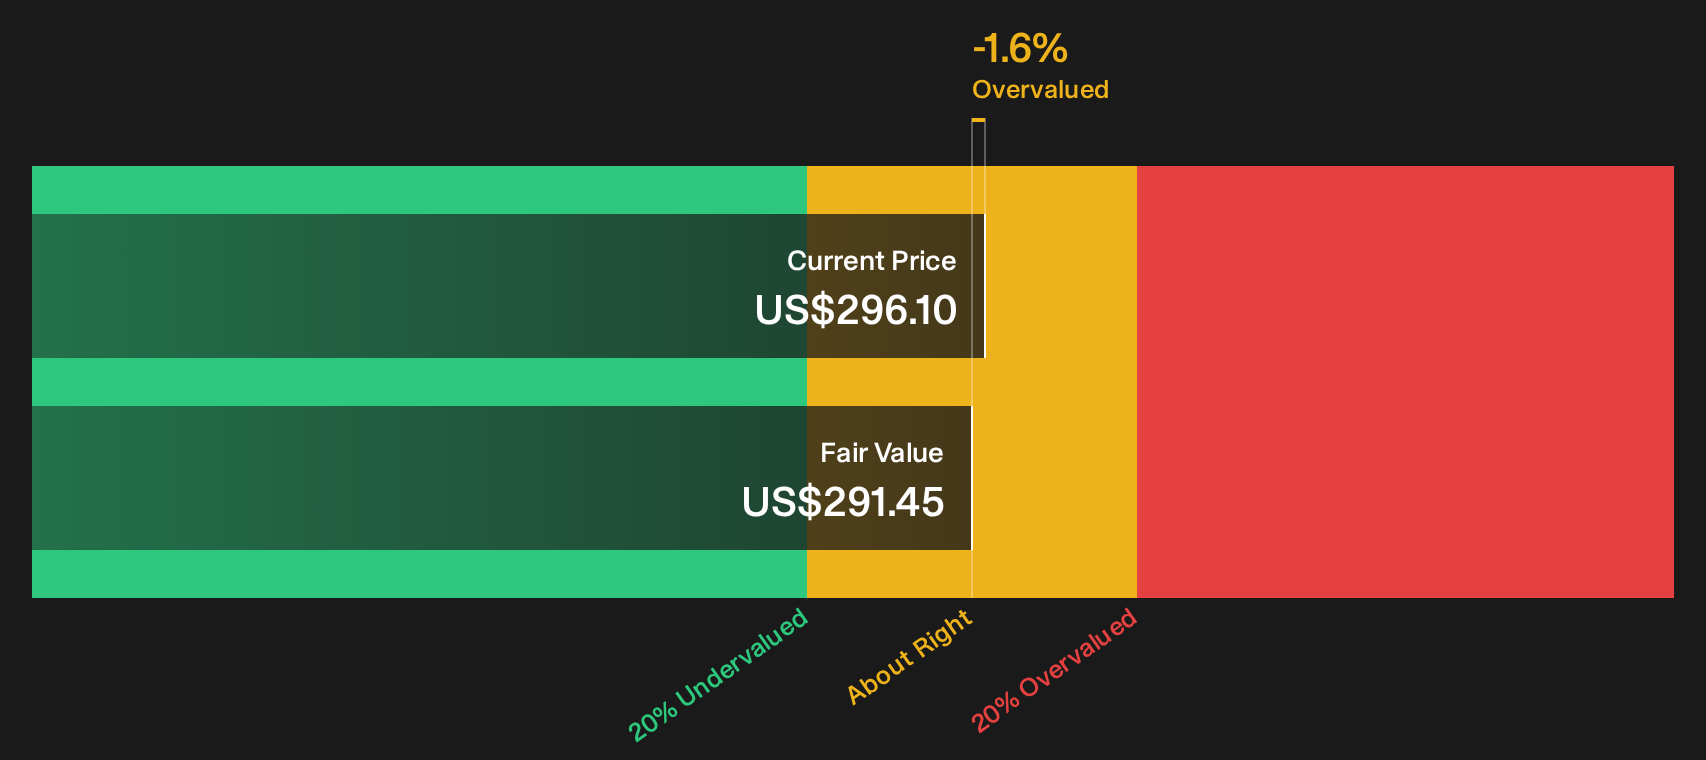
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Domino's Pizza for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Domino's Pizza so far. If you want to move quickly and form your own take on the trade off between potential upside and downside, weigh both sides of the story with the 5 key rewards and 2 important warning signs.
Looking for more Domino's Pizza sized ideas?
If Domino's Pizza has you rethinking where risk and return line up, do not stop here. Broader idea hunting can sharpen your next move.
- Target resilient value by scanning companies that combine quality fundamentals with attractive valuations using the 32 high quality undervalued stocks.
- Prioritise capital strength and filter for businesses with robust finances through the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd and search for promising smaller players with strong fundamentals across the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com