
What Kulicke And Soffa Industries (KLIC)'s SEMI Award Win Means For Shareholders
- Kulicke and Soffa Industries recently received the 2026 SEMI Award for North America for its fluxless thermocompression bonding technology, which addresses interconnect scaling needs in AI, high performance computing and photonics packaging.
- The award points to real progress in advanced packaging tools that target heterogeneous integration, an area where qualification cycles and customer adoption patterns can materially influence equipment demand.
- We will now see how Kulicke and Soffa’s investment narrative could be affected by this SEMI Award recognition for fluxless thermocompression.
Scan beyond Kulicke and Soffa Industries and see which other advanced packaging and AI hardware suppliers are already on our curated list of 92 AI infrastructure stocks.
Kulicke and Soffa Industries Investment Narrative Recap
For a shareholder in Kulicke and Soffa Industries, the key belief is that advanced packaging tools, especially thermocompression systems, can keep finding real demand in AI, memory and power semiconductor assembly. The SEMI Award validates the fluxless thermocompression roadmap but does not remove the near term swing factor, which is how quickly customers qualify and order these tools.
The biggest short term catalyst remains a smoother production ramp in fluxless thermocompression, vertical wire and ACELON advanced dispense, given management’s focus on technology transitions into fiscal 2026. The main risk is that utilization in memory and general semiconductors moderates, or adoption of high bandwidth memory and on device AI moves slower than anticipated.
The SEMI Award for fluxless thermocompression aligns most directly with management’s existing push to grow advanced packaging and thermocompression shipments into HBM, logic and eventually higher volume DRAM and mobile opportunities. Recognition helps reinforce that the technology is real and shipping, which matters given long customer qualification cycles and uneven order timing.
Where this could matter most is in the planned production ramp. Management has indicated that roughly half of expected fiscal 2026 incremental growth is tied to technology transitions and share gains in areas such as fluxless thermocompression, vertical wire, advanced dispense and power semiconductor assembly. Any delay in customer adoption, or utilization above roughly 80% slipping back, would still be a key operational risk.
Kulicke and Soffa Industries’ narrative points to forecast revenue of $1.8 billion and projected earnings of $500.1 million by 2029, based on analysts’ assumption of 22.8% yearly revenue growth and an earnings increase of about $384.4 million from $115.7 million today.
Uncover why Kulicke and Soffa Industries' fair value indicates a 26% potential upside to its current price that could narrow quickly.
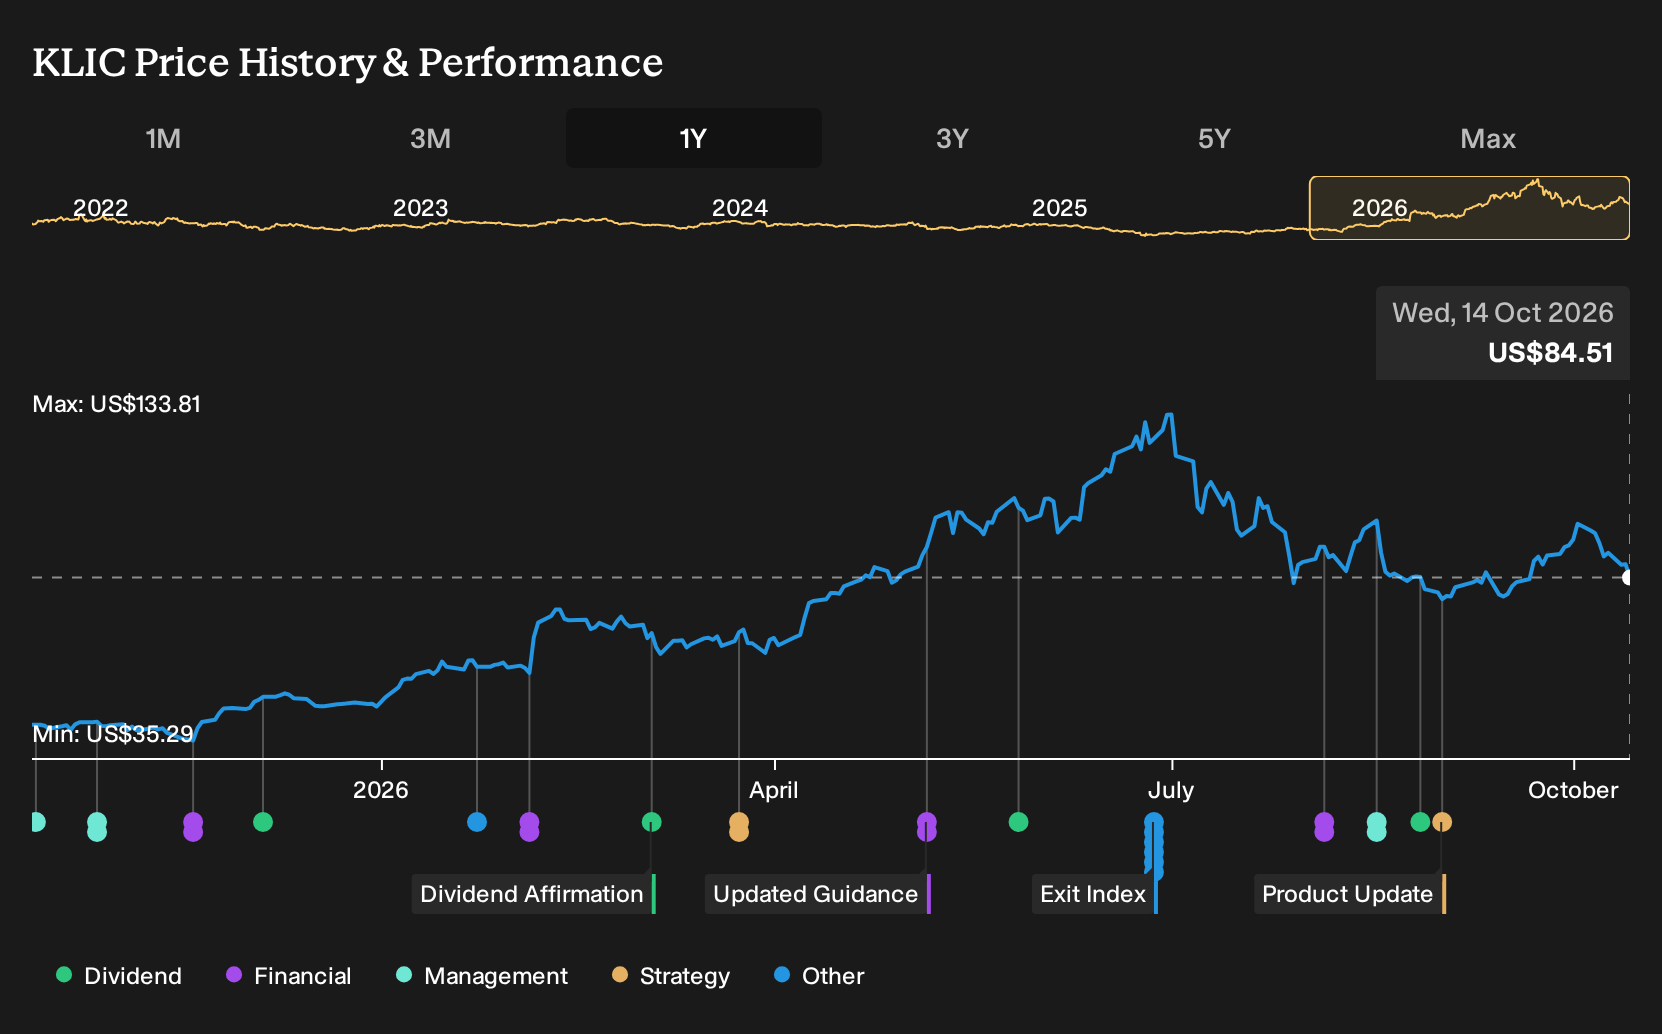
Exploring Other Perspectives
Some of the most optimistic analysts on Kulicke and Soffa Industries lean hard into one catalyst. They assume advanced packaging ramps smoothly, with revenue climbing about 27.5% a year and earnings reaching roughly $491.9 million by 2029. Those forecasts were set before this SEMI Award, so you may want to see how opinions shift.
Explore 3 other Kulicke and Soffa Industries fair value estimates, including one that suggests as much as 26% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Kulicke and Soffa Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kulicke and Soffa Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kulicke and Soffa Industries' overall financial health at a glance.
Looking for more investment ideas beyond Kulicke and Soffa Industries?
If the Kulicke and Soffa Industries story has you thinking more broadly about where to put fresh capital, it can help to line up a few watchlist candidates that match different goals, from value to balance sheet strength to income.
- If you want potential value with quality fundamentals in focus, review our carefully filtered list of 32 high quality undervalued stocks that share a blend of healthy cash flows and resilient balance sheets.
- For investors who care most about financial resilience and sleep-at-night risk, filter for companies with stronger balance sheets using the list of solid balance sheet and fundamentals (25 results) and see which ones match your criteria.
- If income is a priority and you are hunting for higher yields with a stability tilt, scan through the 8 dividend fortresses and spot which payers might deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com