
Will Higher Dividend Change SkiStar's (OM:SKIS B) Narrative
- SkiStar reported fourth quarter sales of SEK 292 million and full year sales of SEK 4,954 million, with the Board proposing a dividend of SEK 3.50 per share, equal to SEK 274 million or 44% of profit after tax.
- The increased dividend payout indicates that SkiStar’s Board is comfortable distributing a larger share of profit while the business reports higher annual net income.
- We will now explore how SkiStar’s higher proposed dividend might influence the existing investment narrative built around capacity and profitability.
Compare SkiStar’s dividend move with other potential payout stories by scanning a hand picked set of 217 dividend fortresses that may appeal if income is central to your thesis.
SkiStar Investment Narrative Recap
SkiStar appeals to investors who believe its Nordic resort platform can continue filling lifts and beds as major capital projects begin to contribute. The higher dividend does not radically change that view. In the near term, booking strength around key holiday weeks still looks like the main swing factor, given recent comments on softer periods and weather sensitivity.
The main risk remains that warm winters or weak Easter demand put pressure on lift usage, snowmaking costs and retail mix, just as large projects such as new gondolas require ongoing investment. A richer payout slightly raises the bar for cash generation, but the core question remains focused on operating performance rather than capital returns.
The full year earnings release links this dividend move back to operations. Sales reached SEK 4,954 million and net income was SEK 627 million, which frames the proposed SEK 274 million dividend and 44% payout ratio. That leaves a meaningful portion of profit within the business to fund resort upgrades and accommodation expansion.
Regarding potential catalysts, the reported improvement in net loss in the seasonally weak fourth quarter, along with higher annual revenue, appears more significant than the extra SEK 0.50 per share. These figures highlight how effectively SkiStar is building out its year-round mountain offering while managing weather risk and the cost of operating larger, more complex resorts.
SkiStar's narrative projects SEK 5.6b revenue and SEK 847.1m earnings by 2029. This is based on an assumption of 3.8% yearly revenue growth and an earnings increase of about SEK 256.5m from SEK 590.6m today.
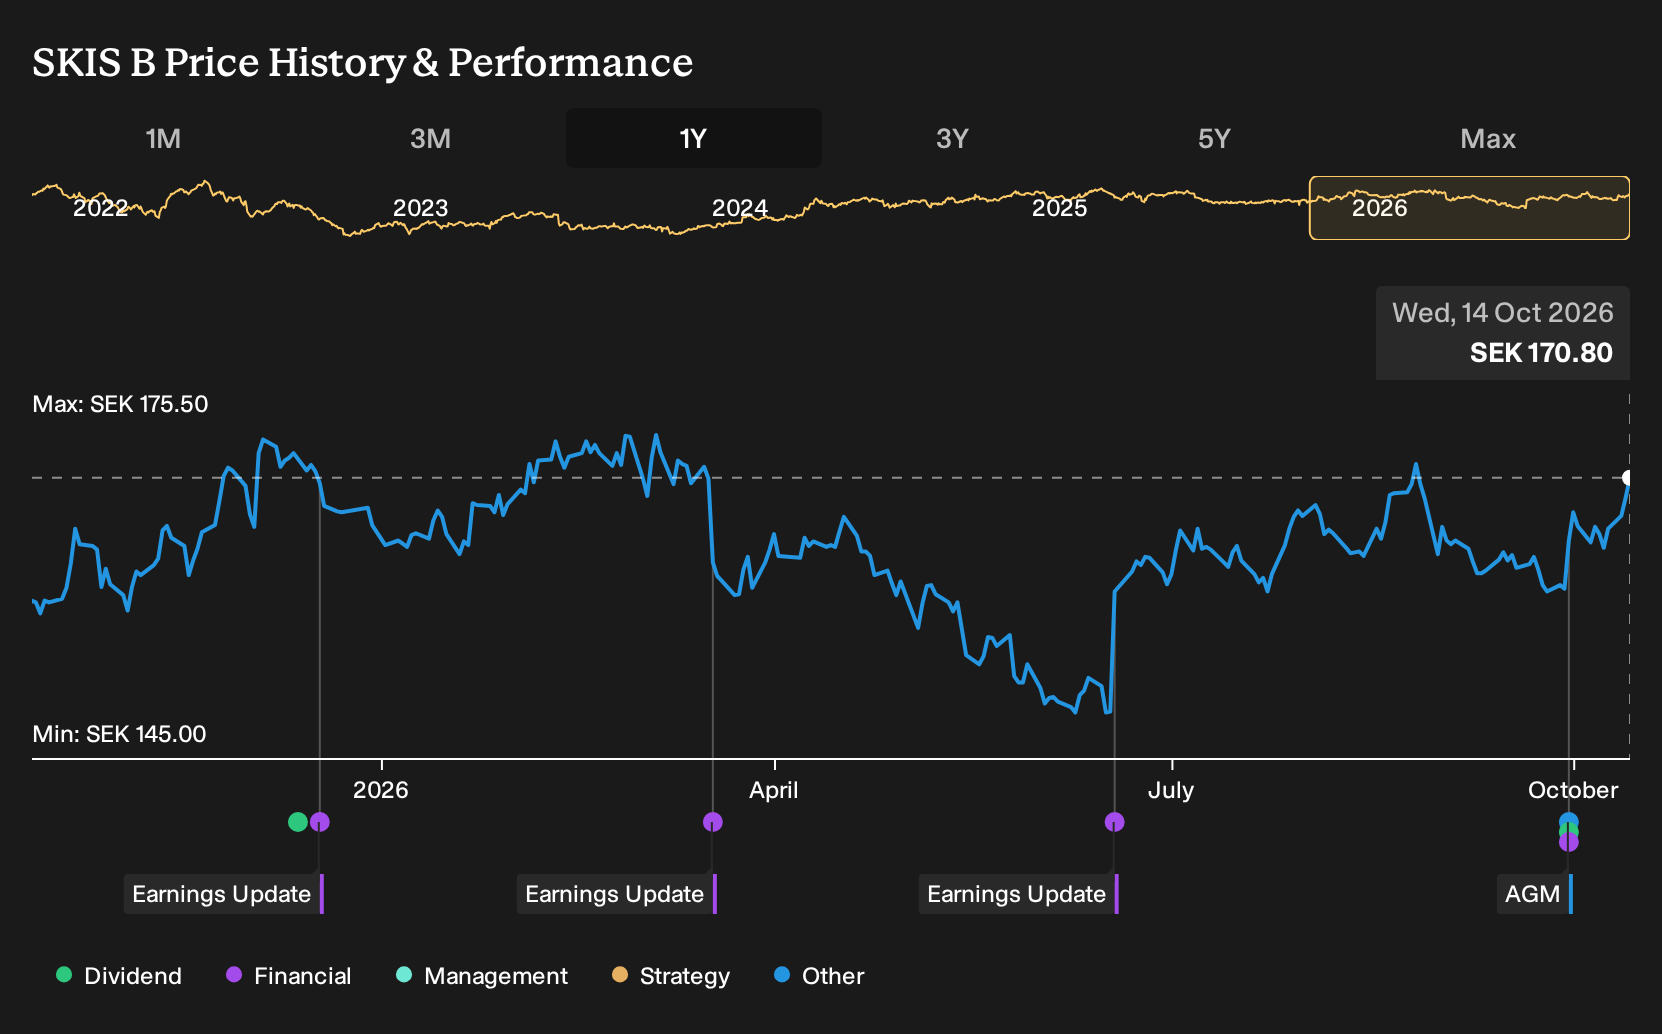
Uncover why SkiStar's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community bracket SkiStar between about SEK 192 and SEK 231 per share, a fairly wide band for such a small sample. These retail investors clearly do not agree, which makes sense when weather risk, heavy resort investment and the fresh dividend proposal all pull the story in different directions. Explore those conflicting views before deciding how SkiStar fits your own income and growth mix.
Explore another SkiStar fair value estimate, including one that suggests it could be worth just SEK191.67.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your SkiStar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SkiStar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SkiStar's overall financial health at a glance.
Looking for more SkiStar style investment ideas?
If SkiStar has sharpened your focus on dividends, quality and risk, it can help to widen the lens and compare it with other listed businesses that share some of those traits.
- If you want income that leans on robust cash generation, scan a curated 217 dividend fortresses that prioritise payout strength with financial resilience.
- If value is your starting point, sort through a focused 187 high quality undervalued stocks that combine quality fundamentals with pricing that may look appealing.
- If capital preservation sits high on your list, filter for companies in a 224 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com