
How Lowe's Vendor Award At Trex Company (TREX) Has Changed Its Investment Story
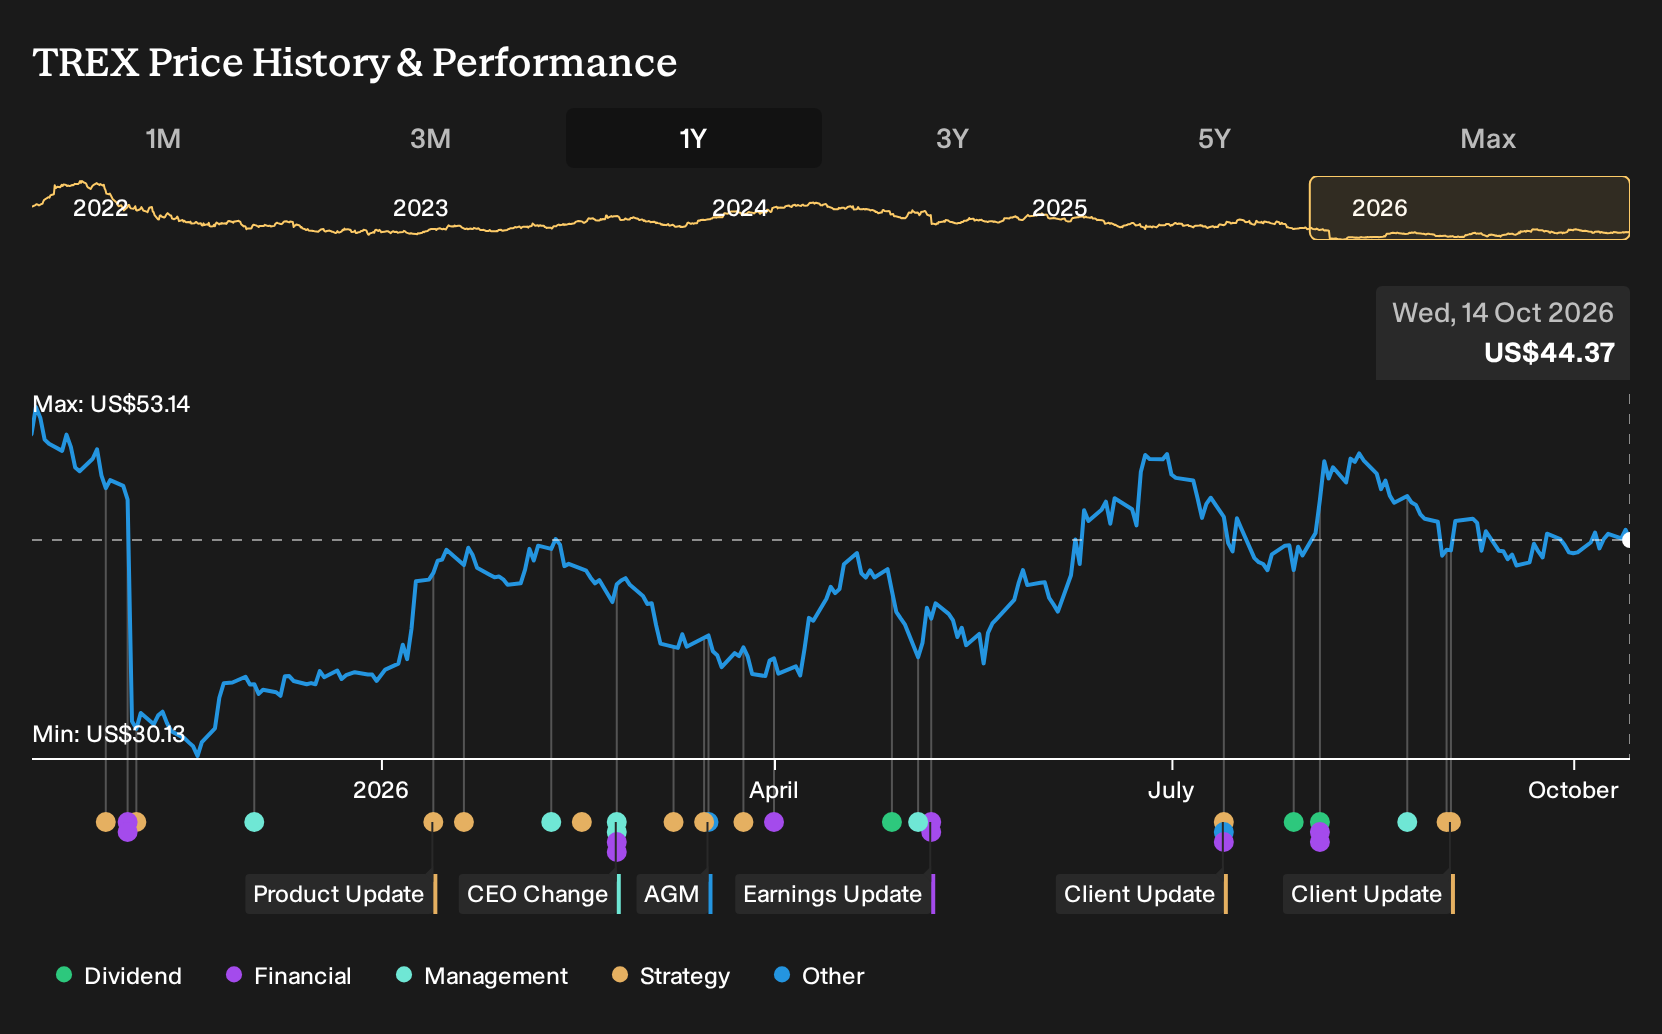
- Lowe's recently named Trex Company its 2026 Building Products Vendor Partner of the Year, citing Trex's composite decking execution, exclusive Trex Select Aluminum Railing launch, and added production capacity that supported double digit unit growth in one of Lowe's fastest growing categories.
- This award signals that Trex is becoming a more embedded supplier in a key retail channel, with its broader four season outdoor living portfolio, including new Trex Lighting, giving retailers and contractors more ways to keep the category selling beyond the traditional decking season.
- We will examine how Trex's recognition by Lowe's as a top vendor partner feeds into the existing composite decking investment narrative.
Scan how retailers are leaning into outdoor living momentum by reviewing the hand picked 20 high quality undiscovered gems that could be building similar behind the scenes demand stories.
Trex Company Investment Narrative Recap
To own Trex Company, you need to believe composite materials keep taking share from wood and that outdoor living remains a priority spend category. The immediate swing factor is whether higher capacity and broader product offerings translate into cleaner execution. Lowe's recognition helps validate Trex's position at a key channel partner, but it does not change the near term thesis on its own.
The more pressing issue is margin quality. Management still has to work through mix headwinds, depreciation from the Little Rock facility and manufacturing inefficiencies that already weighed on earnings. If those pressures linger, or SG&A stays heavy at about 18% of sales, the story around operating leverage and free cash flow improvement looks weaker.
The Lowe's award ties directly into Trex's push beyond boards into full outdoor living systems, especially as the retailer called out composite decking execution and the Trex Select Aluminum Railing launch. That matters for the catalyst around using existing extrusion and distribution muscle to support more revenue per project without duplicating past capex intensity.
Outdoor living becoming more of a four season category, with Trex Lighting extending use into evenings, aligns with the thesis that the firm can sell more accessories around each deck. The opportunity is clear. The test is whether these add on products deliver better product mix and utilization at Little Rock fast enough to offset prior pressure on margins and returns on capital.
What The Current Trex Company Consensus Is Pricing In
Trex Company now sits on a set of analyst assumptions that try to match its Lowe's momentum with hard numbers. Consensus models call for revenue to grow at 6.6% a year over the next three years, with profit margins moving from 14.7% today to 16.0% by around 2029. On that view, earnings would step up from US$177.4 million today to US$234.1 million, which is an increase of roughly US$56.7 million, with earnings per share reaching US$2.41 if share count keeps shrinking at about 5.03% a year.
To line that story up with current price targets, analysts are effectively asking investors to evaluate a 2029 setup where Trex Company generates US$1.5b of revenue and US$234.1 million of earnings. The implied P/E on those numbers is 26.1x, compared with 25.0x today and above the 19.7x multiple cited for the wider US building group. That gap reflects expectations for margin repair at the Little Rock plant and a stronger mix from accessories sold alongside decking through channels such as Lowe's.
Trex Company's narrative projects US$1.5b revenue and US$234.1 million earnings by 2029. This assumes 6.6% yearly revenue growth and an earnings increase of about US$56.7 million from US$177.4 million today.
Uncover why Trex Company's fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate Trex Company storyline leans hard into the catalyst of faster wood to composite conversion. The most optimistic analysts were already penciling in revenue of about US$1.6b and earnings near US$243.6 million by 2029, compared with the US$1.5b and US$234.1 million in the baseline. Those projections came before this Lowe’s award, so if you are weighing Trex today, treat this as a live debate and explore a range of views rather than anchoring on any single forecast.
Explore 2 other Trex Company fair value estimates, including one that suggests potential upside of up to 61% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Trex Company research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Trex Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trex Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Trex Company?
Once you have a view on Trex Company, it can help to compare that thesis with other businesses that share similar quality traits or risk profiles. The Simply Wall St Screener lets you move from a single ticker to a short list of candidates that fit your preferred mix of balance sheet strength, valuation, and income potential.
- If capital preservation sits high on your list, start with a curated set of resilient companies by reviewing the 32 resilient stocks with low risk scores that may better match your tolerance for drawdowns.
- When you want stronger fundamentals and cleaner finances, broaden your watchlist through a list of solid balance sheet and fundamentals (25 results) that can help you compare Trex Company to businesses with similar financial resilience.
- For investors who place income at the center of their approach, scan a focused pool of high-yield opportunities using the 8 dividend fortresses and see how those payouts line up with your own cash flow needs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com