
HealthStream (HSTM) Could Be 16% Undervalued As Its Growth Narrative Builds
HealthStream (HSTM) has attracted fresh attention after a recent share price move, prompting investors to reassess what the current valuation implies for its healthcare software business and future capital deployment choices.
Recent trading has been brisk, with HealthStream’s share price gaining 7.79% over the past week and 15.94% over the last month. The 1-year total shareholder return of 31.40%, alongside a 3-year total shareholder return of 52.35%, points to momentum that has been building rather than fading.
Scan for other healthcare software stocks showing similar strength by reviewing the curated list of 20 high quality undiscovered gems alongside HealthStream.
HealthStream has run hard in a short span, which tempts some investors to lock in gains while others consider starting a position now. The key question is whether the recent move is already pricing in the value on offer, or if it is not yet fully reflected.
Most Popular Narrative: 16% Undervalued
HealthStream’s most followed thesis pegs fair value at $40.00 per share versus the latest close at $33.75. This frames the recent rally as only part of the story rather than the finish line for this healthcare software stock.
The combination of 97% subscription revenue, no debt, cash of roughly $57 million to $66 million and consistent free cash flow mentioned alongside active dividends, buybacks and acquisition spending gives HealthStream flexibility to increase investment in hStream, AI and career networks. This could translate into higher long term subscription revenue and support future operating margin leverage.
See why 1 investors see HealthStream as 16% undervalued.
Result: Fair Value of $40.00 (UNDERVALUED)
Still, the bullish HealthStream story frays quickly if higher cloud and software costs bite into margins, or if legacy product declines outpace newer subscriptions.
Find out about the key risks to this HealthStream narrative.
Another View: HealthStream On Earnings Multiples
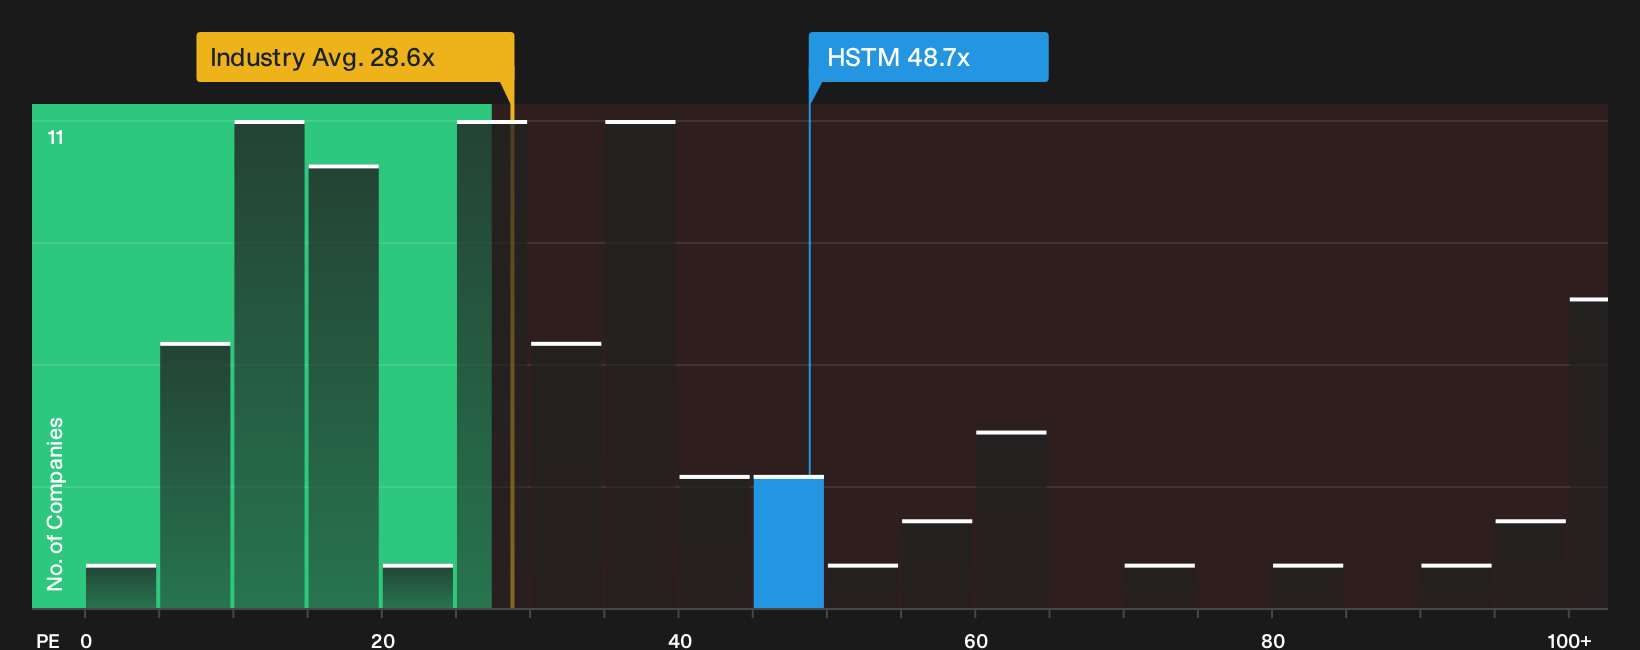
There is a different read on HealthStream when using its P/E. The shares trade on 48.7x earnings, slightly below close peers at 51.6x, yet well above the broader Global Healthcare Services group at 28.7x and the fair ratio of 20.7x that the market could move toward.
That gap implies investors are already paying up for quality earnings, so any disappointment could hit sentiment faster than the bullish narrative suggests. The key consideration is whether the current subscription model and capital allocation justify that premium.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out HealthStream for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around HealthStream is mixed, with clear positives on one side and flagged issues on the other. Move quickly, test the numbers yourself and weigh both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond HealthStream?
If HealthStream has sharpened your focus, do not stop here. Cast the net wider so you are not relying on a single opportunity.
- Target dependable compounders by scanning a fresh set of quality candidates in the 32 high quality undervalued stocks.
- Prioritise resilience first by running through a 32 resilient stocks with low risk scores that spotlights companies with sturdier profiles.
- Hunt for overlooked potential before others catch on by using the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com