
Should Lower EBITDA Guidance Require Action From Tennant (TNC) Investors?
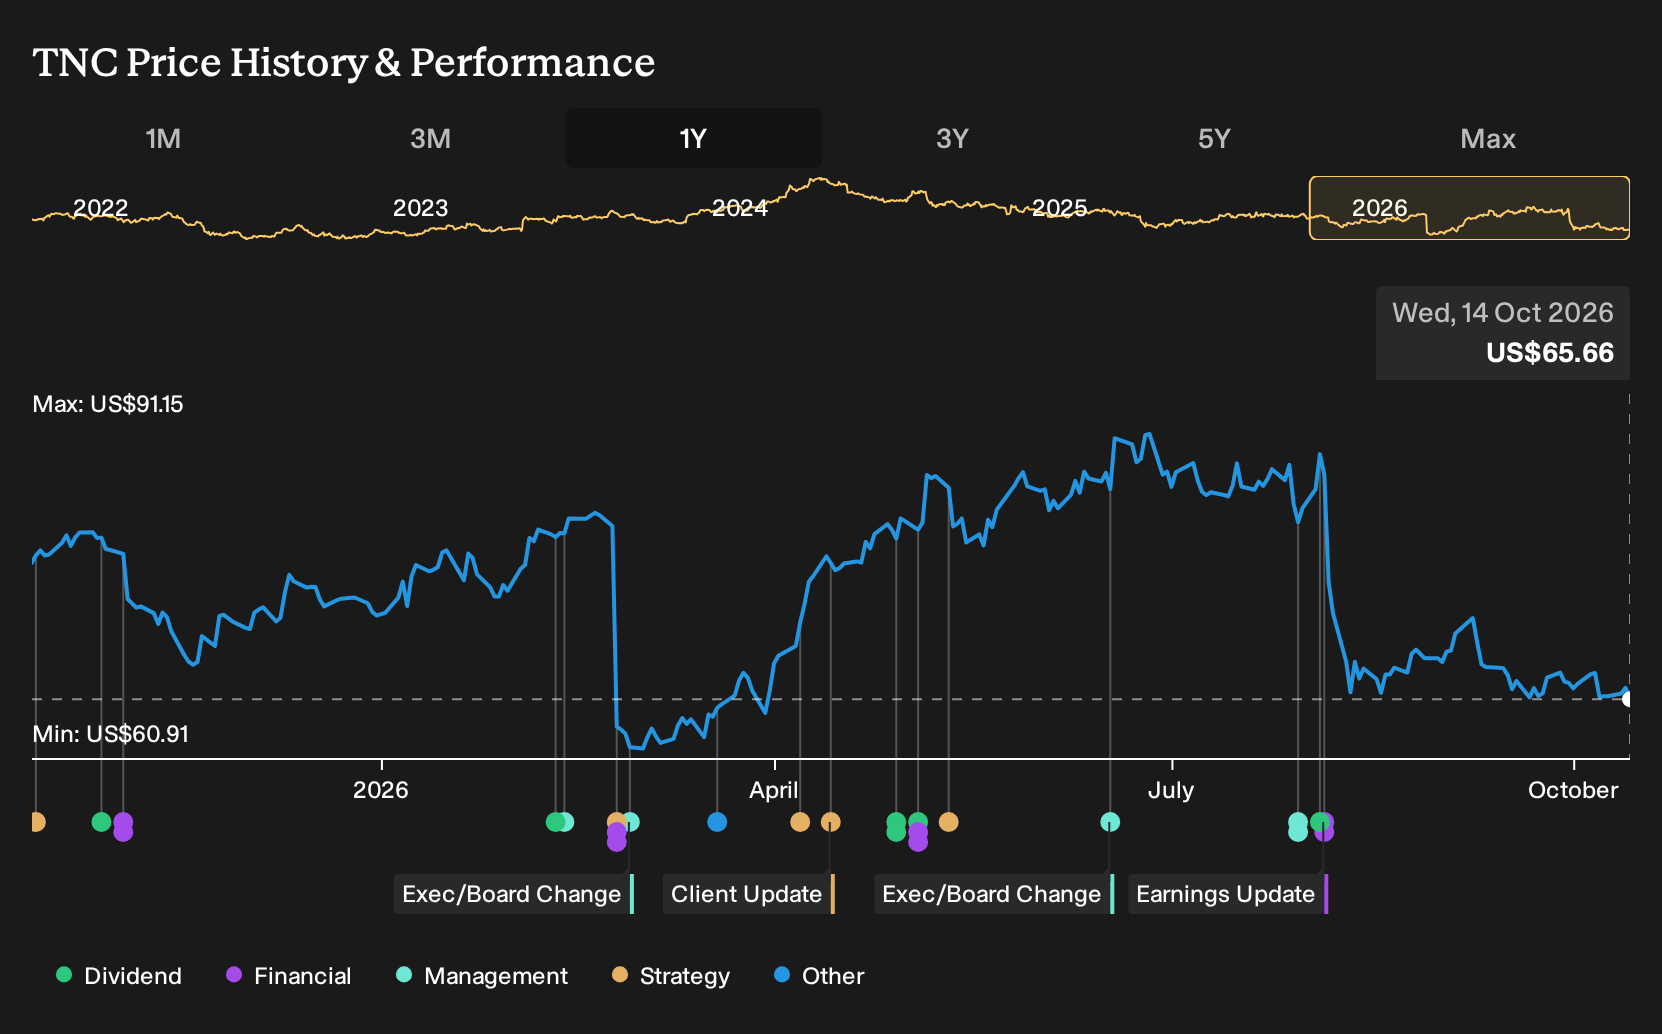
- Tennant reported Q2 revenue of US$324 million, up 1.7% year on year, which fell short of analyst expectations and came with full year EBITDA guidance that materially missed estimates.
- The softer profit outlook highlights how ERP disruption, regional margin pressure and the mix of autonomous cleaning offerings are now central to Tennant's operating story.
- We will explore how Tennant's weaker full year EBITDA guidance interacts with the existing robotics focused investment narrative and what that means for investors.
Contrast Tennant's guidance reset with other cleaning and automation plays by scanning our hand picked list of 90 robotics and automation stocks that are also exposed to the robotics and autonomy trend.
Tennant Investment Narrative Recap
To own Tennant, you need to buy into a fairly simple idea. The future of this business leans heavily on autonomous cleaning equipment and a cleaner, more efficient ERP backbone that can turn its order book into healthier earnings. The softer Q2 and weaker full year EBITDA guide point to a slower reset in profitability rather than a broken robotics story.
The more immediate swing factor is ERP execution. Disruption has already caused lost sales, extra costs and delayed margin recovery into the first half of 2027, and the latest guidance underlines that this remains the main operational drag. The biggest current risk is that further regional pricing pressure and ERP fixes keep compressing already thin net margins.
Against this backdrop, the previously outlined target of about US$250 million in robotics revenue by 2028 and 10 planned product launches still frames the long term upside case. Robotics sales in the first half of 2026 grew 56%, and that segment, if converted efficiently through a stabilized ERP platform, is what many investors are watching as the key quality shift in Tennant’s earnings mix.
The extension of the Brain Corp partnership through 2029, along with the BrainOS Clean 2.0 and SelfPath AI rollout, is the announcement that ties closest to that thesis. It directly affects how quickly customers can deploy autonomous machines, how reliably they operate and, in time, how Tennant might hold or improve pricing power, all of which matter if regional competition and ERP related friction linger longer than hoped.
Tennant earnings and valuation expectations
Tennant's narrative projects US$1.5b revenue and US$131.1 million earnings by 2029. That profile assumes 6.5% yearly revenue growth and an earnings increase of about US$112.8 million from US$18.3 million today.
Uncover why Tennant's fair value indicates a 34% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic Tennant analysts were leaning hard into faster AMR adoption as a key upside catalyst, with forecasts for about 7.0% annual revenue growth and US$127.0 million in earnings by 2029. Those projections came before this weaker EBITDA guidance, so you should expect that views like this may shift.
Explore 3 other Tennant fair value estimates, including one that suggests there may be as much as 34% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Tennant research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Tennant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tennant's overall financial health at a glance.
Looking for more Tennant investment ideas?
If Tennant has sharpened your focus on quality, it can be useful to line it up against other stocks with different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can help you compare Tennant with peers that also carry low leverage and strong fundamentals.
- If your priority is a smoother ride, check out a 32 resilient stocks with low risk scores that focuses on companies with more stable risk scores and fewer red flags.
- Those hunting for underappreciated stories can review a 20 high quality undiscovered gems that filters for stocks with solid fundamentals that are not widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com