
Missed Out On UBS Group's Run? Here's The Bet Holders Made
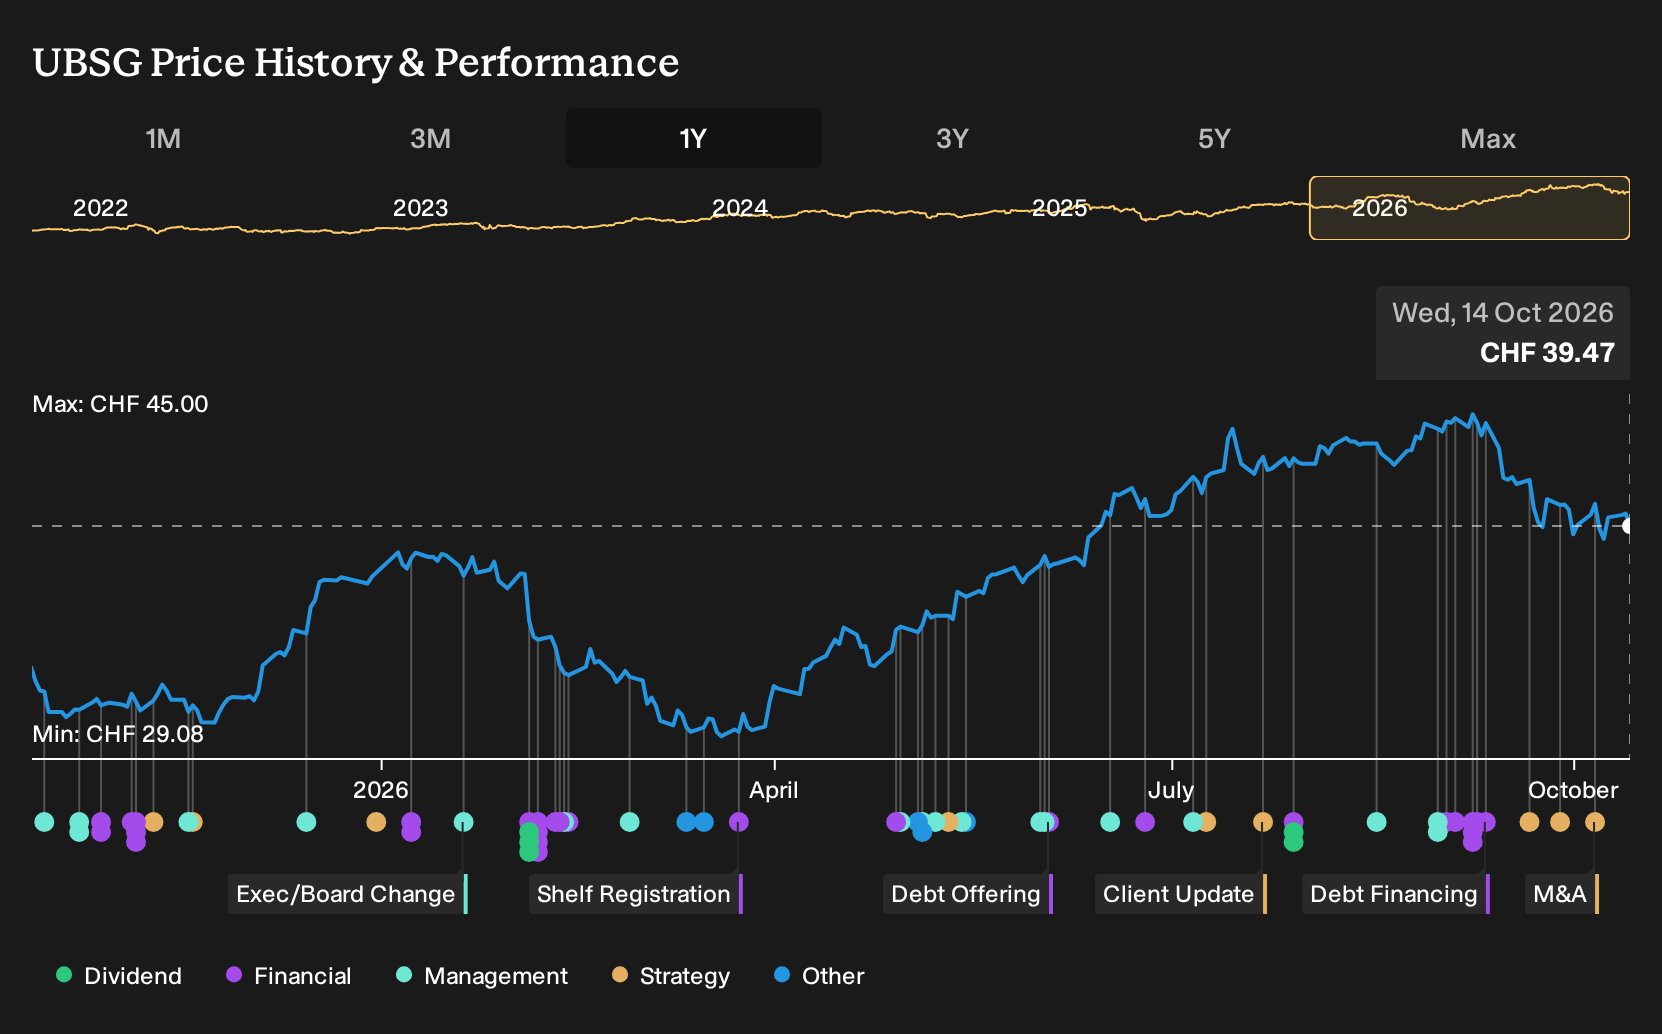
UBS Group’s latest headline moment was a Q2 2026 update that put net profit at US$2.8b and showed the Credit Suisse integration still moving forward. Holding UBS Group over the past year would have returned 29.2%, including dividends. If you had been weighing a purchase back on 14 October 2025, what exactly would you have needed to believe about capital rules, digital banking and wealth inflows before this news ever arrived?
UBS Group has already moved. See which of 188 high quality undervalued stocks still trade below our estimates.
The Argument UBS Investors Were Really Weighing
The shares cost CHF31.8 at the start of the period, and anyone looking at UBS Group had to choose between two very different stories about what that price already assumed.
The bullish view said the stock was worth CHF37 as a rough implied future price if things went right, based on UBS squeezing more out of the Credit Suisse deal and using digital tools and AI to improve wealth management margins.
The bearish camp put Fair Value at CHF21 on their own implied scenario, anchored in the risk that tougher Swiss capital rules, with up to US$42b of extra capital, would drag on returns and limit future payouts.
What The UBS Evidence Actually Tested
UBS Group’s key data point was Q2 2026 results, with revenue at US$13,581m and net income at US$2,800m, compared with US$11,852m and US$2,395m a year earlier. Net margin edged up from 20.2% to 20.6%. Strong Q1 and Q2 profits, progress on Credit Suisse integration and large invested assets supported the optimistic case, while capital rule debates and the US$125m AML penalty challenged it. Overall, the evidence cut both ways.
The useful takeaway is simple. When a bank story hinges on regulation, capital intensity and digital execution, you test that by tracking reported net margin, absolute capital buffers and concrete items like buybacks or fines, not just headline profit. Apply the same lens to any large lender that promises higher returns from technology, consolidation or laxer capital demands.
What UBS Group's Price Already Bakes In
UBS Group now trades at CHF39.47, after a 29.2% move over the past year. The selected Narrative’s Fair Value sits below that quote rather than above it.
The Narrative leans on solid earnings and Credit Suisse progress, and it also asks whether extra Swiss capital, legal costs and restructuring risk could still crimp the long run payoff from those foundations.
"Key Takeaways: Bearish analysts expect UBS Group to see its profitability and capital return capacity squeezed, as higher Swiss capital requirements and ongoing legal and integration costs weigh on returns. The main factor that has to go right is that UBS Group converts Credit Suisse integration progress, wealth and alternatives growth, and technology investments into sustainably high returns despite rising regulatory capital pressure."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where UBS Questions Point Next
Thinking about UBS Group highlights one theme. Regulated lenders often chase fee income while avoiding heavier balance sheet risk.
Another finance platform reflects that tension differently. Instead of holding loans, it focuses on providing rails for people and merchants to move money.
It still relies on banks in the background, yet keeps its own model relatively light. Renting balance sheets may reduce margin, but helps preserve flexibility.
When higher capital demands trouble pure banks, this structure offers a contrast. The trade off between tighter regulation and freer cash returns looks very different here.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 46% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com