
3 Renewable Energy Stocks To Watch In October 2026
Gas prices in the US have stayed above $4 a gallon for a record stretch in 2026, and that kind of sticker shock at the pump keeps clean power in the spotlight for investors. Expensive fuel highlights the appeal of companies that build or run energy projects not tied to oil. This article discusses three stocks from the renewable energy screen that may be relevant if you are considering ways to reflect that shift in your portfolio.
The three stocks below are just a starting sample from the renewable energy idea, and the full screen surfaced 20 more companies with equally compelling narratives that are not covered here. If you want to identify potential front runners for your watchlist, head straight into the Renewable (solar, wind, hydro or tidal) Energy screener to filter and analyze the broader set of renewable opportunities.
Clearway Energy (CWEN)
Clearway Energy runs a large mix of renewable projects and gas fired plants across the US, and its utility scale wind, solar and battery storage portfolio is the clearest link to this screener’s focus on low carbon power generation and grid flexibility.
Clearway Energy, Inc. operates clean power assets across the United States, generating about US$1.25b of revenue from Renewables & Storage and US$320 million from Flexible Generation, and has a market value of roughly US$6.2b.
"Expansion of late stage wind, solar and storage projects, with 100% of 2026 and 2027 vintages already commercialized and a 2028 to 2029 pipeline larger than what is needed for internal CAFD targets, gives the company multiple ways to add contracted capacity that can lift CAFD and support dividend coverage."
The real swing factor is how a single constraint on future financing terms ultimately filters through to cash flow growth and dividend headroom.
That financing question is only the starting point, and the full narrative for Clearway Energy explains how Clearway Energy’s contracted pipeline could accelerate or stall future payout capacity.

Ormat Technologies (ORA)
Ormat Technologies is a pure play on geothermal power in this screener, combining electricity generation, equipment manufacturing and energy storage that all contribute to clean baseload supply rather than fuel driven capacity.
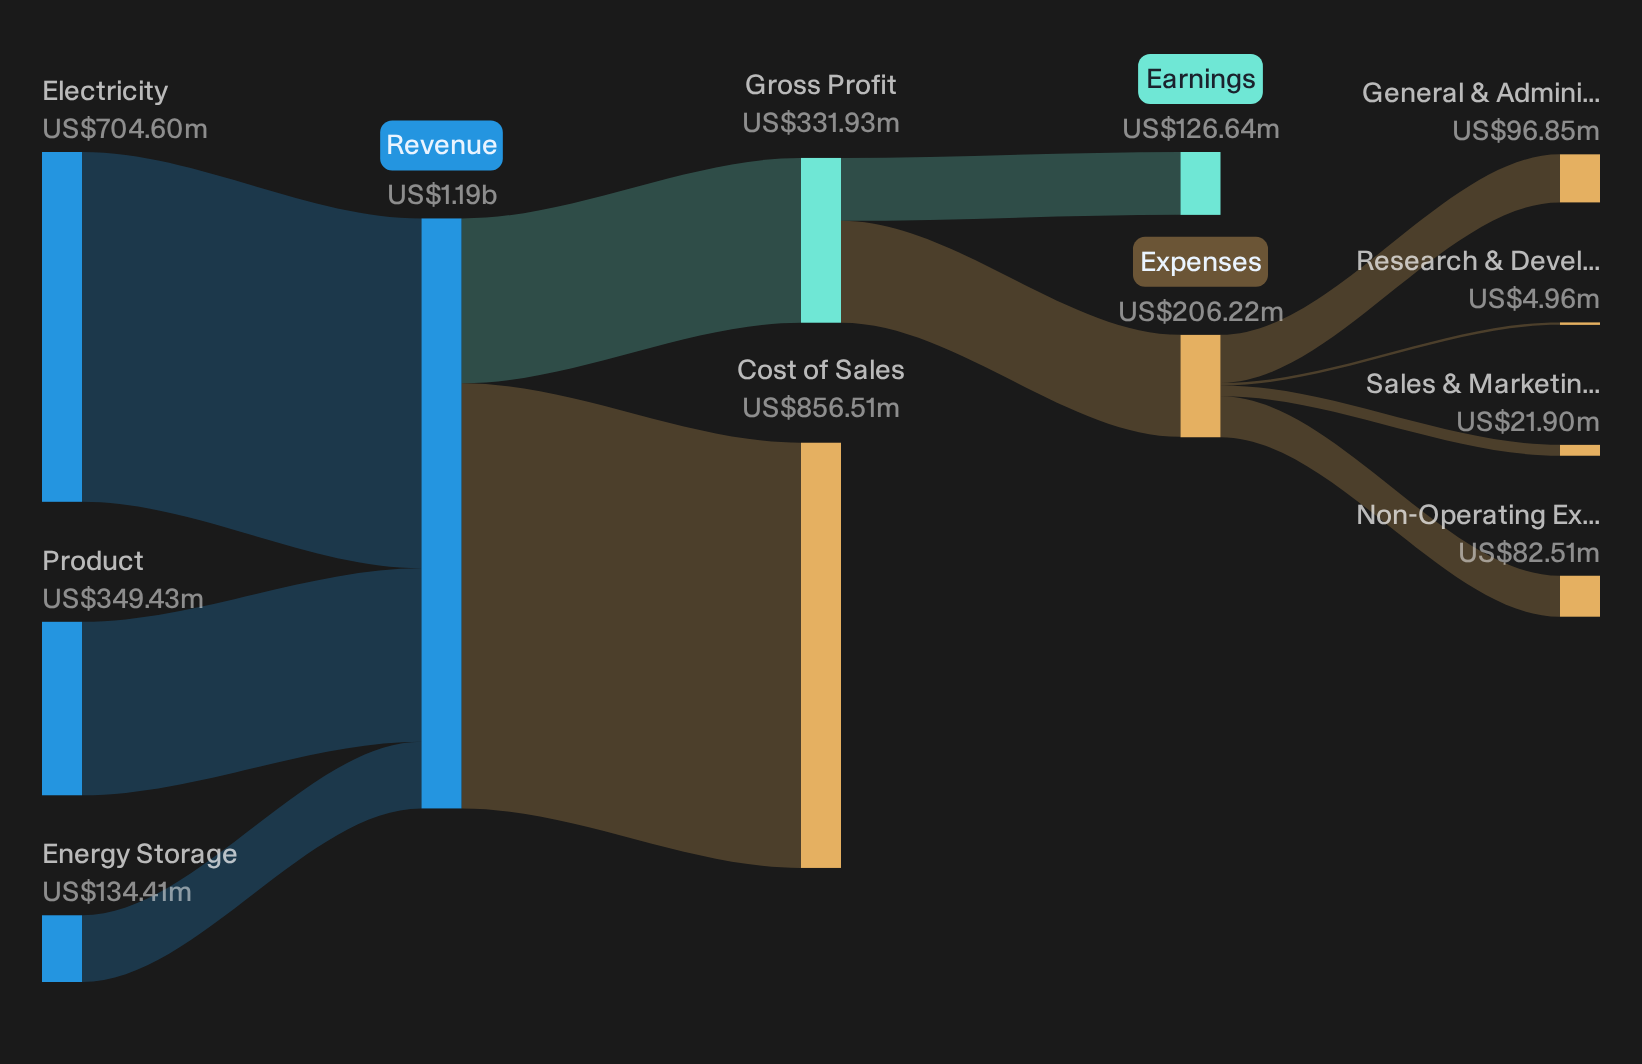
Ormat Technologies runs geothermal and recovered energy power plants worldwide, with about US$705 million from Electricity, US$349 million from Product and US$134 million from Energy Storage segments, and a market value near US$5.6 billion.
"Recent U.S. federal permitting reforms and policy support have significantly expedited geothermal project development timelines for the company, enabling it to accelerate greenfield expansion and release more projects for construction."
For investors, an important consideration is how one unresolved cost pressure may influence future profitability as this geothermal build out continues.
That cost pressure is the crux, and the full narrative for Ormat Technologies shows how Ormat Technologies could balance project acceleration with returns while the geothermal story keeps building.
ReNew Energy Global (RNW)
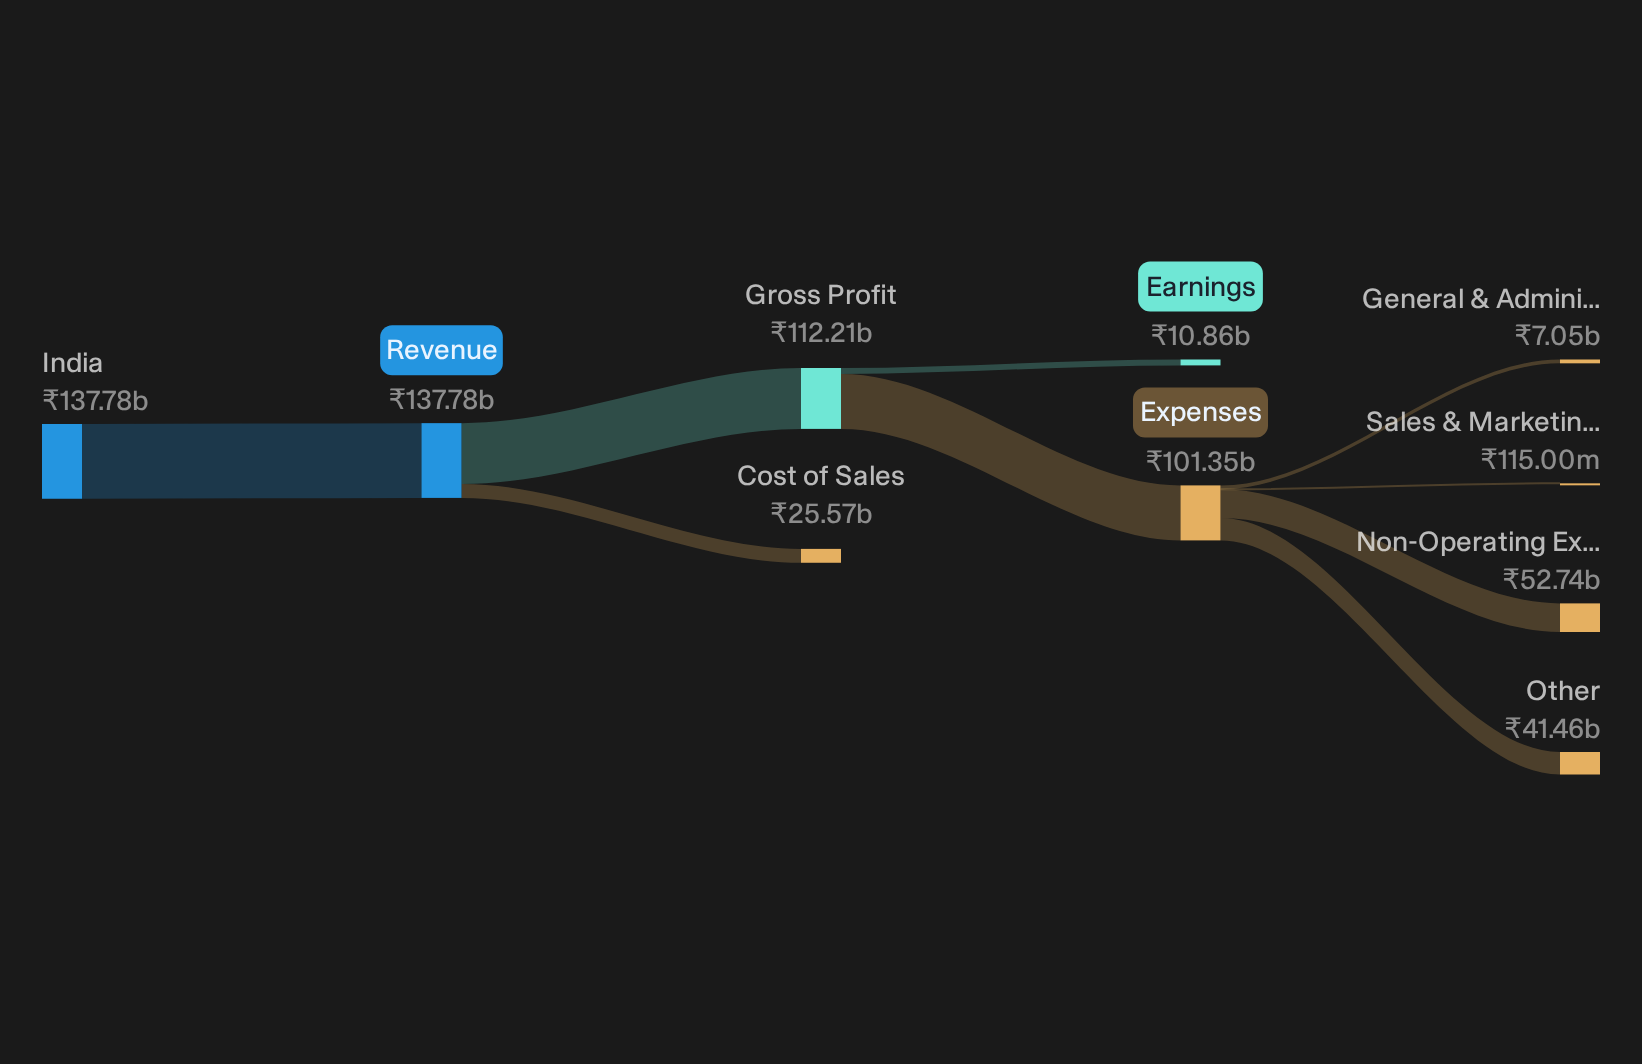
ReNew Energy Global runs a large, India focused clean power platform, owning and operating utility scale wind and solar projects while also manufacturing solar modules and supplying EPC, O&M and transmission services that directly fit the renewable build out theme. It carries a market value near US$2.5b.
ReNew Energy Global ties together generation assets and manufacturing in one vertically linked platform. This can matter for investors looking for direct exposure to large scale renewable build out rather than fuel linked producers.
"ReNew Energy Global is still positioned to benefit from rising global and corporate decarbonization demands as it scales its renewable operating base."
What happens if one less visible pressure on that integrated model ends up setting the tone for margins and growth across the portfolio?
If that pressure point is what could reset returns across ReNew Energy Global, the full narrative for ReNew Energy Global explains how its scale, contracts and risks might be getting misread.
Seeking Fresh Alternatives Beyond Renewables?
Fresh opportunities do not stay quiet for long. Strong stories gain momentum, weak ones start dropping, and the early edge shrinks fast. Scan these ideas before the crowd and act now.
- Consider pairing potential income and defense by reviewing 7 dividend fortresses screened for durability so you are not chasing yield after prices start flying.
- Look for early trendsetters in automation by checking 90 robotics and automation stocks while they are still under the radar for now and before any breakout is fully reflected in headlines.
- Monitor shifting market currents by using list of solid balance sheet and fundamentals (25 results) so you focus on resilient operators rather than stories that appeared strong but are already dropping.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com