
Mader Group Fell While Profit Rose
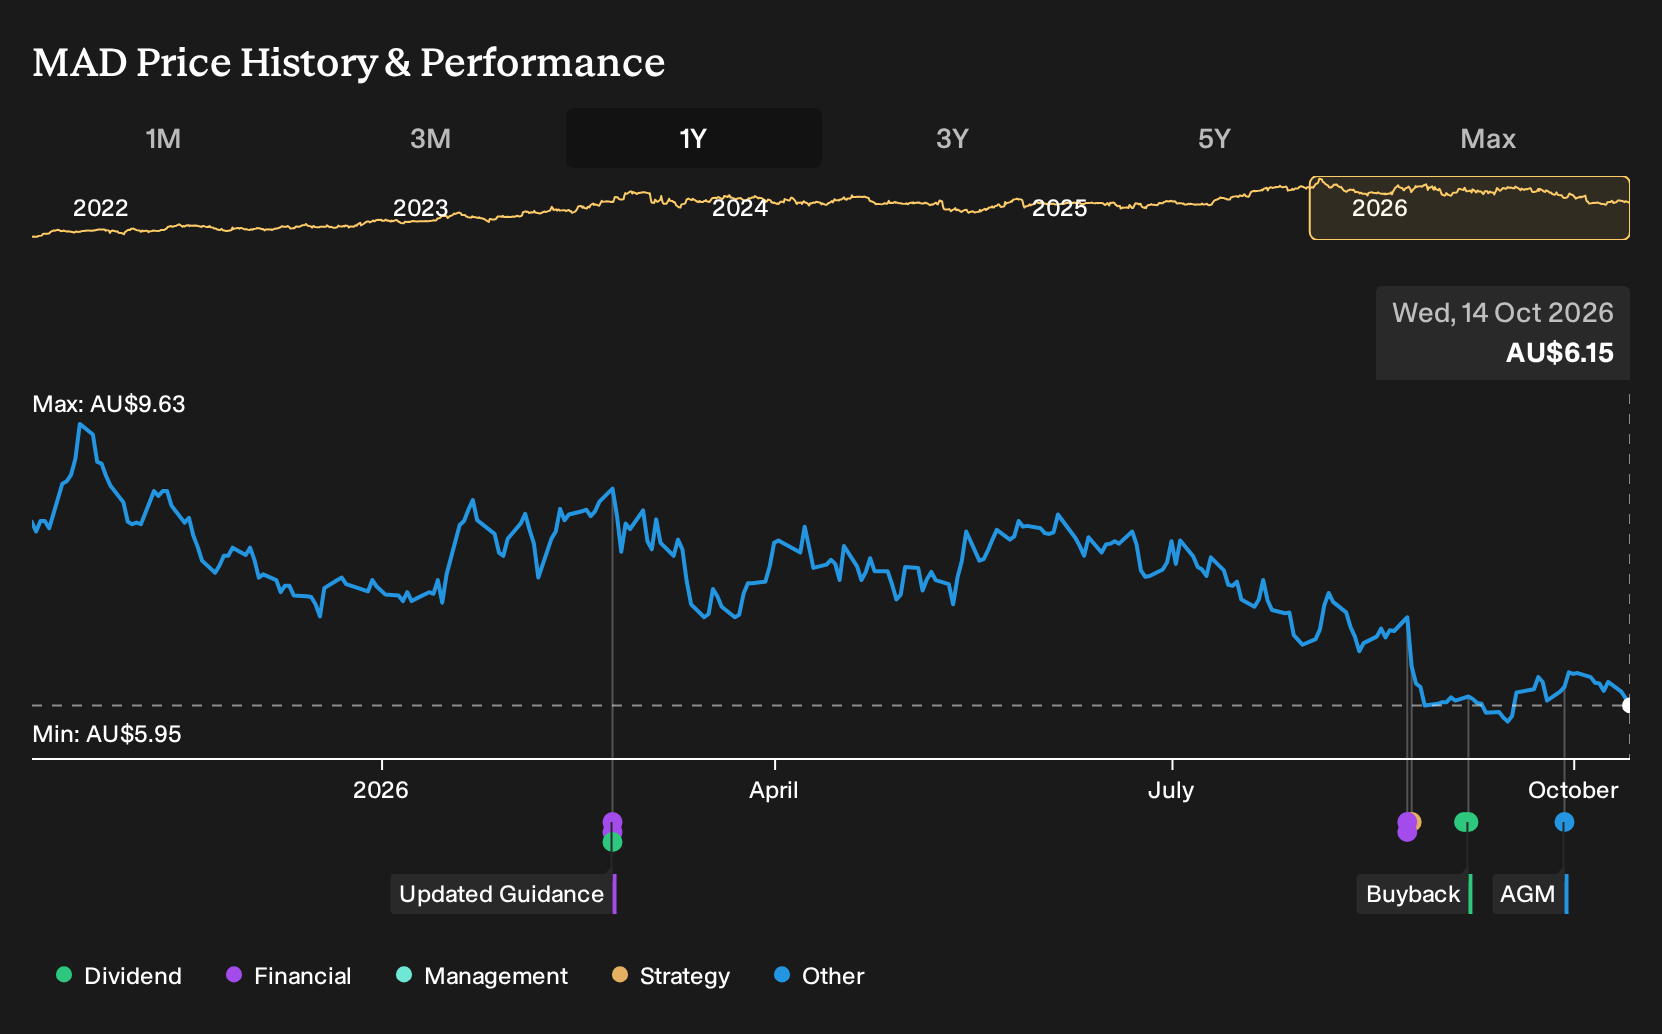
Mader Group had just delivered higher annual revenue and profit, and its shares jumped 4% after a fresh broker note highlighted Western Australia iron ore demand and a new five year growth plan on the horizon. For Mader Group shareholders, the loss over the past year was 27.0%, including dividends. If you had been weighing a position in October 2025, how should this combination of upbeat news and weaker returns influence expectations now?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The move put Mader Group in the middle of this trade. Scan 90 robotics and automation stocks for other companies exposed to it.
The Argument Mader Group Investors Were Weighing Up
The shares cost A$8.3 at the start of the period, and anyone looking at Mader Group then had to choose between two very different but logical stories.
On the optimistic side, the bullish Narrative put Fair Value at A$9, assuming revenue growth of 13.2% with profit margins reaching 7.1% as maintenance demand rose with electrification and renewable projects.
The more cautious view set Fair Value at A$6.15, using the same growth and margin assumptions but stressing the risk that decarbonization and automation could weaken traditional, labour heavy maintenance work and reduce the P/E to 17.8x.
What The Results Changed For Mader Group
The most concrete update for Mader Group was the 2026 report showing revenue of A$1,001.14m and net income of A$65.373m, with net margin at 6.5%. That supported the optimistic call on scale and earnings, yet the slight margin slip from 6.6% also gave the cautious view fresh backing on profitability pressure. The evidence cut both ways.
The hinge assumption here was not just growth but margin resilience. For any other contractor you review, track whether rising turnover is matched by stable or improving net margin rather than relying on headline revenue alone.
Mader Group: What The Fall May Already Be Pricing In
Mader Group now trades at A$6.15, after the share price fell 27.0% over the past year. The selected bullish Narrative sees Fair Value above that level, built on the idea that demand for specialist maintenance can compound as equipment fleets age and become more complex.
The distinctive claim buyers must test is that Mader can keep attracting scarce technical labour and win contracts fast enough that human-led services remain a strength, not a vulnerability, as automation and decarbonization reshape its core markets.
"Mader's consistent success at exporting its unique culture-led business model is attracting and retaining scarce technical labor at scale, allowing it to capture disproportionate share of contract outsourcing from resource companies under pressure to reduce costs. This is expected to structurally expand net margins and earnings resilience."
The price and this Narrative do not agree. → Uncover what this Narrative says Mader Group is actually worth
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 34% below our estimate - supports investment managers by handling outsourced registry, administration and trustee functions.
- Company 2 - 46% below our estimate - secures integrated civil, mining and processing contracts spanning build, run and upkeep.
- Company 3 - 43% below our estimate - fits major venues with unified audio visual, electrical and data infrastructure replacing legacy systems.
Those are three of them. See the full list of 4 companies trading below our estimate →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com