
Netflix (NFLX) Cuts 6% Of Staff As New Content Budget Fight Emerges
- Netflix (NasdaqGS: NFLX) plans to lay off about 1,000 employees, or roughly 6% of staff, in a new cost move.
- The reductions follow slowing user growth and stronger competition from streaming rivals, according to the company.
- A coalition of Hollywood agents and producers is urging lawmakers to require major streamers to spend 50% of content budgets with independent producers.
- The layoffs and proposed indie content quota sit alongside broader shifts in how Netflix funds programming and allocates capital. Our analysis turns up 4 other big wins for Netflix as well.
For readers weighing how this streaming reshuffle could influence other income-focused opportunities, the next place to look is 7 dividend fortresses.
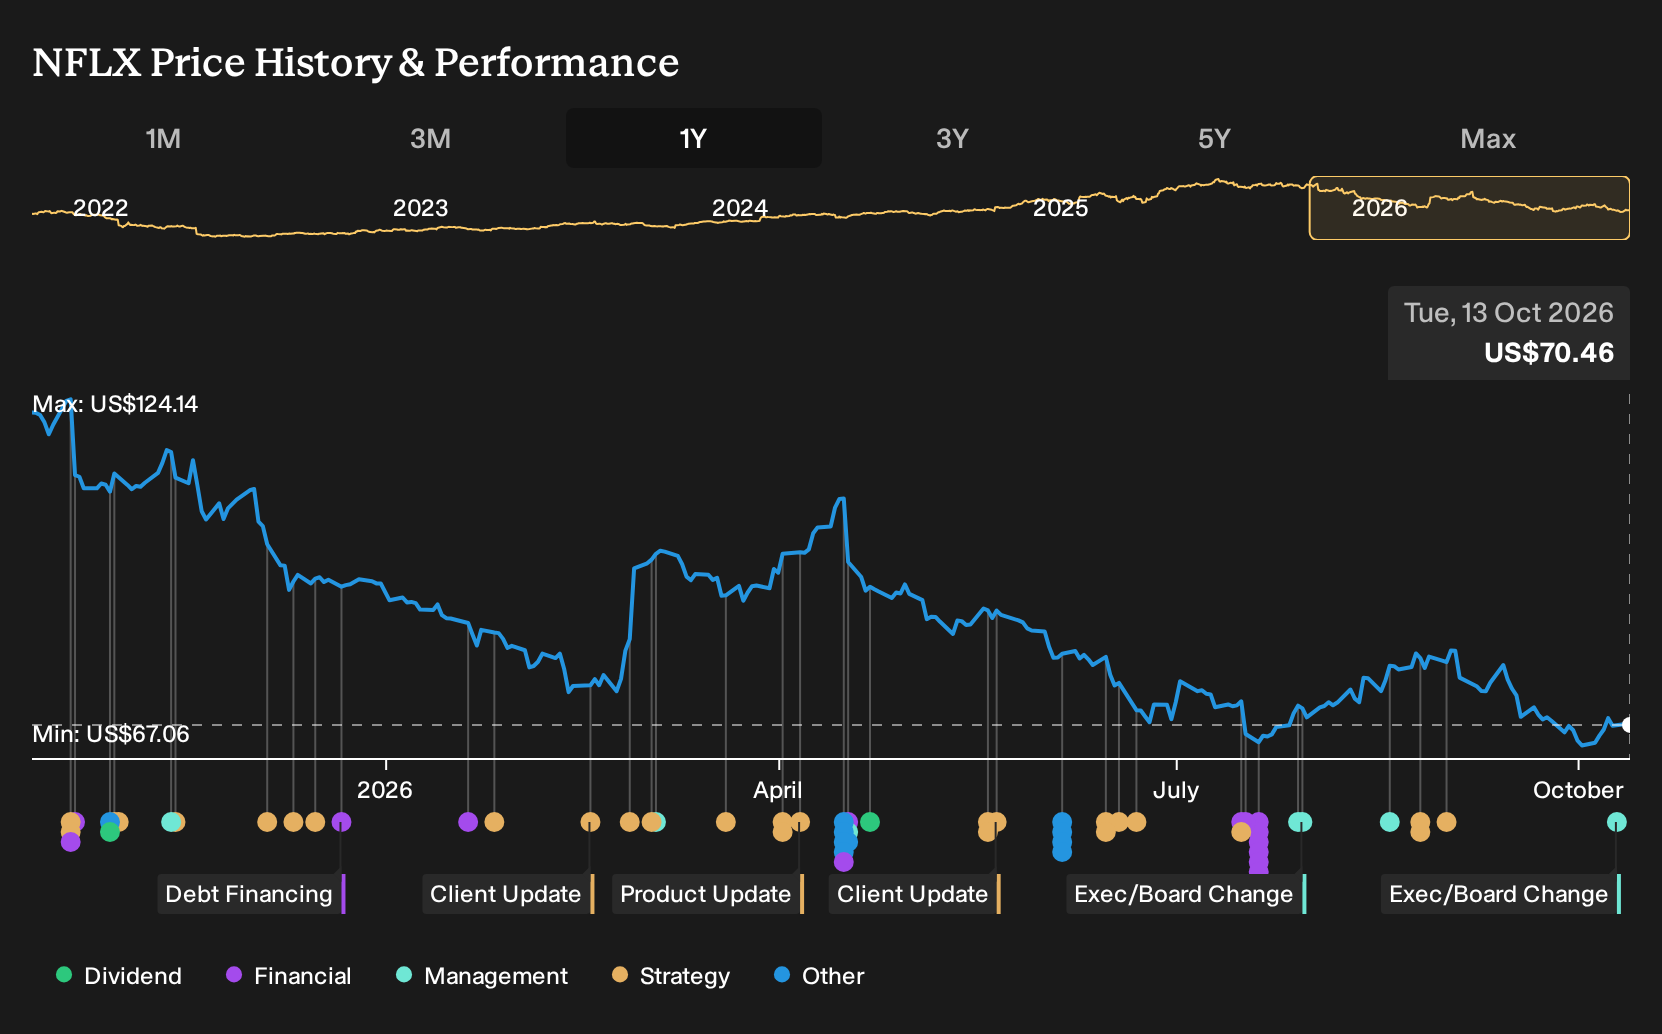
Netflix runs a global entertainment platform that produces and distributes films and series, so any push to direct 50% of content budgets to independent producers could influence how this US$293.4b giant splits spending between in house projects and external partners.
What this Netflix reset really signals for the Narrative
For Netflix investors, the headline is job cuts and possible future content quotas, but the deeper story is how capital and decision making are being reshaped to protect the existing Narrative. The layoffs point to tighter cost control just as the Netflix thesis leans on advertising, live events and margin discipline to support earnings, while bringing Craig Ferguson in as director of content acquisition strengthens the bench on licensing and dealmaking. That combination touches two big Narrative levers: keeping unit content costs in check and using third party deals to support engagement without overspending on in house production.
See how these catalysts shape Netflix's path to a $92.62 fair value.
The clearest test of whether this shift is working will come with the next few quarterly updates, when investors can see how content amortisation, operating margin and ad tier traction are trending against the guided path toward roughly 30% profitability and management’s comments on how any indie quota push might reshape content mix and spending.
The one check on Netflix many readers skip before acting
The part of the Netflix story that rarely gets airtime is where current analyst projections say this business could end up a few years from now, and how that path lines up with what you expect. See where analysts expect Netflix to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com