
What Babcock International Group (LSE:BAB)'s Defence Contract Extension Means For Shareholders
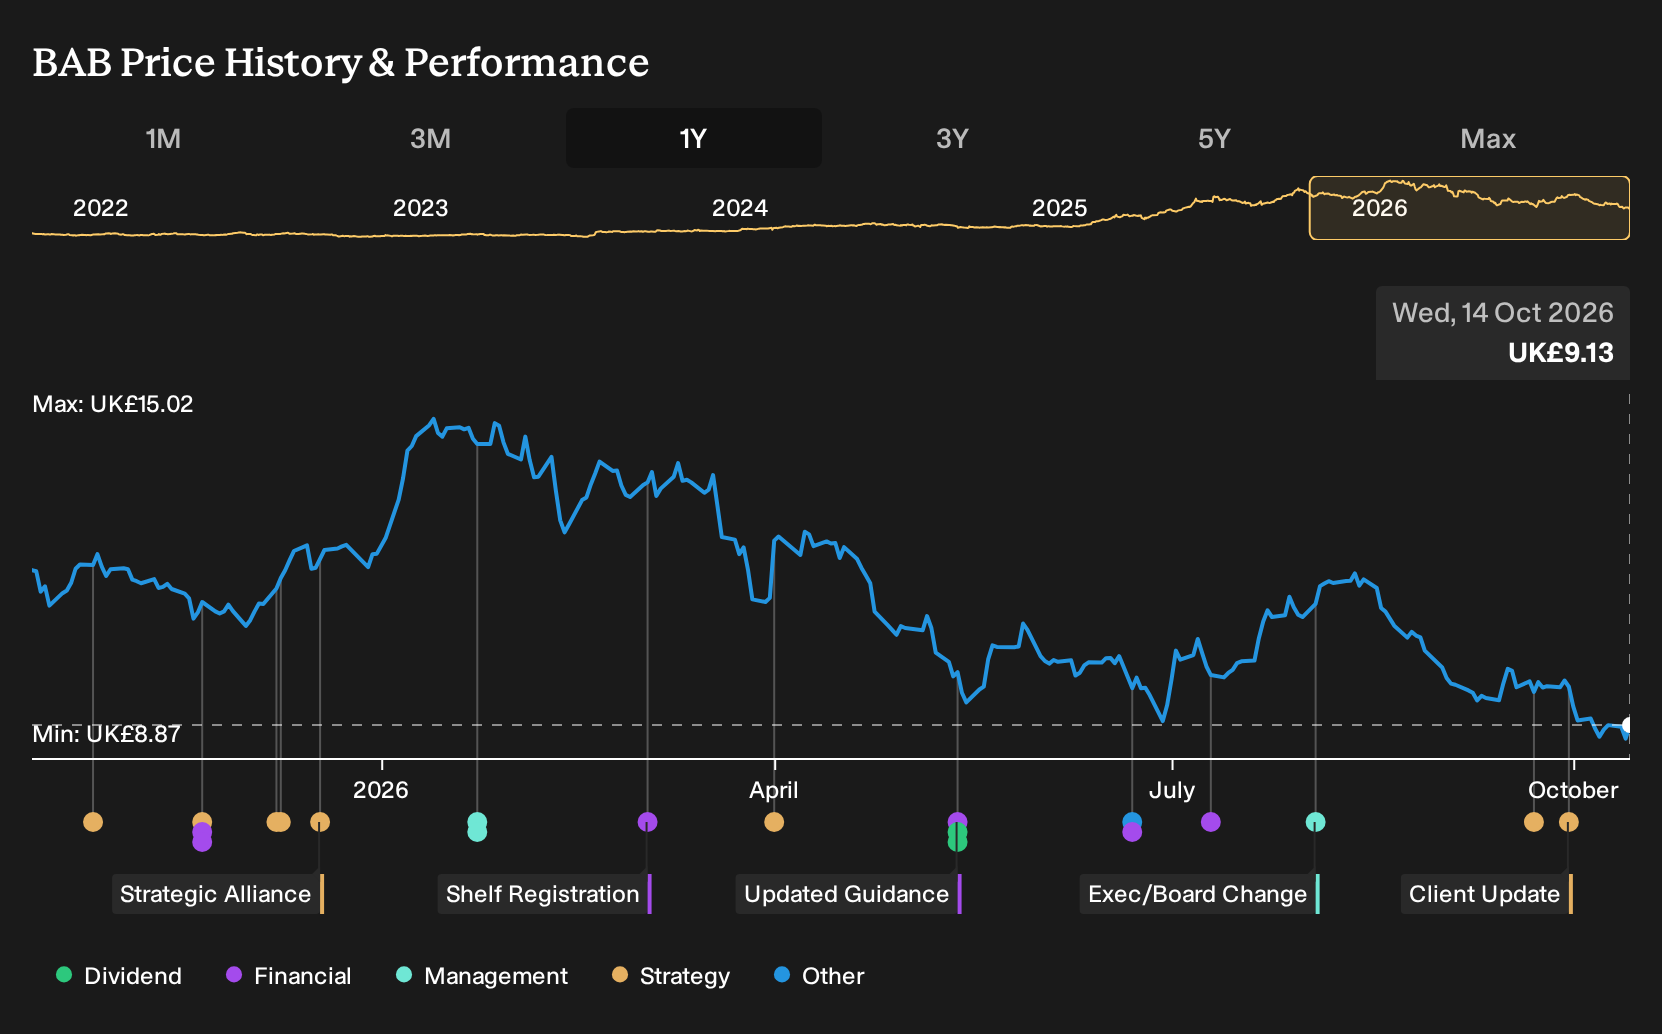
- Babcock International Group agreed a two month extension to its Future Maritime Support Programme bridging agreement with the UK Ministry of Defence from 1 October 2026. This maintains naval base and nuclear submarine fleet support while the longer term Gateway Agreement is finalised.
- The extension keeps Babcock in place as the sole provider of in service submarine support to the Royal Navy, which underpins its role in the UK’s submarine enterprise and the Continuous At Sea Deterrent.
- This development may influence how some investors view Babcock’s investment narrative in light of the extended Future Maritime Support Programme bridging agreement.
Scan how defence contractors like Babcock International Group compare on resilience and balance sheet strength by reviewing the hand picked list of solid balance sheet and fundamentals (9 results) today.
Babcock International Group Investment Narrative Recap
Babcock International Group tends to appeal to shareholders who value long-duration defence contracts, disciplined delivery on complex programs and steady progress on margins rather than rapid top line acceleration. The FMSP extension supports that thesis by keeping core submarine support work in place, but on its own it does not change the short term picture in a major way.
The key near term swing factor remains execution and profitability across Marine and Nuclear, especially where previous profit pressure and overheads were an issue. The biggest risk still sits in cash flow timing and large program working capital, including the chance that earlier favourable cash conversion unwinds and squeezes liquidity.
The extension to the FMSP bridging agreement links directly to earlier commentary around strong operational delivery and frame contracts. A shareholder who already cares about performance linked extra work will probably read this as operational continuity in one of Babcock International Group’s most sensitive support roles, rather than as a fresh growth driver in its own right.
Earlier catalysts such as Skynet mobilisation, improving Nuclear and Land margins and international defence partnerships appear more central to the medium term thesis. The FMSP news mostly interacts with those by reinforcing the idea that dependable execution on critical UK defence work can support order volumes, while any slip in delivery or cost control would quickly feed into the existing risks around margins and cash generation.
Babcock International Group's current analyst narrative assumes revenue will expand at 5.3% per year, reaching about £6.0b by 2029, with earnings rising from £211.2m today to £383.8m. That implies an earnings increase of about £172.6m by the 2029 forecast year, based on a shift from 4.1% profit margins to 6.4% if those projections occur.
Discover why Babcock International Group's fair value points to a 48% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on a very different catalyst. They see the nuclear and defence outlay story around Babcock International Group as the big swing factor, with forecasts for revenue reaching about £6.3b and earnings of £440.7m by 2029 before this FMSP extension, which could prompt fresh views.
Explore 3 other Babcock International Group fair value estimates, including one that suggests potential upside of up to 70% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Babcock International Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Babcock International Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Babcock International Group's overall financial health at a glance.
Looking for more investment ideas beyond Babcock International Group?
If the Babcock International Group story has sharpened your thinking, use that same lens across the wider market by scanning focused lists built from the Simply Wall St Screener.
- For investors who want income at the forefront, start with a shortlist of 3 dividend fortresses that aim to pair higher yields with resilient fundamentals.
- If capital preservation and steadier profiles matter most to you, filter for 4 resilient stocks with low risk scores and see which businesses score well on financial strength and volatility.
- Prefer to hunt for less crowded opportunities, where fewer eyes are on the story? Narrow your search to 5 high quality undiscovered gems that already show solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com