
Is BE Semiconductor Industries (ENXTAM:BESI) Undervalued After Its Applied Materials AI Packaging Partnership?
BE Semiconductor Industries (ENXTAM:BESI) drew fresh attention after Applied Materials expanded their long-running partnership, adding Besi as an Innovation Partner at the new EPIC Center focused on advanced AI-oriented packaging.
BE Semiconductor Industries’ share price has pulled back sharply over the past three months, with a 90 day share price return showing a decline of 26.1%, which has tempered earlier gains. However, the year to date share price return of 17.1% and 1 year total shareholder return of 20.7% still indicate stronger longer term momentum, supported by a 3 year total shareholder return of about 2.1x and a 5 year total shareholder return of roughly 3x.
Scan other chipmakers geared to the same AI packaging buildout by reviewing our curated list of 92 AI infrastructure stocks alongside BE Semiconductor Industries.
BE Semiconductor Industries now trades well below its recent highs, even as the Applied Materials partnership deepens and AI packaging interest builds. Does that pullback already offer a fair entry, or is patience still worth a premium?
Most Popular Narrative: 43% Undervalued
According to the most closely followed narrative on BE Semiconductor Industries, a fair value of €305 sits well above the last close at €174.55. This frames the current weakness as a potential valuation gap rather than just a pullback.
The market’s debate around BE Semiconductor Industries has shifted. The question is no longer whether AI will create demand for advanced semiconductor packaging. BESI’s order book is already providing evidence that it is. The harder question is how much of that future has already been capitalised into the share price. That distinction matters at €204.80. BESI’s underlying business is accelerating at a rate that would normally justify a substantial rerating.
See why 3 investors see BE Semiconductor Industries as 43% undervalued.
Result: Fair Value of €305 (UNDERVALUED)
Still, the story around BE Semiconductor Industries can change quickly if AI related equipment orders slow or if the current high P/E multiples compress.
Find out about the key risks to this BE Semiconductor Industries narrative.
Another View: What BE Semiconductor Industries’ P/E Ratio Implies
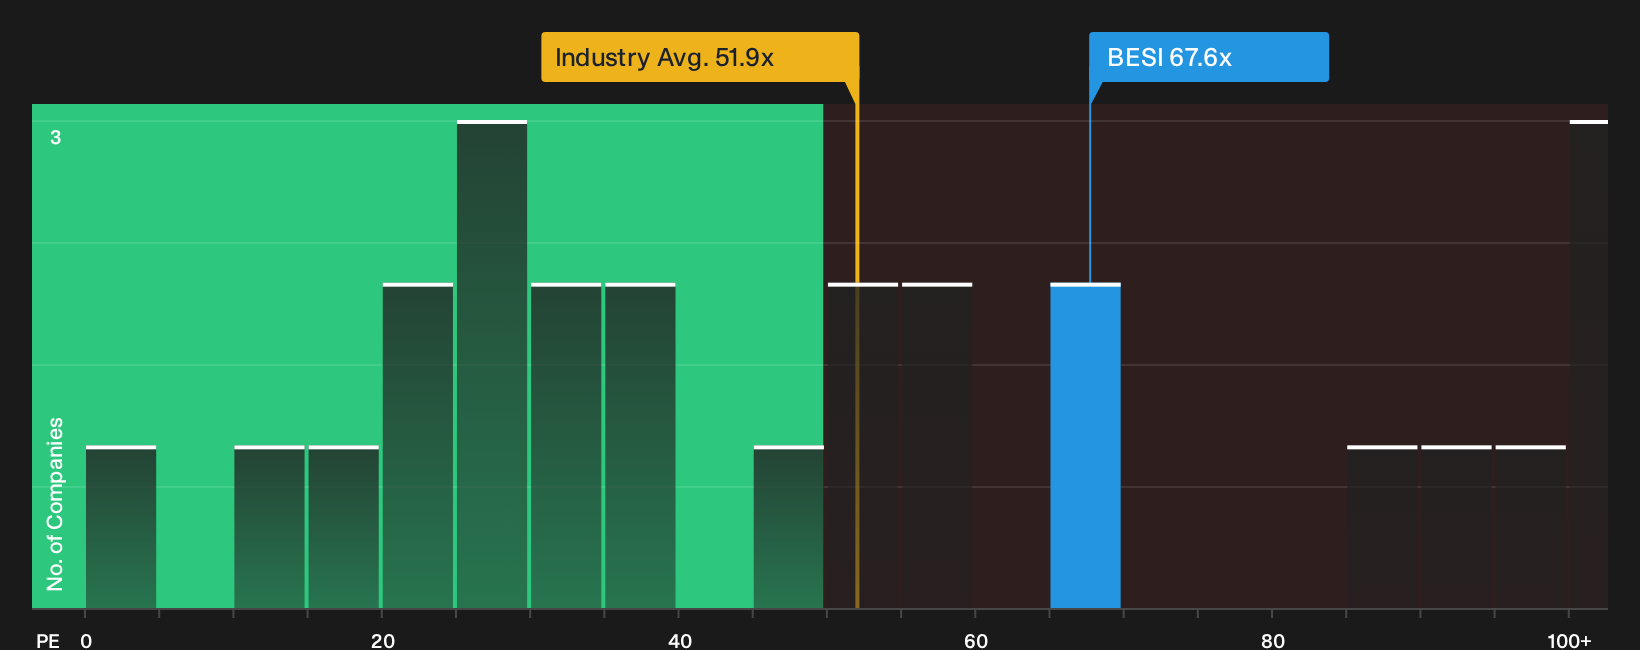
That 43% undervalued narrative meets a very different signal once you look at BE Semiconductor Industries through its P/E multiple. The shares trade on 67.6x earnings, compared with 51.9x for the European semiconductor group, 47.1x for peers, and a fair ratio of 52.5x that the market could move toward.
This richer valuation leaves less room for disappointment if growth expectations ease. The open question for investors is whether the current premium feels like a buffer or a bruise waiting to happen.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk can be confusing, so consider reviewing BE Semiconductor Industries against your own checklist and weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BE Semiconductor Industries?
If BE Semiconductor Industries has your attention, do not stop here. Broaden your watchlist with filters that spotlight different strengths so you are not missing opportunities elsewhere.
- Target lower-priced opportunities with robust fundamentals by scanning a focused set of 121 elite penny stocks with strong financials that still clear basic quality hurdles.
- Hunt for potential value by reviewing a curated mix of 188 high quality undervalued stocks that blend stronger balance sheets with healthier cash flows.
- Prioritise resilience by zeroing in on a 223 resilient stocks with low risk scores that screens for companies with steadier risk profiles and fewer financial red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com