
ChemoMetec (CPSE:CHEMM) Just Moved, So What Is Behind The Attention?
ChemoMetec (CPSE:CHEMM) just raised its earnings outlook for the 2026/27 financial year, guiding revenue to DKK 560 million to DKK 590 million. That updated range replaces earlier expectations of DKK 545 million to DKK 575 million.
The raised guidance comes after a busy stretch for ChemoMetec, with a share buyback program, a decision not to pay a dividend for 2025/26, and a new auditor appointed at the recent AGM. All of these developments feed into how investors gauge risk and capital allocation.
The share price has climbed 20.3% over the past month and 37.2% over the last 90 days, yet remains down 13.9% year to date. The 3-year total shareholder return of 102% contrasts with a 33.5% decline over five years, highlighting the difference between recent performance and the longer-term picture.
Spot fresh momentum stories like ChemoMetec’s guidance upgrade by scanning our hand picked 615 high quality undiscovered gems that currently sit off most investors' radar.ChemoMetec’s guidance lift and sharp rebound set up a simple tension. Is this the early stage of a reset, or has most of the easy upside already been priced in ahead of valuation work?
Most Popular Narrative: 9% Undervalued
ChemoMetec’s most followed narrative pegs fair value at DKK 638, which sits above the latest close at DKK 581. That gap reflects a view that current pricing does not fully capture the earnings power analysts expect over the next several years.
Investment of around DKK 120 million in product development for fiscal 2026 to 2027, focused on automation, sample management and XM Octopus fleet management software, can build higher value system and software revenue streams that may support EBITDA margins over time.
See why 1 investors see ChemoMetec as 9% undervalued.
Result: Fair Value of DKK 638.33 (UNDERVALUED)
Still, the story can break if ChemoMetec’s heavy spending on automation fails to gain traction, or if early stage biotech funding weakens again.
Find out about the key risks to this ChemoMetec narrative.
Another View On ChemoMetec’s Valuation
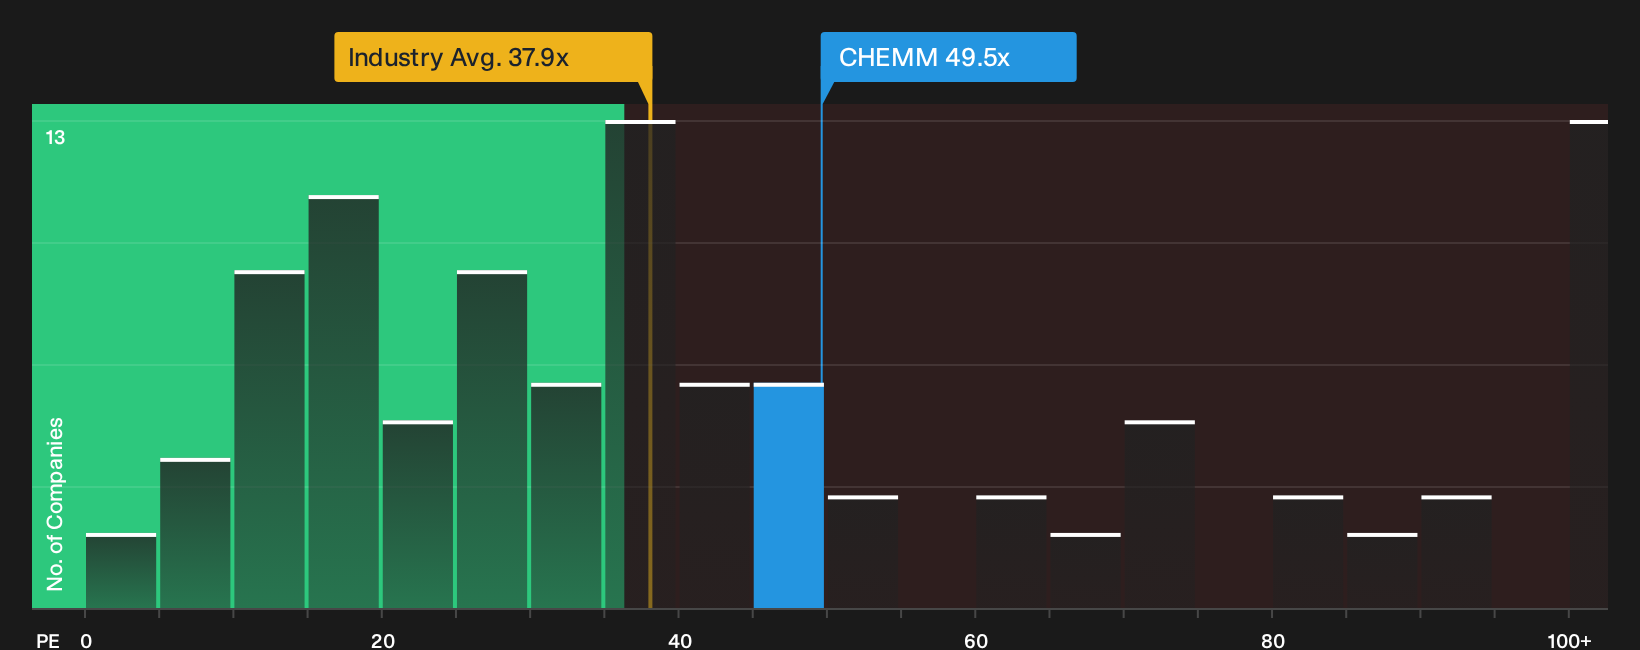
Analysts frame ChemoMetec as about 9% below their DKK 638 fair value, yet the current P/E of 49.5x tells a tougher story. That multiple sits well above the global Life Sciences average at 37.9x and an estimated fair ratio of 19.9x, which points to meaningful valuation risk if sentiment cools.
If you want to see how that premium stacks up in detail, take a closer look at the valuation breakdown using our earnings multiple workup See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on ChemoMetec so far. With both risks and potential rewards on the table, move quickly and weigh the full picture through 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond ChemoMetec?
Do not stop at a single stock when the wider market may hold better fits for your goals and risk comfort.
- Target potential mispricing by scanning the 188 high quality undervalued stocks that combine solid fundamentals with prices that some investors may be overlooking.
- Prioritise resilience first and see which companies pass the quality filter in our list of solid balance sheet and fundamentals (203 results).
- Secure-focused investors can hunt for reliable cash payouts inside the 216 dividend fortresses before yield opportunities slip away.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com