
Patient Specific Spine Implants Could Be A Game Changer For Globus Medical Stock (GMED)
- Globus Medical recently showcased its SCRIPT patient-specific spinal implant platform and XLIF Prone Procedural Solution at the 41st Annual NASS Meeting, highlighting FDA-cleared technology that connects preoperative planning with navigated surgical workflows.
- The move into tailored spine implants and prone lateral workflow tools points to Globus Medical prioritising integrated, software-linked procedures that can deepen surgeon adoption across its broader Excelsius ecosystem.
- The next area of attention will be how Globus Medical's SCRIPT patient-specific platform could reshape the broader investment narrative around its digital spine ecosystem.
Globus Medical Investment Narrative Recap
To own Globus Medical, you need to be comfortable with a story built around integrated spine and neuromodulation workflows, powered by robotics, software and implants. The near term swing factor is still execution on margin and synergy goals, while keeping procedure volumes healthy across spine, trauma, international and Nevro.
The biggest near term risk is that Enabling Technologies and Nevro stay choppy, which could dilute earnings quality even if SCRIPT and other tools get traction. This NASS news looks directionally helpful for the digital spine narrative, but by itself it does not fundamentally change the key near term catalyst or the central risk.
The SCRIPT patient specific implant platform preview sits closest to the current thesis. It plugs into ExcelsiusGPS and ExcelsiusHub, which matters because analysts already frame the story around getting more value from each installed robot through software and implant pull through, rather than just upfront hardware sales.
For you as a shareholder, SCRIPT is another test of how effectively Globus Medical can link planning software, navigation and implants into one workflow. Strong execution here could support the existing catalysts around margins and ecosystem monetisation. Execution missteps, by contrast, would add to concerns already present around Enabling Technologies volatility.
What The Current Globus Medical Forecasts Assume
Globus Medical's narrative projects US$3.7b revenue and US$767.4m earnings by 2029. That lines up with analysts baking in 5.8% yearly revenue growth and an earnings increase of about US$232m from US$535.4m today.
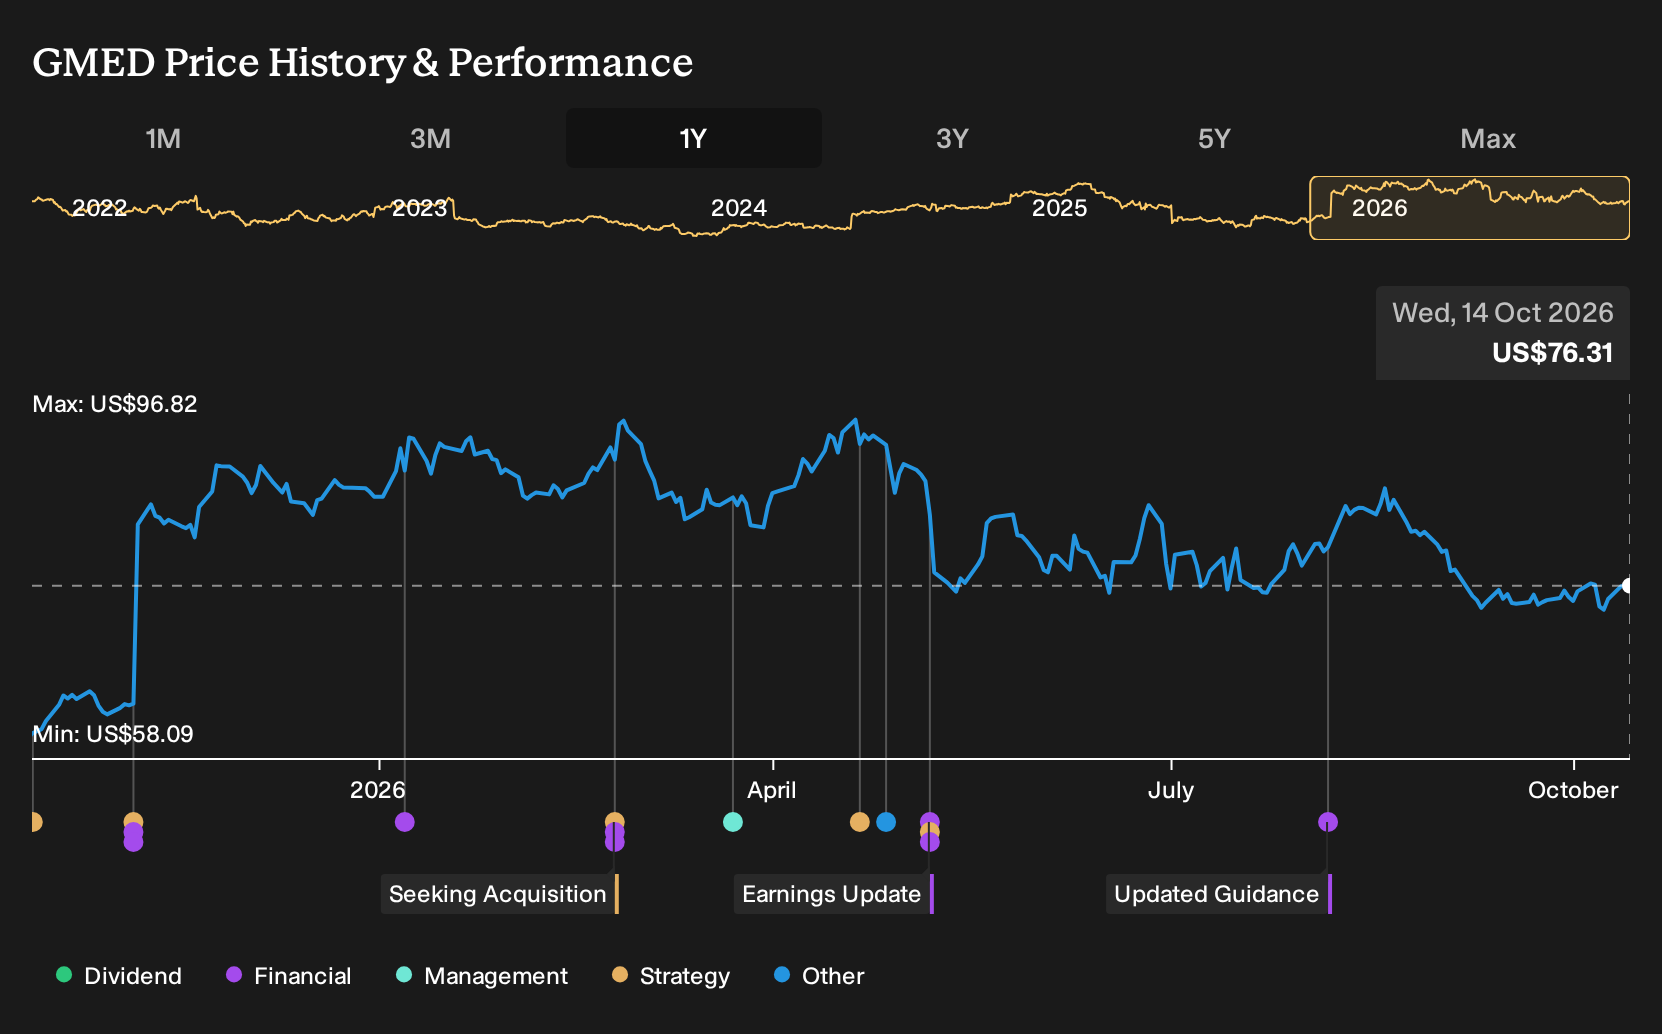
Uncover why Globus Medical's fair value indicates a 32% potential upside to its current price, which could narrow quickly if sentiment around Globus Medical shifts.
Exploring Other Perspectives
One alternate angle around Globus Medical focuses on the risk that the expanded Excelsius and SCRIPT style ecosystem might not convert into as much implant and software usage as hoped. The most cautious analysts were only modelling about US$3.7b of revenue and US$711.4m of earnings by 2029. That is a materially stricter view than consensus and it came before this NASS news. This gives you a useful reference point as you weigh how opinions might shift from here.
Explore 5 other Globus Medical fair value estimates, including one that suggests it could be worth just $84.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Globus Medical research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Globus Medical. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Globus Medical's overall financial health at a glance.
Looking For More Investment Ideas Beyond Globus Medical?
Once you have formed a view on Globus Medical, it can be useful to line it up against other companies with very different risk and return profiles. The Simply Wall St Screener helps you quickly sort through the market so you are not relying on a single story or sector.
- If capital preservation sits high on your list, consider starting with a basket of 32 resilient stocks with low risk scores that score well on stability and downside resilience.
- For readers who want quality at a reasonable entry point, you can filter for 32 high quality undervalued stocks that pair stronger fundamentals with prices that analysts see as below intrinsic value.
- Those hunting for steady income streams can refine their search to 7 dividend fortresses that combine higher yields with a focus on sustainability and balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com