
3 Stocks To Watch as Investors Shift Back to Cash Yield
With tech hardware and chip stocks under pressure, cash suddenly looks interesting again. Investors worried about AI funding stress and higher Fed rates are hunting for yield that does not swing as wildly as growth shares. This article explores three stocks from our Global Cash and Money-Market Solutions Providers screener that appear closely tied to this shift toward liquidity and capital preservation, and shows how their business models intersect with today’s market reset.
The stocks highlighted below are only a small sample of what this cash focused theme picks up, with the full screen surfacing 24 more companies whose business stories around liquidity and yield are not covered here. To see the broader field and identify which cash and money-market specialists best fit your own risk and income preferences, head into the Global Cash and Money-Market Solutions Providers screener.
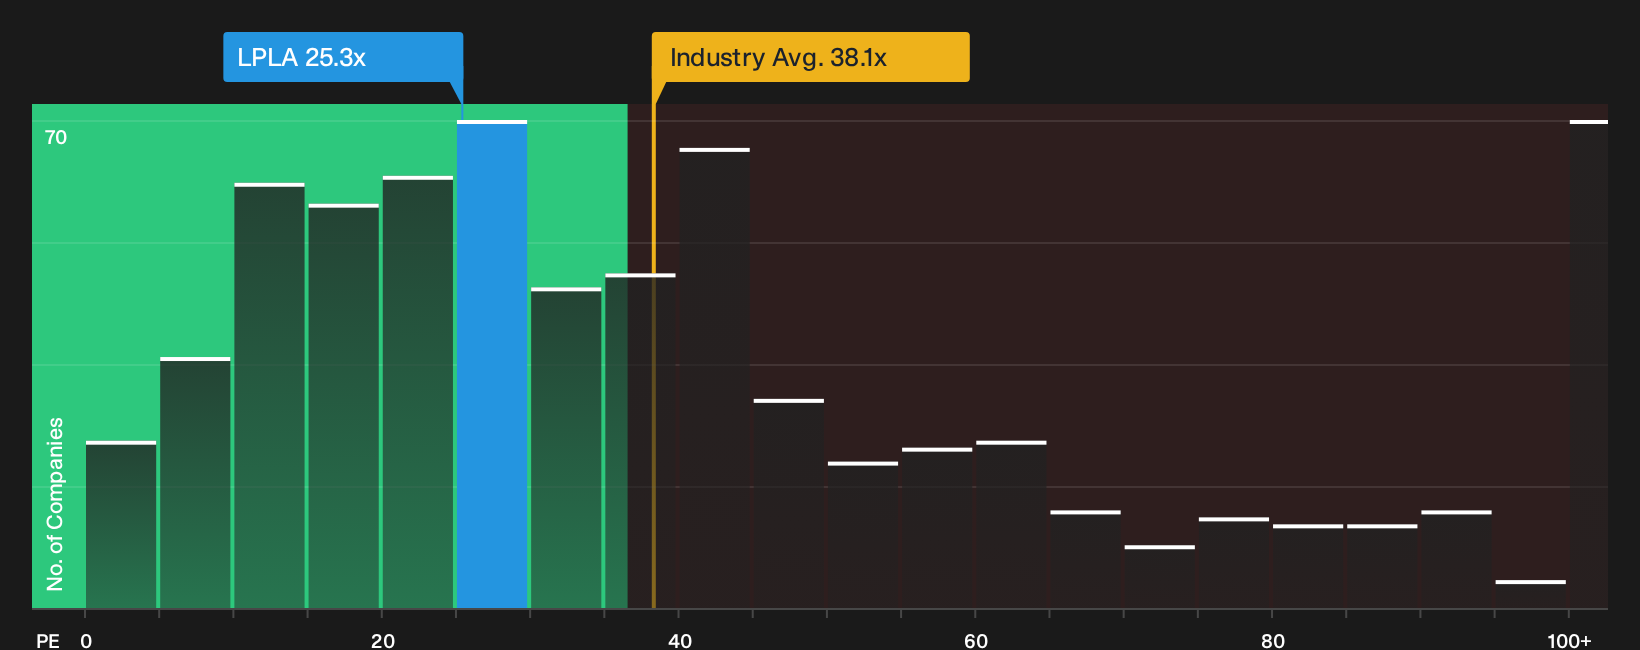
LPL Financial Holdings (LPLA)
Overview: LPL Financial Holdings runs a large US brokerage and advisory platform where independent advisors route client assets, including cash, into sweep and money-market solutions tied directly to today’s hunt for higher-yielding liquidity.
Operations: LPL Financial generates about US$19.2b of brokerage revenue entirely from US clients, reflecting a business concentrated in domestic advisory and trading activity.
Market Cap: US$25.6b
For investors watching how cash moves when markets turn rough, LPL Financial Holdings is important because advisor decisions on where client money parks often pass through its sweep and money-market channels.
"The continued expansion of LPL Financial Holdings advisor base, supported by ongoing recruiting of advisers in motion and new institutional relationships, can add fee and commission revenue as additional client assets come onto the platform."
What happens to interest sensitive cash sweep income if one unseen pressure on pricing and yields starts to bite harder will matter a lot.
If that pressure point on cash sweep economics is what you are really watching, the full narrative for LPL Financial Holdings shows how LPL Financial Holdings could absorb or benefit from shifting yields.
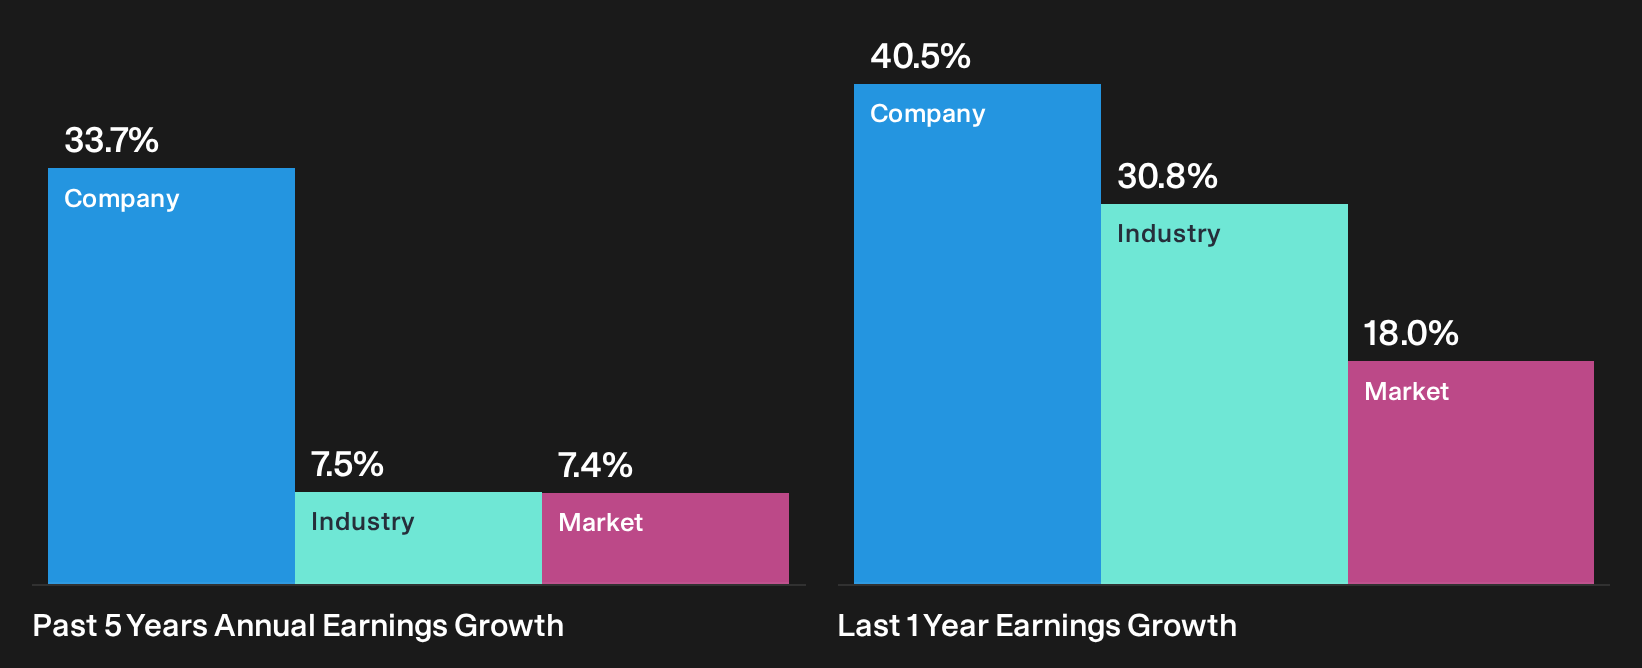
Futu Holdings (FUTU)
Overview: Futu Holdings runs the Futubull and moomoo platforms, where investors trade securities and channel idle balances into cash focused wealth products.
Operations: Futu Holdings currently generates about HK$24.1b in revenue from online brokerage and margin financing services, its sole reported business segment.
Market Cap: US$16.0b
Futu Holdings catches attention in this cash and money market theme because its digital platforms sit where retail traders decide whether to leave money in volatile trades or shift into yield bearing, near cash products during risk off moments.
"The rapid growth in funded accounts remains a live driver, with total funded accounts reaching about 3.84 million in Q2 2026 and overseas markets contributing nearly 60% of these. This can support future revenue and fee income growth from a larger, more diversified client base."
What happens to client appetite for those lower volatility, income oriented options if one unresolved regulatory and funding constraint tightens will be crucial.
That pressure point is exactly where the full narrative for Futu Holdings shows whether funding growth is accelerating or regulatory risks are quietly masking the real earnings engine.
State Street (STT)
Overview: State Street is a global custodian and asset manager that runs large scale cash, money-market, and short duration investment solutions for institutional investors.
Market Cap: US$47.8b
State Street matters for this cash and money-market theme because its institutional clients tend to move sizeable pools of assets into short term liquidity vehicles when risk appetite cools and yields on safer options become more attractive.
"The integrated One State Street approach that links its custody, asset management, FX, securities lending, and co branded ETF and tokenized servicing mandates together is gaining traction with institutional and wealth clients. This can deepen relationships and support fee revenue and pretax margin resilience even as ETF fee pressure remains a headwind."
This raises the question of what happens when a subtle shift in how clients allocate between ultra short cash products and higher fee ETF strategies starts to reshape those margins.
That margin puzzle is exactly where the full narrative for State Street shows how State Street could turn shifting client cash habits into accelerating fee power and overlooked resilience.

Seeking Alternatives Before Momentum Flies
Fresh opportunities rarely stay quiet for long. Once momentum builds, prices move and the easy entry points shrink. Scan these ideas while they are still under the radar for now and consider them before conditions change.
- Spot stronger balance sheets before the crowd moves by running the list of solid balance sheet and fundamentals (25 results) and lining up candidates while pricing still reflects caution instead of confidence.
- Target resilient cash generators by reviewing the 32 high quality undervalued stocks and filtering for businesses where quality and valuation still look out of sync with recent momentum.
- Track high yield opportunities early by scanning the 7 dividend fortresses and shortlisting payers that currently combine elevated income with disciplined fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com