
Global Growth Companies With High Insider Ownership Growing Earnings Up To 68%
As global markets navigate volatility driven by Middle East tensions, fluctuating energy prices, and evolving interest rate policies, investors are increasingly focused on companies with robust insider ownership that can weather such uncertainties. In this context, growth companies with high insider stakes often signal confidence from those closest to the business and may be well-positioned to capitalize on market opportunities.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Fulin Precision (SZSE:300432) | 11.7% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's take a closer look at a couple of our picks from the screened companies.
Intsig Information (SHSE:688615)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Intsig Information Co., Ltd. focuses on researching and developing text recognition and commercial big data core technologies in China, with a market cap of CN¥16.19 billion.
Operations: The company's revenue segments include text recognition and commercial big data technologies in China.
Insider Ownership: 11.4%
Earnings Growth Forecast: 26.2% p.a.
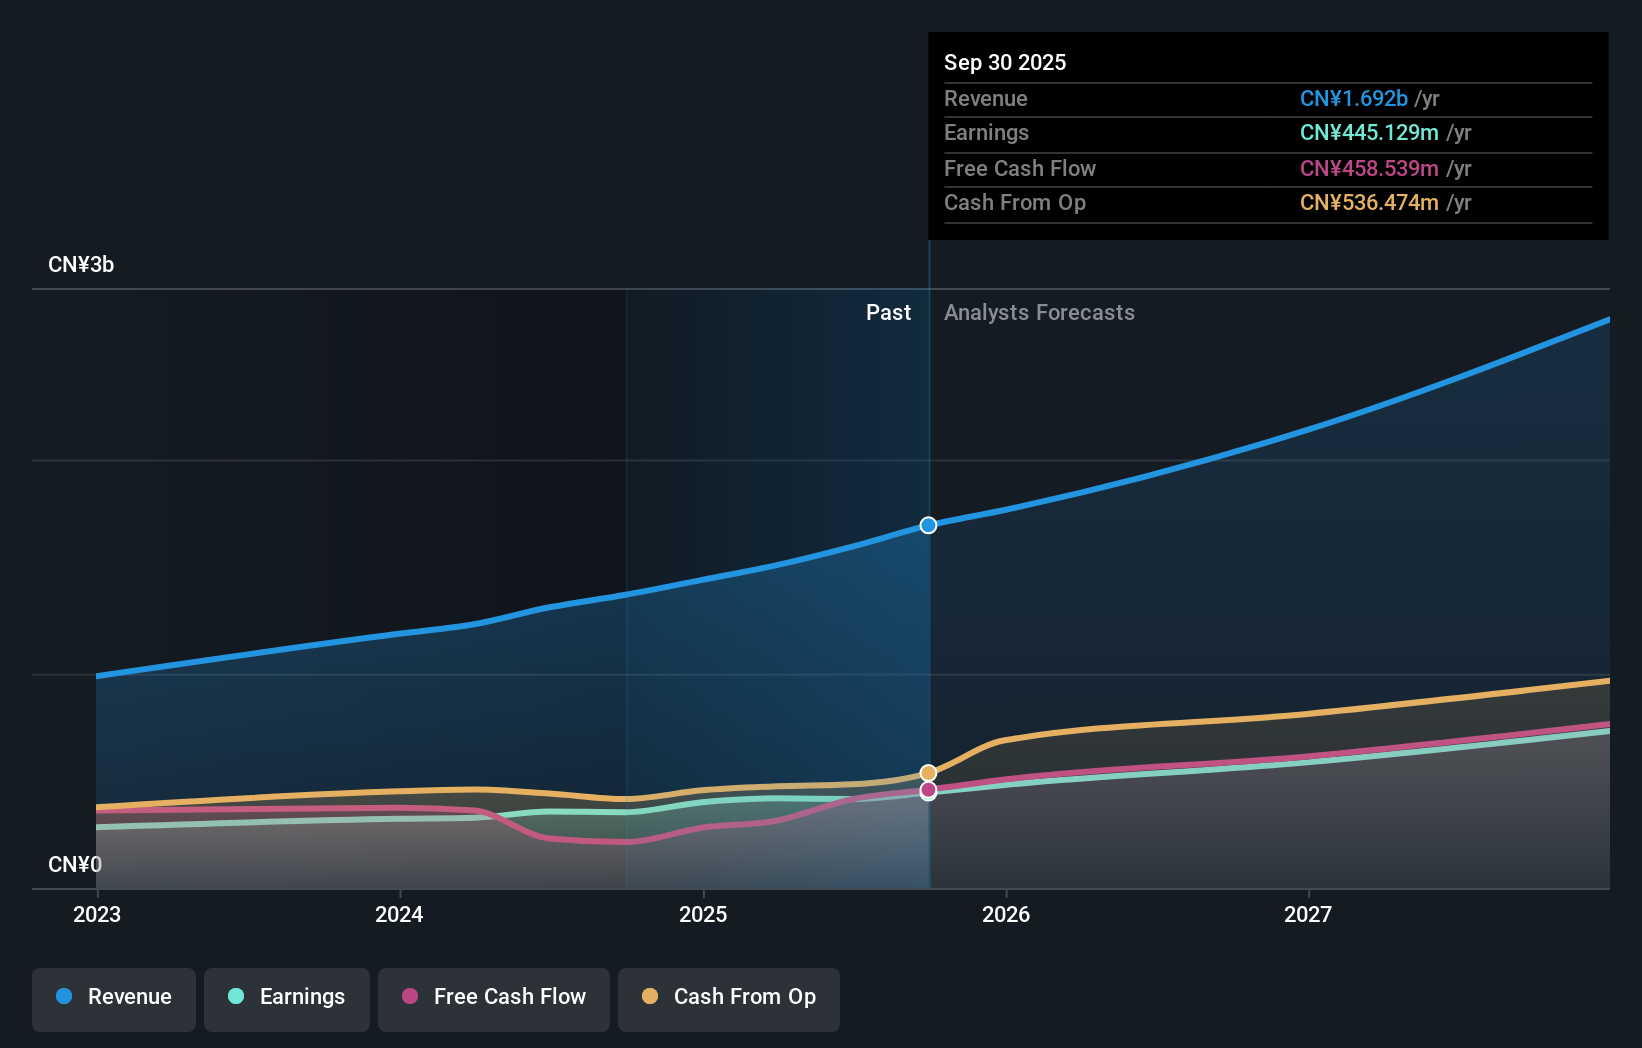
Intsig Information is experiencing robust growth, with revenue forecasted to increase by 21.5% annually, outpacing the Chinese market average of 16.5%. Recent earnings showed a rise in net income to CNY 246.71 million, and its P/E ratio of 34.1x suggests it is trading at a good value relative to peers. Despite high volatility in share price recently, the company's addition to the S&P Global BMI Index highlights its growing prominence.
- Click to explore a detailed breakdown of our findings in Intsig Information's earnings growth report.
- Our valuation report unveils the possibility Intsig Information's shares may be trading at a discount.
Japan Elevator Service HoldingsLtd (TSE:6544)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Japan Elevator Service Holdings Co., Ltd. specializes in the repair, maintenance, and modernization of elevators and escalators in Japan, with a market capitalization of ¥268.08 billion.
Operations: The company generates revenue primarily through its Maintenance Business, which accounted for ¥59.95 billion.
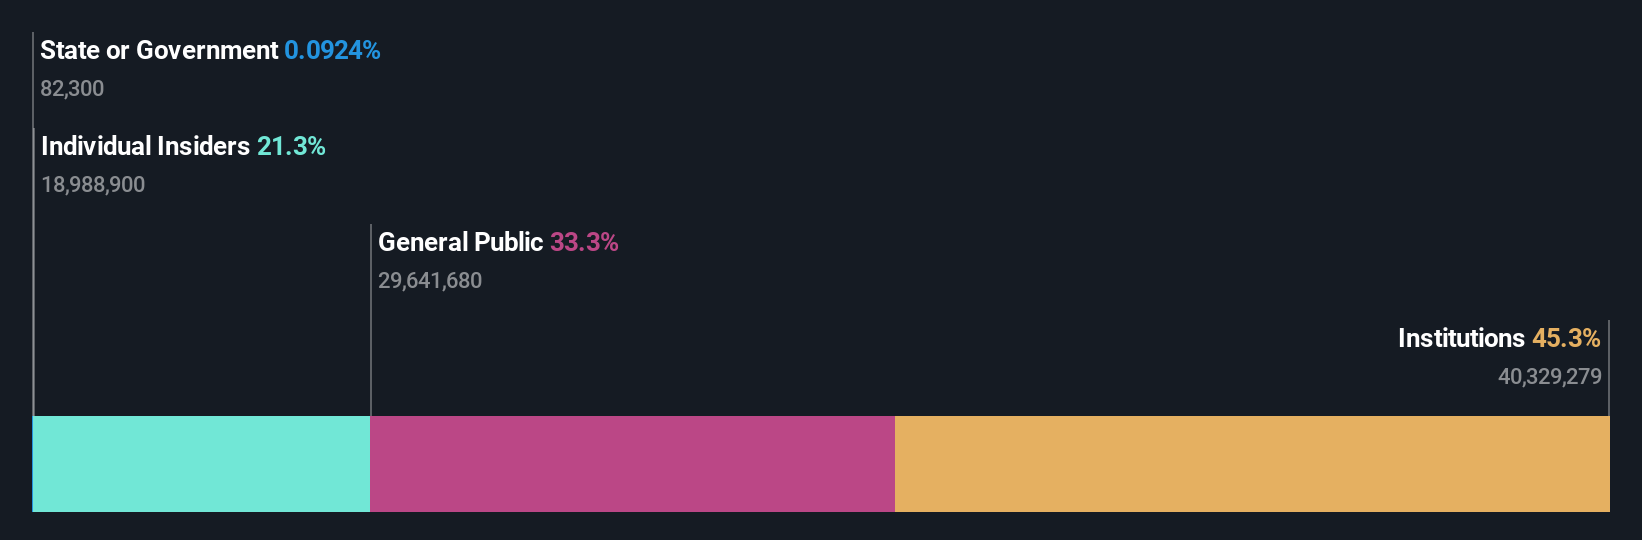
Insider Ownership: 20.3%
Earnings Growth Forecast: 16.1% p.a.
Japan Elevator Service Holdings Ltd. demonstrates steady growth with its revenue forecasted to rise 12.4% annually, surpassing the Japanese market's average of 6.7%. Recent earnings show a net income increase to ¥1.92 billion, reflecting strong performance. The stock is trading at 24.8% below estimated fair value, and analysts expect a potential price rise of 60.4%. Despite no recent insider buying or selling activity, the company maintains high insider ownership levels.
- Unlock comprehensive insights into our analysis of Japan Elevator Service HoldingsLtd stock in this growth report.
- Our valuation report here indicates Japan Elevator Service HoldingsLtd may be undervalued.
Taiwan Surface Mounting Technology (TWSE:6278)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Taiwan Surface Mounting Technology Corp. is involved in the design, processing, manufacturing, and trading of TFT-LCD panels, general electronic information products, and PCB surface mount packaging globally, with a market cap of NT$83.81 billion.
Operations: The company generates revenue primarily from its Electronic Components & Parts segment, amounting to NT$50.66 billion.
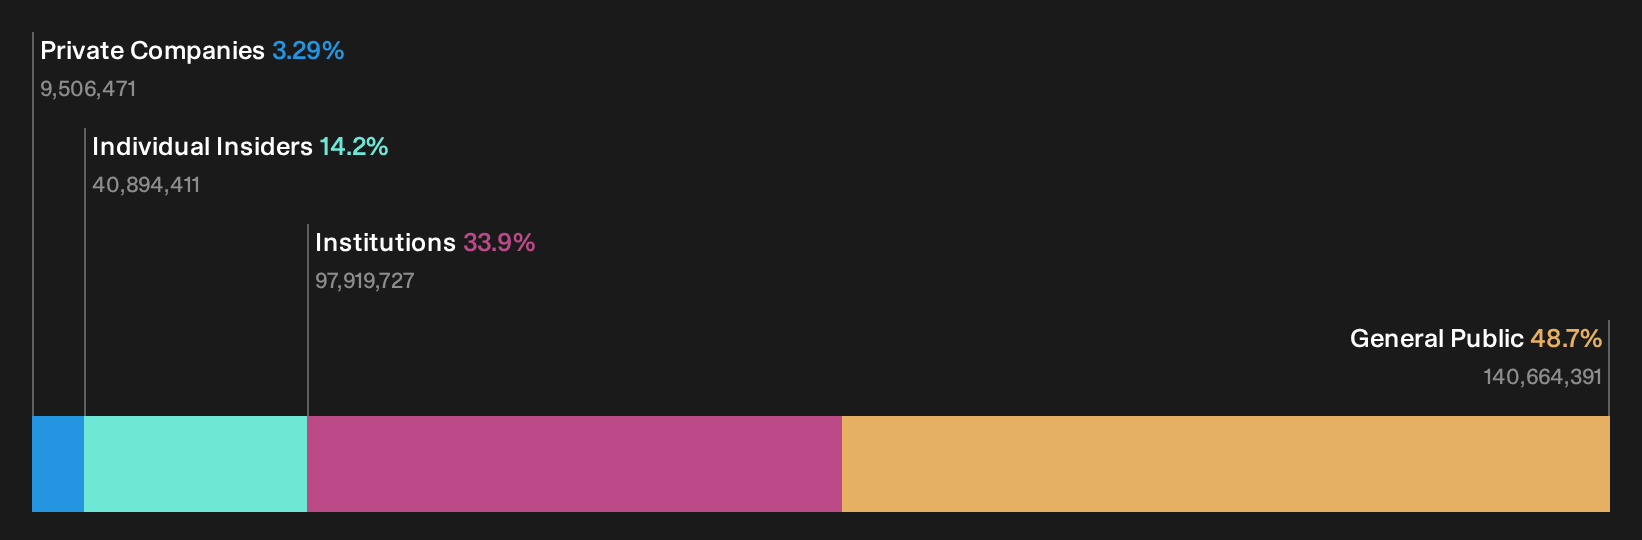
Insider Ownership: 14.2%
Earnings Growth Forecast: 68.7% p.a.
Taiwan Surface Mounting Technology Corp. is poised for robust growth, with earnings forecasted to increase significantly at 68.7% annually, outpacing the Taiwanese market's 25.9%. Recent results show strong financial performance, with Q2 net income rising to NT$799.74 million from NT$479.98 million year-over-year and sales climbing to NT$13.23 billion from NT$12.59 billion a year ago. Despite high insider ownership, no recent insider trading activity has been reported over the past three months.
- Delve into the full analysis future growth report here for a deeper understanding of Taiwan Surface Mounting Technology.
- Our expertly prepared valuation report Taiwan Surface Mounting Technology implies its share price may be too high.
Key Takeaways
- Investigate our full lineup of 718 Fast Growing Global Companies With High Insider Ownership right here.
- Ready For A Different Approach? Explore 25 top quantum computing companies leading the revolution in next-gen technology and shaping the future with breakthroughs in quantum algorithms, superconducting qubits, and cutting-edge research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com