
Global Stocks Estimated Below Intrinsic Value In October 2026
In October 2026, global markets are navigating a landscape marked by volatility due to fluctuating oil prices and geopolitical tensions in the Middle East, alongside mixed performances across major indices. Amid these conditions, investors are increasingly focused on identifying undervalued stocks that may offer potential opportunities for growth. A good stock in this environment is often characterized by strong fundamentals and resilience against market fluctuations, making them attractive candidates for those seeking value investments.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| XTC New Energy Materials(Xiamen)Ltd (SHSE:688778) | CN¥38.70 | CN¥75.63 | 48.8% |
| Valmet Oyj (HLSE:VALMT) | €27.24 | €53.41 | 49% |
| PORR (WBAG:POS) | €30.95 | €60.75 | 49% |
| Orthex Oyj (HLSE:ORTHEX) | €4.50 | €8.89 | 49.4% |
| Marco Polo Marine (SGX:5LY) | SGD0.119 | SGD0.23 | 48.9% |
| Lindab International (OM:LIAB) | SEK127.30 | SEK251.22 | 49.3% |
| ING Groep (ENXTAM:INGA) | €30.08 | €59.70 | 49.6% |
| Industrias Peñoles. de (BMV:PE&OLES *) | MX$869.48 | MX$1735.30 | 49.9% |
| Ichikoh Industries (TSE:7244) | ¥538.00 | ¥1058.34 | 49.2% |
| ALEC Holdings PJSC (DFM:ALEC) | AED1.27 | AED2.54 | 49.9% |
Let's review some notable picks from our screened stocks.
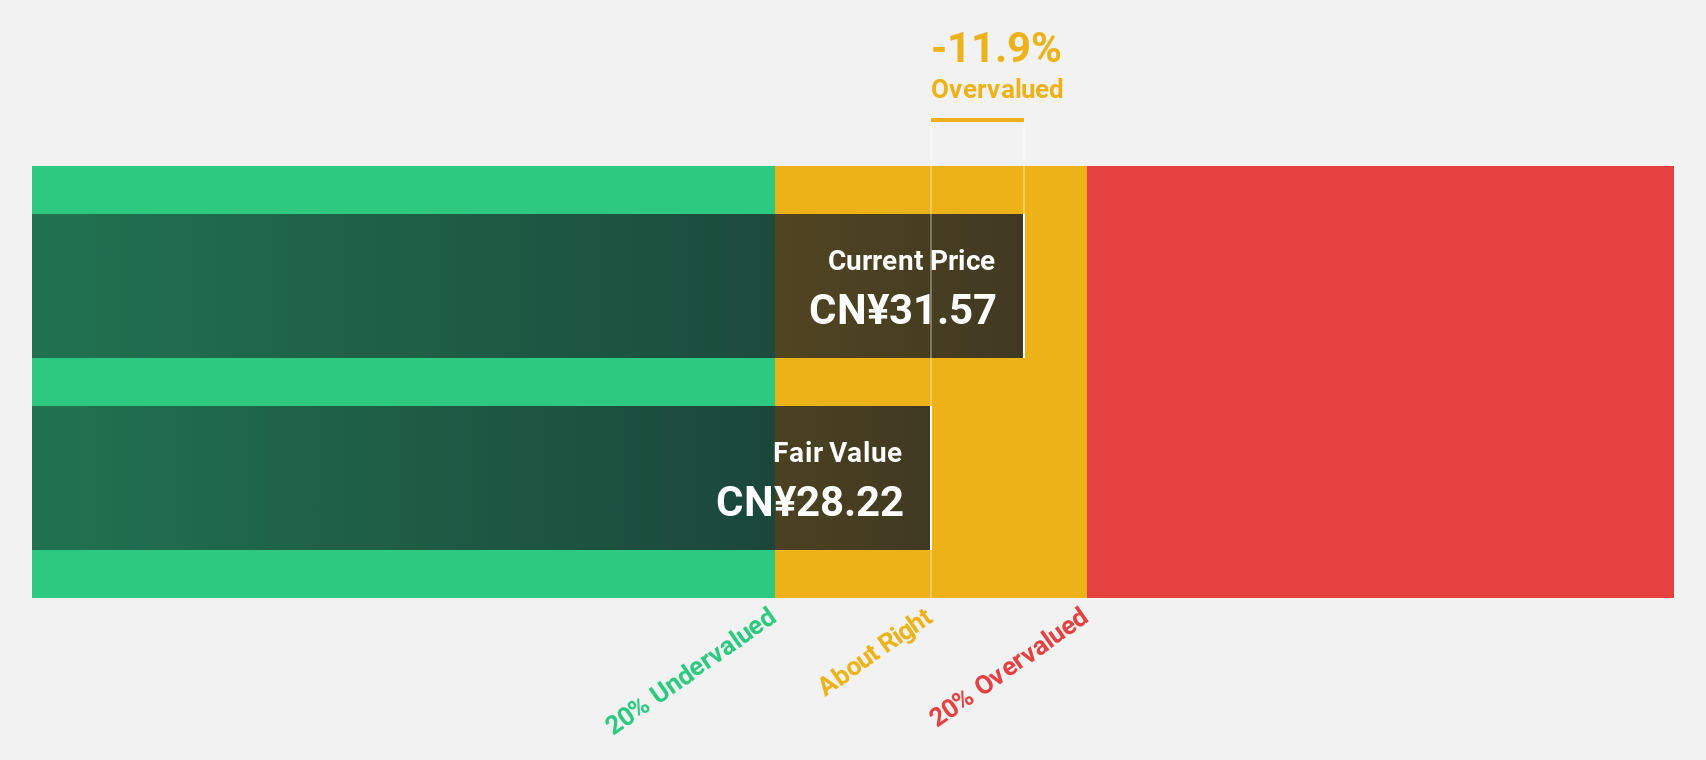
Hangzhou EZVIZ Network (SHSE:688475)
Overview: Hangzhou EZVIZ Network Co., Ltd. manufactures and sells smart home products both in China and internationally, with a market cap of CN¥21.92 billion.
Operations: The company's revenue segments include Smart Home Access at CN¥1.06 billion, Smart Home Camera at CN¥3.21 billion, Accessories Products at CN¥316.15 million, Intelligent Service Robot at CN¥96.06 million, and Internet of Things Cloud Platform at CN¥1.29 billion.
Estimated Discount To Fair Value: 33.1%
Hangzhou EZVIZ Network is trading at CN¥27, significantly below its estimated future cash flow value of CN¥40.36, indicating it may be undervalued. Despite a forecasted earnings growth of 19.52% per year, this is slower than the Chinese market average. Recent product innovations in smart home technology highlight the company's commitment to growth and innovation, potentially enhancing long-term cash flows and supporting its valuation prospects.
- According our earnings growth report, there's an indication that Hangzhou EZVIZ Network might be ready to expand.
- Click here and access our complete balance sheet health report to understand the dynamics of Hangzhou EZVIZ Network.
Nissui (TSE:1332)
Overview: Nissui Corporation operates in marine, food products, fine chemicals, general distribution, and other businesses across Japan and internationally with a market cap of ¥327.56 billion.
Operations: The company's revenue segments include Marine Products at ¥416.17 billion, Food Products at ¥513.91 billion, Fine Chemicals at ¥18.18 billion, and General Distribution at ¥31.21 billion.
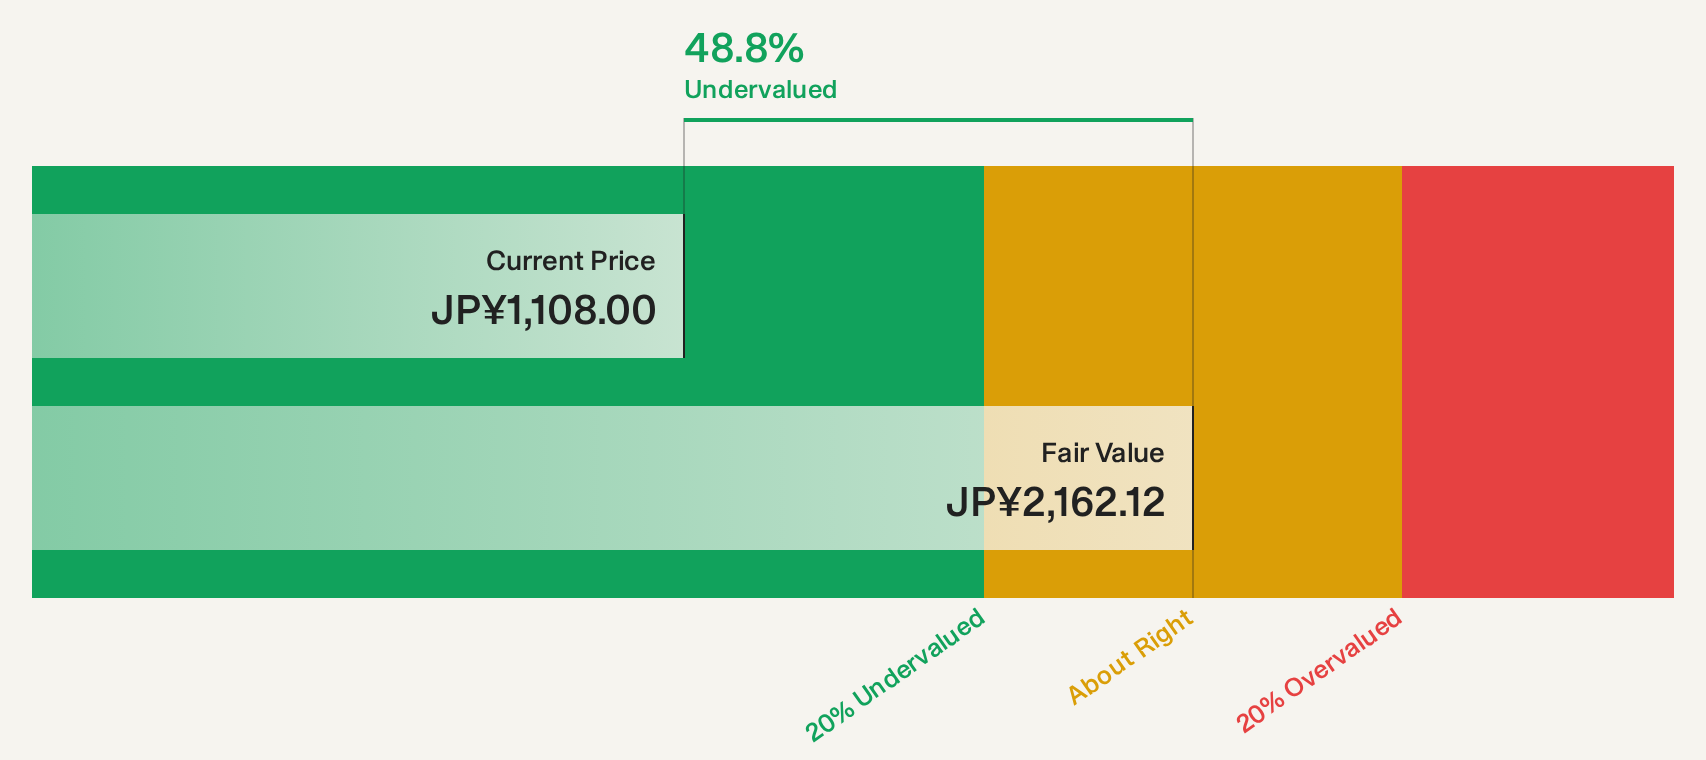
Estimated Discount To Fair Value: 48.6%
Nissui is trading at ¥1,102.5, significantly below its estimated future cash flow value of ¥2,144.21, highlighting potential undervaluation. Earnings grew 16% over the past year and are forecast to grow 7.29% annually, though slower than the Japanese market average of 9.6%. Recent earnings showed increased sales and net income compared to last year; however, dividends have been reduced for the full fiscal year ending March 2027 due to financial constraints.
- Our growth report here indicates Nissui may be poised for an improving outlook.
- Unlock comprehensive insights into our analysis of Nissui stock in this financial health report.
Tachibana Eletech (TSE:8159)
Overview: Tachibana Eletech Co., Ltd. is a technology-driven trading company operating in Japan and internationally, with a market capitalization of ¥104.83 billion.
Operations: Tachibana Eletech Co., Ltd. generates its revenue through various technology-driven trading activities both domestically and internationally.
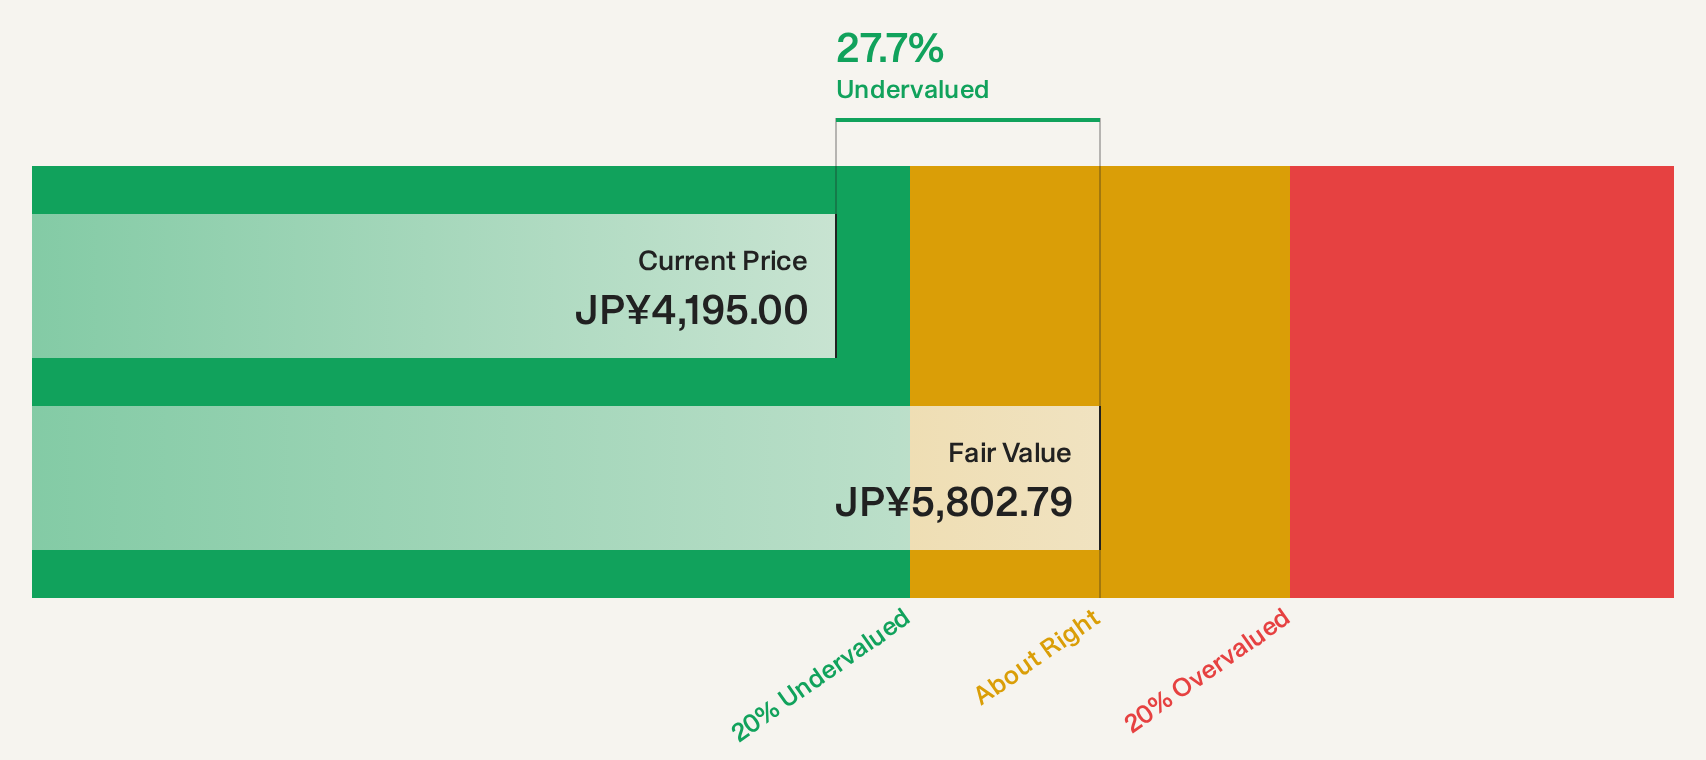
Estimated Discount To Fair Value: 22.2%
Tachibana Eletech is trading at ¥4,620, over 20% below its estimated future cash flow value of ¥5,940.01, suggesting undervaluation. The company revised its earnings guidance upwards due to strong performance in Factory Automation Systems and Semiconductors & Electronic Devices. First-quarter sales increased to ¥57.75 billion from the previous year’s ¥48.16 billion, with net income rising significantly. However, earnings growth is forecasted at a modest 1.87% annually, slower than the market average.
- Our comprehensive growth report raises the possibility that Tachibana Eletech is poised for substantial financial growth.
- Click here to discover the nuances of Tachibana Eletech with our detailed financial health report.
Summing It All Up
- Get an in-depth perspective on all 260 Undervalued Global Stocks Based On Cash Flows by using our screener here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com