
Is Seagate Technology Holdings (STX) Priced Right for Its Earnings Power?
Seagate Technology Holdings has been on a remarkable multi year run, yet the stock has pulled back sharply in recent weeks, which puts a fresh spotlight on whether its current price is still supported by the earnings behind it. With sentiment swinging on both competitive headlines and AI storage expectations, the key issue is how much profit power investors are implicitly paying for today.
- Over the past three years, Seagate shares have delivered a gain of more than 10x, so any reassessment of its earnings power can have an outsized effect on what looks reasonable for the valuation.
- Toshiba's plan to almost double hard disk drive capacity for AI data centers by fiscal 2027 may pressure pricing and margins for Seagate, which could influence how durable the stock's current earnings profile appears.
- There is a second opinion on Seagate Technology Holdings worth weighing. See what analysts think Seagate Technology Holdings's shares could be worth.
The stock's next move may depend on whether Seagate's current earnings are strong and resilient enough to justify the price investors are paying after such a sharp multi year climb and recent pullback.
If this Seagate Technology Holdings pullback has you rethinking how much earnings strength you are paying for in AI storage, a focused screen of other 92 AI infrastructure stocks.
Is Seagate Technology Holdings Still Cheap on Earnings?
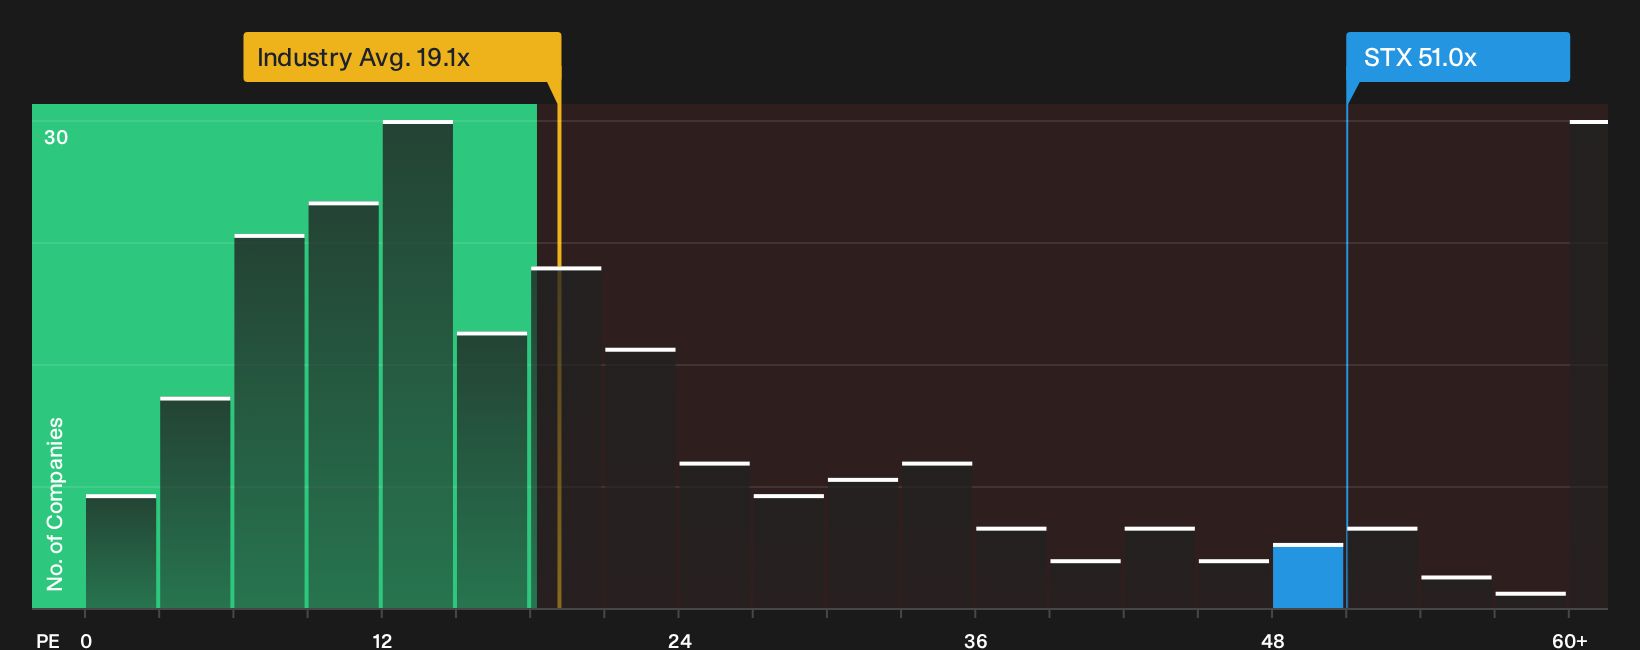
The P/E ratio fits Seagate Technology Holdings well because profit is still the main yardstick investors watch for established hardware producers. Seagate trades on a P/E of 51.0x, compared with roughly 23.1x for peers and 19.1x for the wider Tech industry, so you are paying a much higher price per dollar of earnings than in the broader group.
The fair value framework, which blends Seagate’s growth profile, margins, size and risk into a tailored reference multiple, suggests the current 51.0x P/E sits below where the model would normally place the stock. Despite Toshiba’s planned hard drive capacity expansion putting pressure on sentiment, the market is still pricing Seagate at a discount to that customised benchmark. This leaves the burden on you to weigh how durable those earnings look against rising AI storage competition. Explore the numbers behind Seagate Technology Holdings's P/E valuation.
The Seagate Technology Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Seagate Technology Holdings' stock pick up where the valuation puzzle leaves off and spell out which future paths for growth, margins and earnings would need to play out for the share price to look meaningfully higher or lower than it does today. Rather than lean on a single P/E or model output, each narrative sets out the assumptions sitting behind its fair value view so you can track those against the actual results as they arrive.
Community views on Seagate Technology Holdings split between those who see extra upside in the storage story and those who think expectations already look full.
Bull case: 38% undervalued
"Nearline hard drives are different, they are the only economically viable way to store data at hyperscale, the cost-per-terabyte gap versus flash is widening rather than narrowing..."
Discover why this Narrative puts Seagate Technology Holdings at 38% undervalued.
Bear case: roughly fairly valued
"The biggest risk is industry oversupply, Toshiba has reportedly discussed expanding hard-drive capacity for AI demand, which could pressure pricing and margins..."
Explore why this Narrative puts Seagate Technology Holdings at roughly fairly valued.
The Seagate Technology Holdings share price is only one piece of the decision
Before you weigh Seagate Technology Holdings purely on its earnings multiple and AI storage story, it is worth checking the broader health checks and specific risk flags our research has picked up. Take a closer look at 3 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com