
Is Five Below (FIVE) Undervalued After Extending Its Credit Facility And Raising Earnings Expectations?
Five Below (FIVE) extended its credit agreement on October 14, 2026, pushing the maturity to 2031 and doubling its senior secured revolving credit facility to $450,000,000, with a larger letter of credit subline.
The extended credit line lands at a time when Five Below’s recent price action has been choppy. The stock’s 1‑month share price return is down 12.28%, yet it still shows a 13.18% year to date share price gain and a 43.50% 1‑year total shareholder return. This points to longer term momentum building even as investors reassess near term growth expectations and risk after a fast run up.
Scan how Five Below stacks up against other fast moving retailers by checking the hand picked 20 high quality undiscovered gems that share strong fundamentals and fresh earnings momentum signals.
The question now is whether Five Below’s recent pullback reflects a reset in sentiment after strong gains, or a deeper shift in how the market views the underlying business and its earnings profile.
Most Popular Narrative: 29.5% Undervalued
On the most followed view, Five Below’s fair value sits at $310.48 against a last close of $218.95. This puts the extended credit line in the context of a retailer modeled for higher long run earnings power under an 8.55% discount rate.
The main thing that has to go right is that Five Below continues to convert its store expansion runway, higher price point mix, and new store experience investments into healthy traffic, strong new store productivity, and resilient customer value perception despite rising cost and legal pressures.
See why 15 investors see Five Below as 29% undervalued.
Result: Fair Value of $310.48 (UNDERVALUED)
Still, higher fuel and trucking expenses, along with ongoing legal and regulatory actions, could pressure margins and weaken the upbeat Five Below earnings story investors are leaning on.
Find out about the key risks to this Five Below narrative.
Another View on Five Below’s Valuation
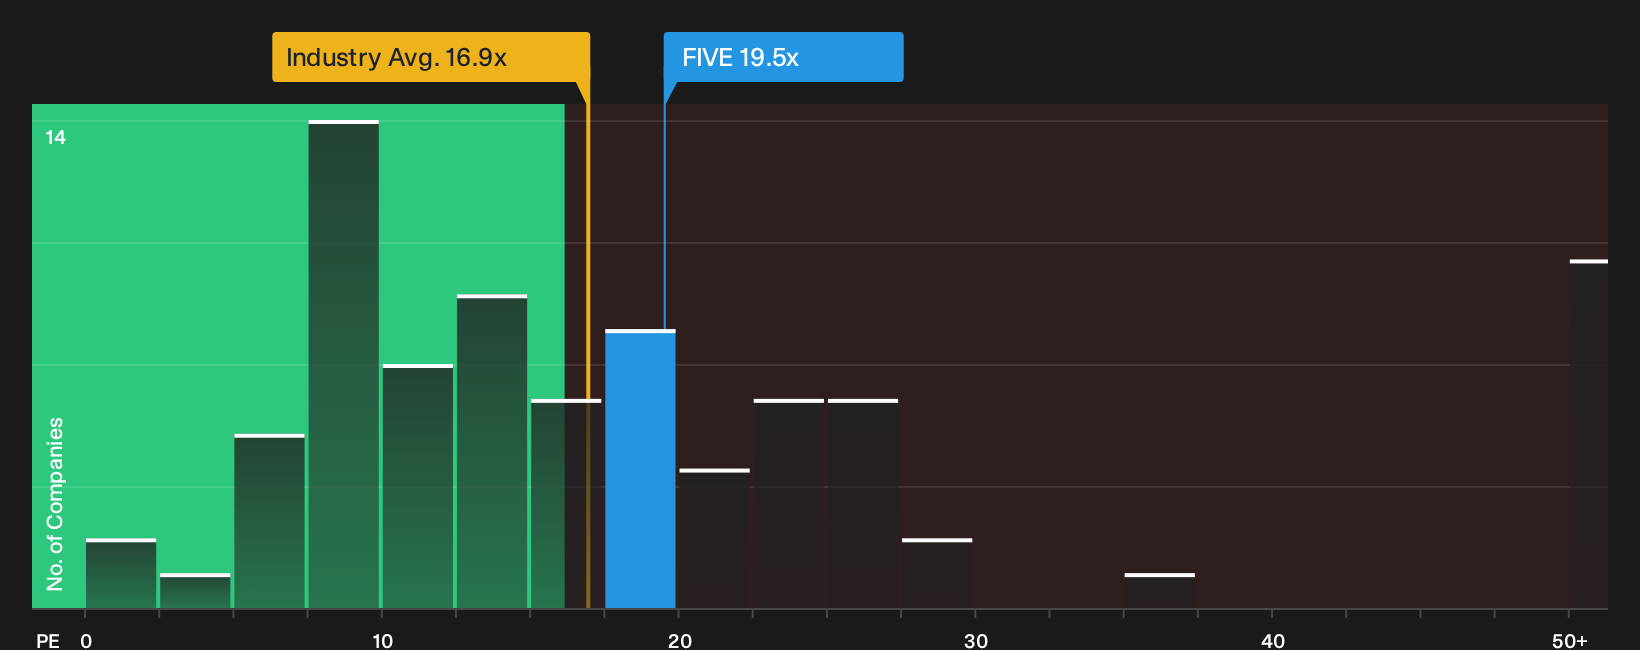
The community narrative frames Five Below as about 29.5% undervalued against a fair value of $310.48. A different lens tells a cooler story. On a P/E of 19.5x, the stock trades above the US Specialty Retail industry at 17x and above a fair ratio of 13.7x. This points to valuation risk if enthusiasm cools.
For a closer look at how that premium compares with peers and where the market could migrate over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you feel mixed about Five Below after all this, or are already leaning strongly one way, then pressure test that initial view against the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Five Below?
Do not stop with a single retailer when there are entire sets of potential opportunities one smart screen away.
- Hunt for mispriced quality and sort through the 32 high quality undervalued stocks that combine solid fundamentals with more modest expectations baked into their share prices.
- Strengthen your income watchlist by reviewing the 7 dividend fortresses that pair higher yields with balance sheets that support ongoing payouts.
- Dial down portfolio stress and focus on resilience by scanning the 32 resilient stocks with low risk scores that score well on financial health and volatility checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com