
Tesla’s Delivery Beat Isn’t Enough to Make TSLA Stock a Buy Ahead of Q3 Earnings
Tesla (TSLA) will release third-quarter financial results after the market closes on Wednesday, October 21. Ahead of the report, the electric vehicle maker posted better-than-expected delivery numbers, offering some relief to investors concerned about slowing EV demand and intensifying competition.
However, beating delivery estimates may not be enough to make Tesla an attractive buy. Despite the stronger-than-expected numbers, Tesla’s valuation warrants caution ahead of earnings.
Tesla Q3 Outlook
Tesla had stronger-than-expected vehicle deliveries in Q3, but its profitability remains a concern. The company delivered 486,532 vehicles during the quarter, comfortably beating analysts’ estimates of around 462,000.
Higher deliveries, growth in its services business, and improved performance in the energy generation and storage segment will likely drive Tesla’s Q3 revenue. However, lower average selling prices for its vehicles may continue to weigh on profit margins.
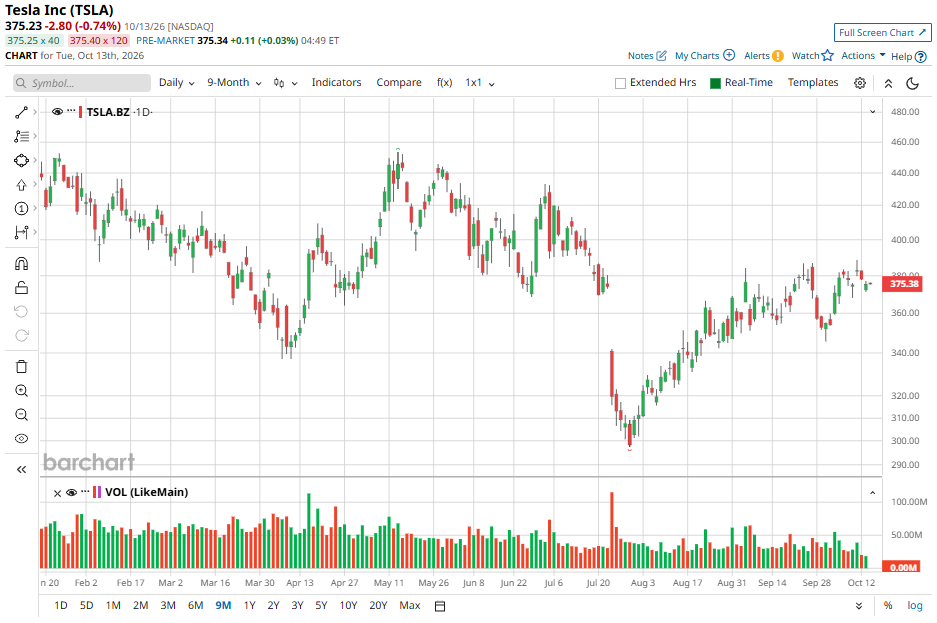
Tesla’s recent financial results highlight this challenge. In Q2, revenue grew 26% year over year, but profitability took a hit. Its adjusted EBITDA margin fell 353 basis points, while its operating margin dropped to 1.4%, down from 4.1% a year earlier and 4.2% in the previous quarter.
Another factor to watch is Tesla’s heavy spending on artificial intelligence (AI), autonomous driving, and other emerging technologies. The company is investing in projects such as Robotaxi and its Optimus humanoid robot, which could create new growth opportunities over time. However, these initiatives require substantial investment, and they may not contribute meaningfully to profits for years. Meanwhile, the spending could pressure earnings and free cash flow.
Wall Street analysts expect Tesla to report earnings of $0.21 per share, down more than 43% from the same period last year. The company has also missed analysts’ earnings estimates for four consecutive quarters.
Overall, Tesla’s stronger delivery numbers are encouraging, but margin pressure, higher capital expenditures, and a high valuation remain key concerns.
Tesla Stock’s Valuation Calls for Caution
Tesla’s profit margins remain under pressure, and its high valuation is another reason for investors to be cautious. TSLA stock is trading at around 521.9 times forward earnings, a steep premium compared with traditional automakers and major technology companies. At this level, Tesla stock has priced in a significant amount of future growth.
The challenge is that Tesla may need more than better vehicle sales to support its current share price. While the company is making progress in several areas, these efforts may take time to translate into higher profits.
In Q2, more customers used Tesla's Full Self-Driving (Supervised) technology and signed up for subscriptions. It also expanded its Robotaxi operations in the U.S. and began construction at its Fremont Factory to prepare for future Optimus robot production.
These developments could help Tesla build new revenue sources beyond electric vehicle sales. Its ambitions in autonomous driving, AI, and humanoid robotics could create significant long-term opportunities if the company can turn these projects into commercially successful businesses.
However, most of these initiatives are still early-stage, and their contribution to Tesla’s overall financial performance remains limited. It could take several years for them to meaningfully impact revenue and earnings, while development costs continue to weigh on margins.
Tesla may share further updates on these projects, which could influence how investors view its prospects. Still, until these initiatives begin generating meaningful profits, the stock’s high valuation remains a concern.
Tesla Stock Is Still Not a Buy
Tesla’s stronger-than-expected deliveries are encouraging, but declining margins, weaker earnings prospects, and substantial capital expenditures continue to pose risks. With the stock trading at a steep valuation, the market has already priced in much of its future growth. Until Tesla shows sustained profitability and meaningful returns from its emerging businesses, a cautious approach is warranted.
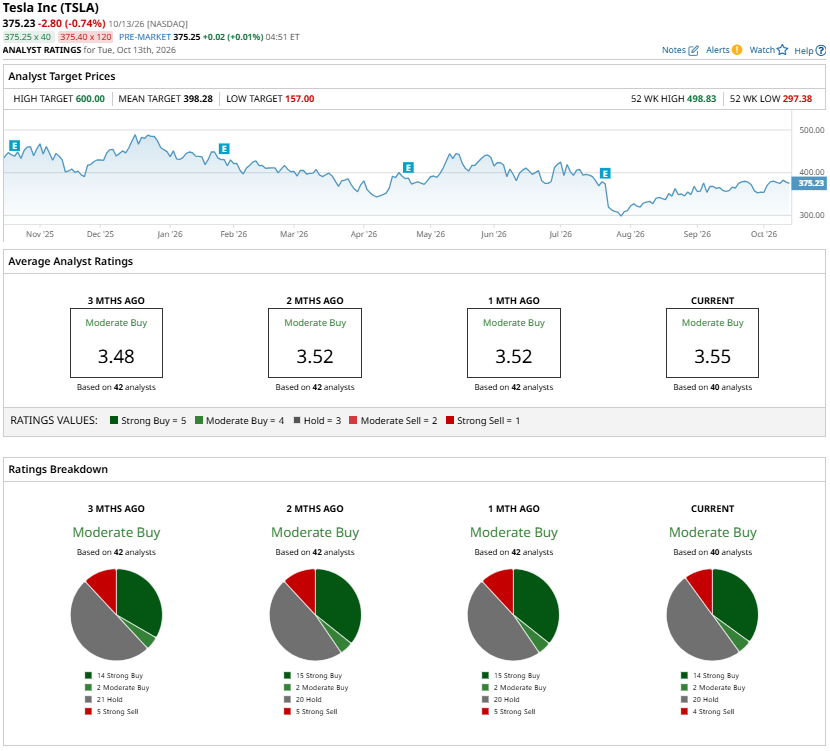
Most analysts covering Tesla stock are not recommending a Buy ahead of its third-quarter earnings report, reflecting near-term margin pressure and its high valuation.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.