
What Rexford Industrial Realty Stock Upgrade Means For Shareholders
- Rexford Industrial Realty received an upgrade from Mizuho after the broker highlighted the REIT’s focus on infill Southern California industrial assets and ongoing capital recycling efforts.
- The upgrade drew attention to how Rexford Industrial Realty’s pivot toward higher return repositioning and small bay infill product may influence its earnings mix and cash flow resilience.
- We will now examine how Mizuho’s upgrade of Rexford Industrial Realty could reshape the existing investment narrative built around infill scarcity.
Scan other industrial-focused REITs and logistics landlords that may share Rexford Industrial Realty’s infill scarcity angle by reviewing our curated list of solid balance sheet and fundamentals (25 results)
Rexford Industrial Realty Investment Narrative Recap
For an investor to back Rexford Industrial Realty, the core belief is that infill Southern California scarcity and the 3.5 million square foot development and repositioning pipeline eventually translate into dependable cash generation. The near term swing factor is how efficiently those projects lease up while rent headwinds run through the portfolio. Mizuho’s upgrade and the 1.5% share move are more sentiment than thesis changing.
The biggest operational risk remains pressure on cash re leasing spreads, guided to a 10% to 15% decline in 2026 with similar pressure expected in 2027 and 2028. That backdrop meets a balance sheet that relies on external borrowing and where debt is not well covered by operating cash flow. In the short term, the key question is whether capital recycling and repositionings offset that drag.
The most relevant context around this upgrade is Rexford Industrial Realty’s ongoing portfolio realignment and capital recycling. Management is selling about US$1.5b to US$2.0b of non core assets, with roughly US$1.5b already completed or contracted at around a 5.5% stabilized yield. The goal is to concentrate on higher return repositionings and small bay infill product.
Execution on that plan underpins the main catalysts investors are watching. The firm is leaning on that 3.5 million square foot pipeline, which management expects to support roughly US$50 million to US$60 million of annual NOI once leased, along with planned repayment of about US$1b of 2027 debt and a sizeable share repurchase authorization. The upgrade highlights those levers, but the real test sits in lease up, rent resets and balance sheet progress over the next few years.
Rexford Industrial Realty's current analyst narrative points to forecast 2029 revenue of US$937.4 million and earnings of US$270.0 million, based on an assumed yearly revenue decline of 1.9%, with earnings expected to move from a loss of US$400.6 million today to a profit of US$270.0 million by 2029, which is an earnings swing of about US$671 million.
Uncover how Rexford Industrial Realty's fair value indicates a 7% potential upside to its current price that could narrow quickly as sentiment follows the upgrade.
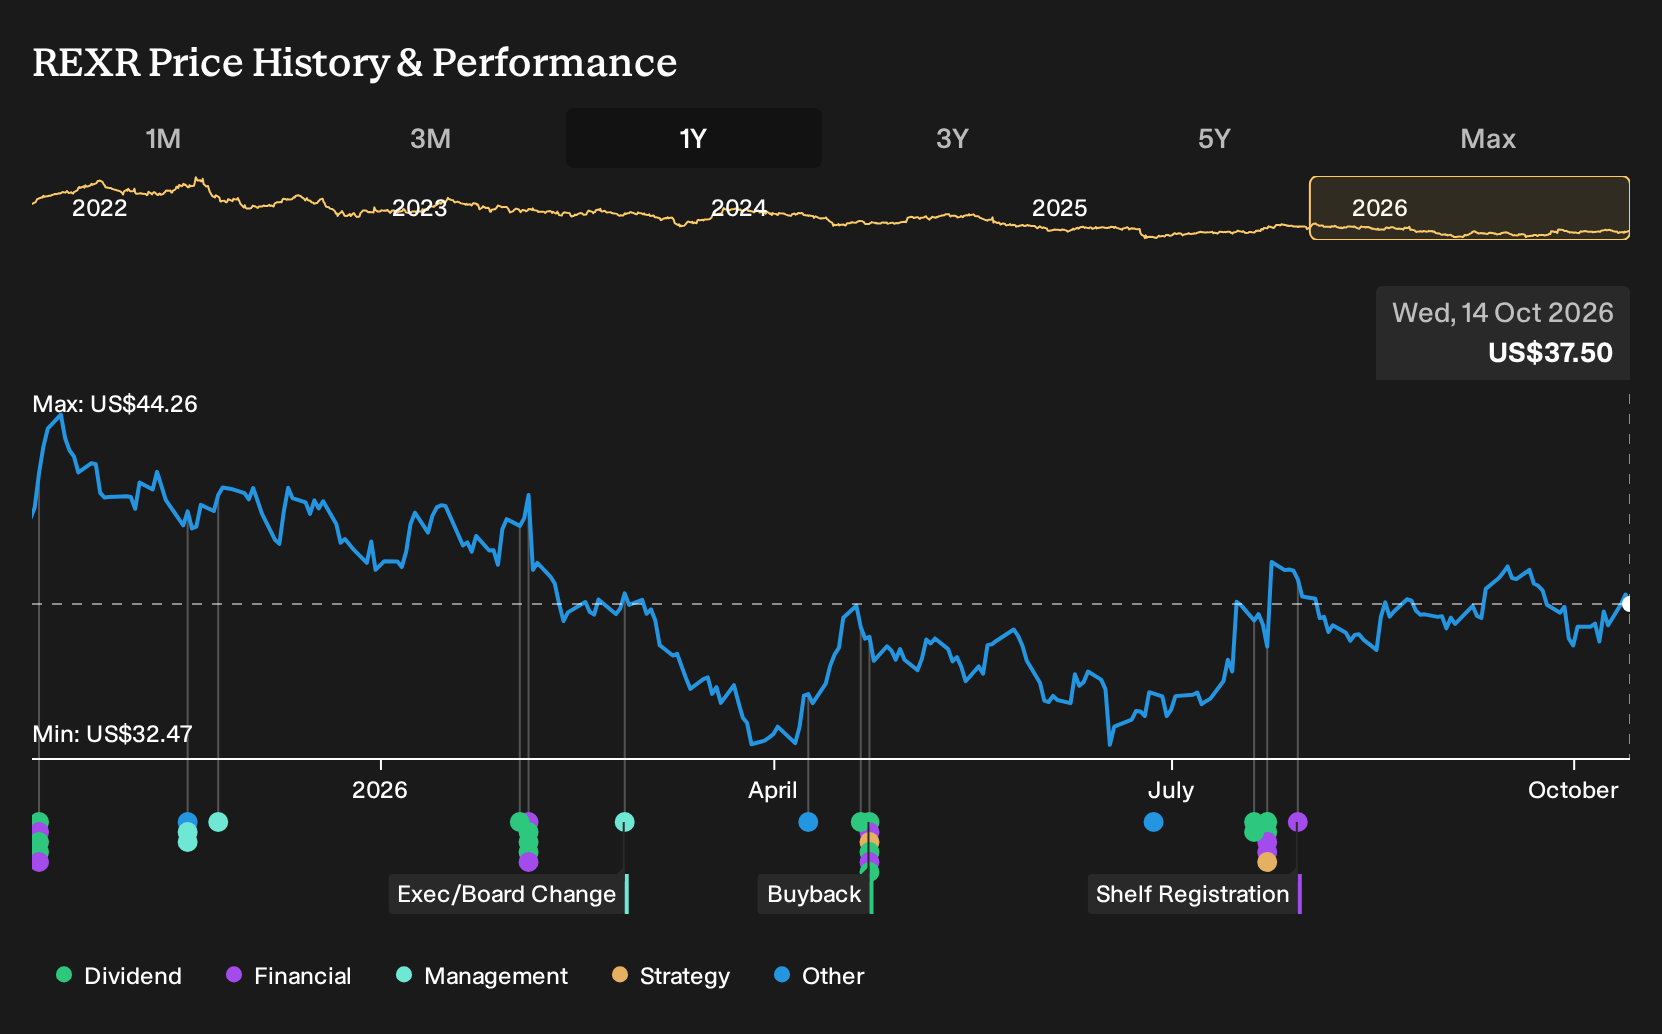
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster in a narrow band between about US$36.7 and US$40.3, which points to relatively tight retail expectations around Rexford Industrial Realty. These opinions sit alongside lease spread pressure, asset sales and the 3.5 million square foot pipeline, so you may want to compare several community views before deciding how this upgrade fits your own thesis.
Explore another Rexford Industrial Realty fair value estimate, including one that suggests as much as 7% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Rexford Industrial Realty research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rexford Industrial Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rexford Industrial Realty's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rexford Industrial Realty?
If you want to put Rexford Industrial Realty’s infill story in context, it can help to line it up against other opportunities with different balance sheet strength, income profiles and risk levels. The Simply Wall St Screener lets you scan a wide range of listed businesses through a fundamentals lens so you can build a watchlist that fits your own return and risk preferences.
- For investors who care most about financial resilience and funding flexibility, review a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with stronger fundamentals.
- If income is your priority and you want to see which payers are offering higher yields, scan a curated mix of 7 dividend fortresses that may align better with a dividend focused approach.
- When you want to search beyond widely followed stocks and look at underappreciated stories, filter through 20 high quality undiscovered gems that combine quality fundamentals with lower visibility in the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com