
How Investors Are Reacting To Forvia (ENXTPA:FRVIA) AI Leadership Shakeup
- Forvia has added Chief Digital and Artificial Intelligence Officer Raphaël Viard to its Executive Committee and expanded Chief Operating Officer Olivier Lefebvre’s remit to lead the JIKA region, signaling tighter alignment between digital priorities and regional execution.
- The combination of a dedicated AI leader at the top table and a single point of accountability for JIKA operations changes how Forvia approaches cost efficiency, data driven decision making and customer proximity across key markets.
- Investors will now be watching how Forvia's AI focused leadership move influences its investment narrative around efficiency, margins and growth.
Forvia Investment Narrative Recap
Forvia appeals to shareholders who buy into a long game built on auto technology content per vehicle, tight cost control and gradual balance sheet repair. The near term story still turns on whether restructuring programs and asset disposals translate into cleaner earnings and better cash generation. The fresh AI and regional leadership moves look helpful for execution, but do not rewrite that core thesis.
The biggest swing factor remains delivery on transformation savings and deleveraging without further strain on cash, while managing exposure to China and currency swings. AI driven efficiency and JIKA oversight may support margins and working capital discipline. If these initiatives stall or costs keep overrunning, the risk is weaker profitability with heavy interest still to service.
The joint venture with ANAND Group in India feels closest to the current leadership reshuffle. Both center on Forvia trying to run more local for local and tie digital capabilities to on the ground production and customer access. The JV focuses on seat frames and complete seats, with Forvia holding a slight majority and plugging its technologies into ANAND’s network.
For you as an investor, the Indian partnership adds another operational catalyst alongside AI and regional governance. It directly links to the order book in seating and to the push for higher margin content with local manufacturing. Execution risk is clear, from ramp up complexity to supply chain and capex discipline. If it runs smoothly, it can support the broader effort to lift returns while restructuring and funding costs are still weighing on results.
Forvia's current analyst narrative points to revenues of €21.3 billion and earnings of €484.8 million by 2029. This setup implies fairly flat annual revenue trends and an earnings swing of about €2.0b from a loss of €1.5b today to those forecast profits.
Uncover how Forvia's fair value indicates a 71% potential upside to its current price that could close sooner than you might expect.
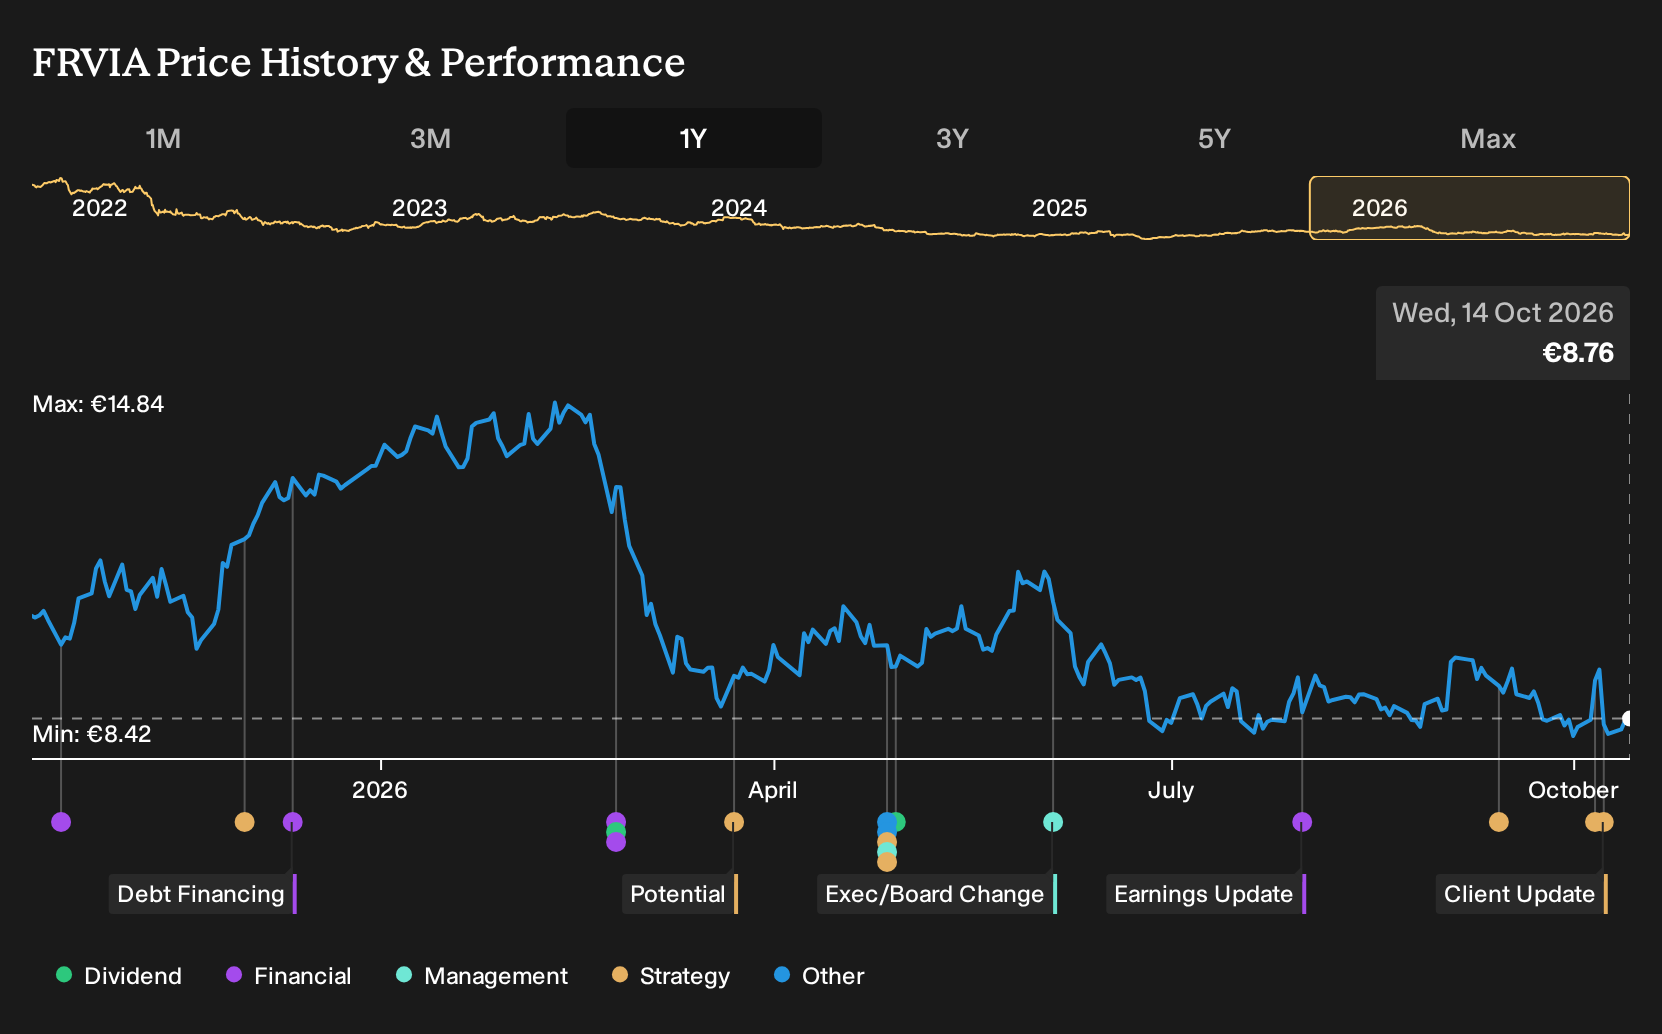
Exploring Other Perspectives
One alternate view focuses on high debt as the real swing factor for Forvia, rather than AI or JIKA execution. Those more pessimistic analysts were working from projections of earnings moving from a loss of about €1.3b to €539.6 million on roughly €20.3b of revenue by 2029. You can read that as a tougher hurdle than consensus, and this week’s leadership changes may eventually push those narratives closer together or even further apart.
Explore 2 other Forvia fair value estimates, including one that suggests it could be worth just €14.57!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Forvia research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Forvia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Forvia's overall financial health at a glance.
Looking For More Ideas Beyond Forvia?
If you want to stress test your Forvia thesis against other opportunities, a quick sweep through the Simply Wall St Screener can help you see where it really stacks up on quality, balance sheet strength and income potential.
- For investors who care most about financial resilience and low downside risk, scan a 223 resilient stocks with low risk scores that can help balance out more volatile positions in your portfolio.
- If income is a priority and you want companies that pay you while you wait, review a curated set of 217 dividend fortresses that may offer meaningful yields with robust fundamentals behind them.
- When you want something a bit less crowded by the market, check a focused group of 613 high quality undiscovered gems that pair solid financials with under-the-radar profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com