
Is Merit Medical Systems (MMSI) Undervalued Following Its Embosphere Recall?
Merit Medical Systems (MMSI) has initiated a voluntary Class II recall of specific Embosphere syringe lots after discovering packaging defects that could compromise sterility. This represents a product issue with clear regulatory and operational implications for investors.
Recent trading suggests investors are still weighing that risk. The share price fell 1.11% over the past day but has a 90 day share price return of 17.80%. Total shareholder return is 7.86% over one year and 34.67% across three years, indicating momentum built over the medium term.
Scan beyond Merit Medical Systems and stress test your healthcare exposure against recalls and balance-sheet strength by reviewing our curated list of solid balance sheet and fundamentals (25 results).
The recall headlines and a 1 day dip tell one story. A 90 day gain of 17.80% suggests another. Which does the current price say Merit Medical Systems is closer to: business strength or changing mood around the stock?
Most Popular Narrative: 14% Undervalued
At a last close of $87.16 against a narrative fair value of $101.45, the current Merit Medical Systems valuation leans toward a discount while still reflecting meaningful expectations for execution.
Merit Medical Systems is still working through multi year efficiency programs that have already lifted non GAAP operating margin to 22.6% in Q2 2026. Management has indicated a total expansion target of about 950 basis points versus 2019. If reached, this could continue to support earnings and free cash flow.
See why 1 investors see Merit Medical Systems as 14% undervalued.
Result: Fair Value of $101.45 (UNDERVALUED)
Still, reimbursement risk around WRAPSODY CIE and ongoing tariff pressure on profitability could both chip away at the upbeat Merit Medical Systems margin story.
Find out about the key risks to this Merit Medical Systems narrative.
Another View: What Multiples Say About Merit Medical Systems
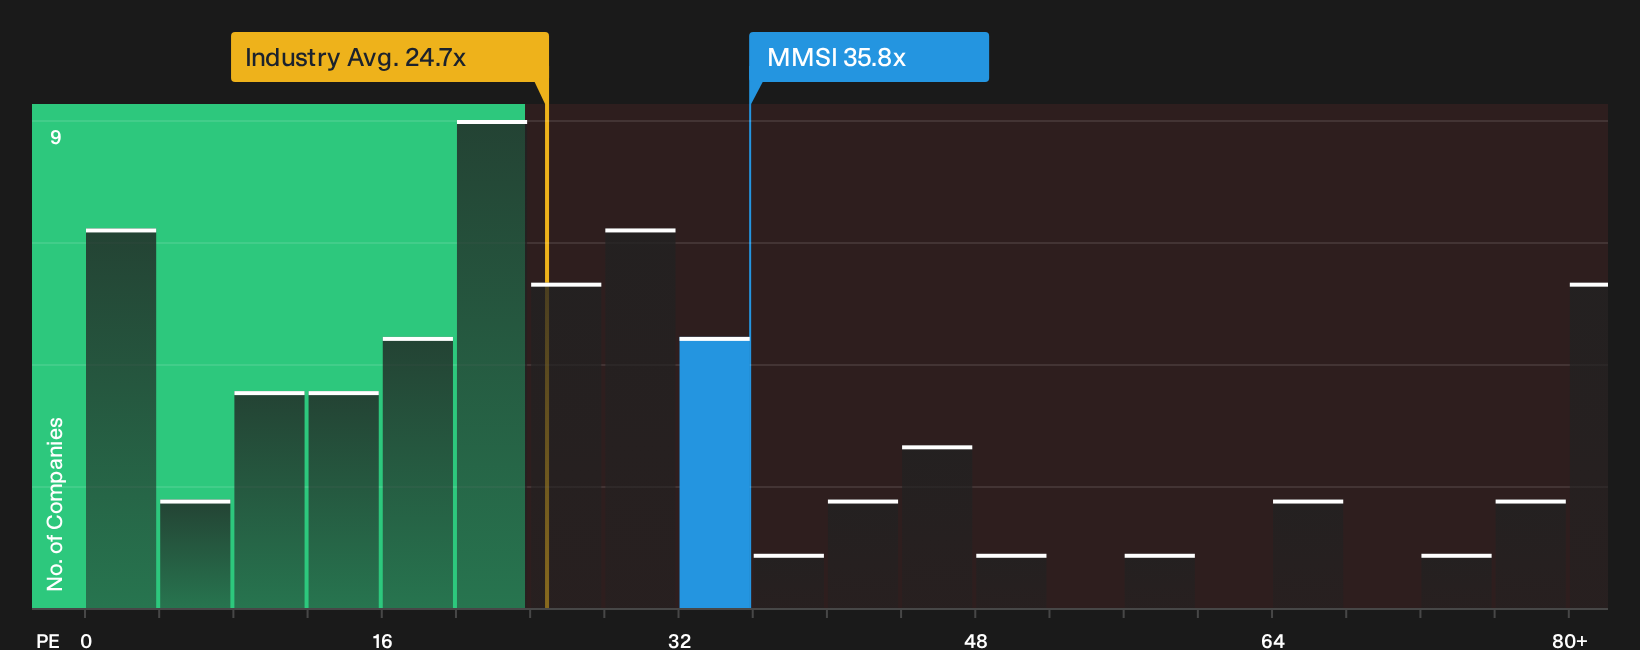
On cash flows, Merit Medical Systems screens as attractive, with the SWS DCF model suggesting a fair value of $107.06 versus the $87.16 share price. The earnings multiple paints a different picture, since a 35.8x P/E is high compared with both the US Medical Equipment sector at 24.5x and a fair ratio of 24.3x. Is that gap a margin story investors are comfortable paying up for, or a valuation risk if sentiment cools?
See what the numbers say about this price, and find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Merit Medical Systems valuation and risk can feel uncomfortable, so move quickly, review the underlying data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Merit Medical Systems?
You have seen what the current Merit Medical Systems story looks like. Now widen the lens with fresh ideas before the next move leaves you catching up.
- Target potential mispricings by scanning a curated 32 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Fortify your future income stream by reviewing a focused 7 dividend fortresses that highlights companies pairing higher yields with staying power.
- Reduce sleepless nights by checking a carefully constructed 32 resilient stocks with low risk scores that concentrates on resilient balance sheets and steadier return profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com