
Undiscovered Gems in Australia to Explore This October 2026
As the Australian market navigates a mixed start to the week, with ASX futures indicating a potential rise despite global concerns over bond yields and geopolitical tensions, investors are keenly observing small-cap stocks for hidden opportunities. In this environment of cautious optimism, identifying undiscovered gems requires a focus on companies with strong fundamentals and resilience amidst fluctuating economic indicators.
Top 5 Undiscovered Gems With Strong Fundamentals In Australia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| West African Resources | 19.46% | 25.90% | 27.84% | ★★★★★★ |
| CTI Logistics | 31.77% | 6.42% | 11.72% | ★★★★☆☆ |
| Servcorp | NA | 7.33% | 26.11% | ★★★★☆☆ |
| Lindsay Australia | 67.18% | 15.96% | 9.84% | ★★★☆☆☆ |
| Pepper Money | 2129.01% | -1.51% | -6.89% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
Pepper Money (ASX:PPM)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Pepper Money Limited is a non-bank lender specializing in mortgage and asset finance across Australia and New Zealand, with a market capitalization of A$766.18 million.
Operations: Pepper Money Limited generates revenue primarily through its mortgage and asset finance segments, with A$202 million from mortgages and A$182.90 million from asset finance. The company also earns A$20.20 million from loan and other servicing activities, while corporate operations reflect a negative contribution of -A$16.80 million.
Pepper Money, a financial player in Australia, has seen its debt to equity ratio improve from 2756% to 2129% over five years, yet it remains high at 2018%. Trading at a significant discount of 68.2% below estimated fair value, the company offers potential upside. Despite being profitable with high-quality earnings, its earnings growth of 9% lagged behind the industry average of 14.5%. Recent board changes saw Mike Cutter retire as an Independent Non-Executive Director after five years on the board; his role in audit and risk oversight now passes to Rob Verlander.
- Click to explore a detailed breakdown of our findings in Pepper Money's health report.
Gain insights into Pepper Money's historical performance by reviewing our past performance report.

Servcorp (ASX:SRV)
Simply Wall St Value Rating: ★★★★☆☆
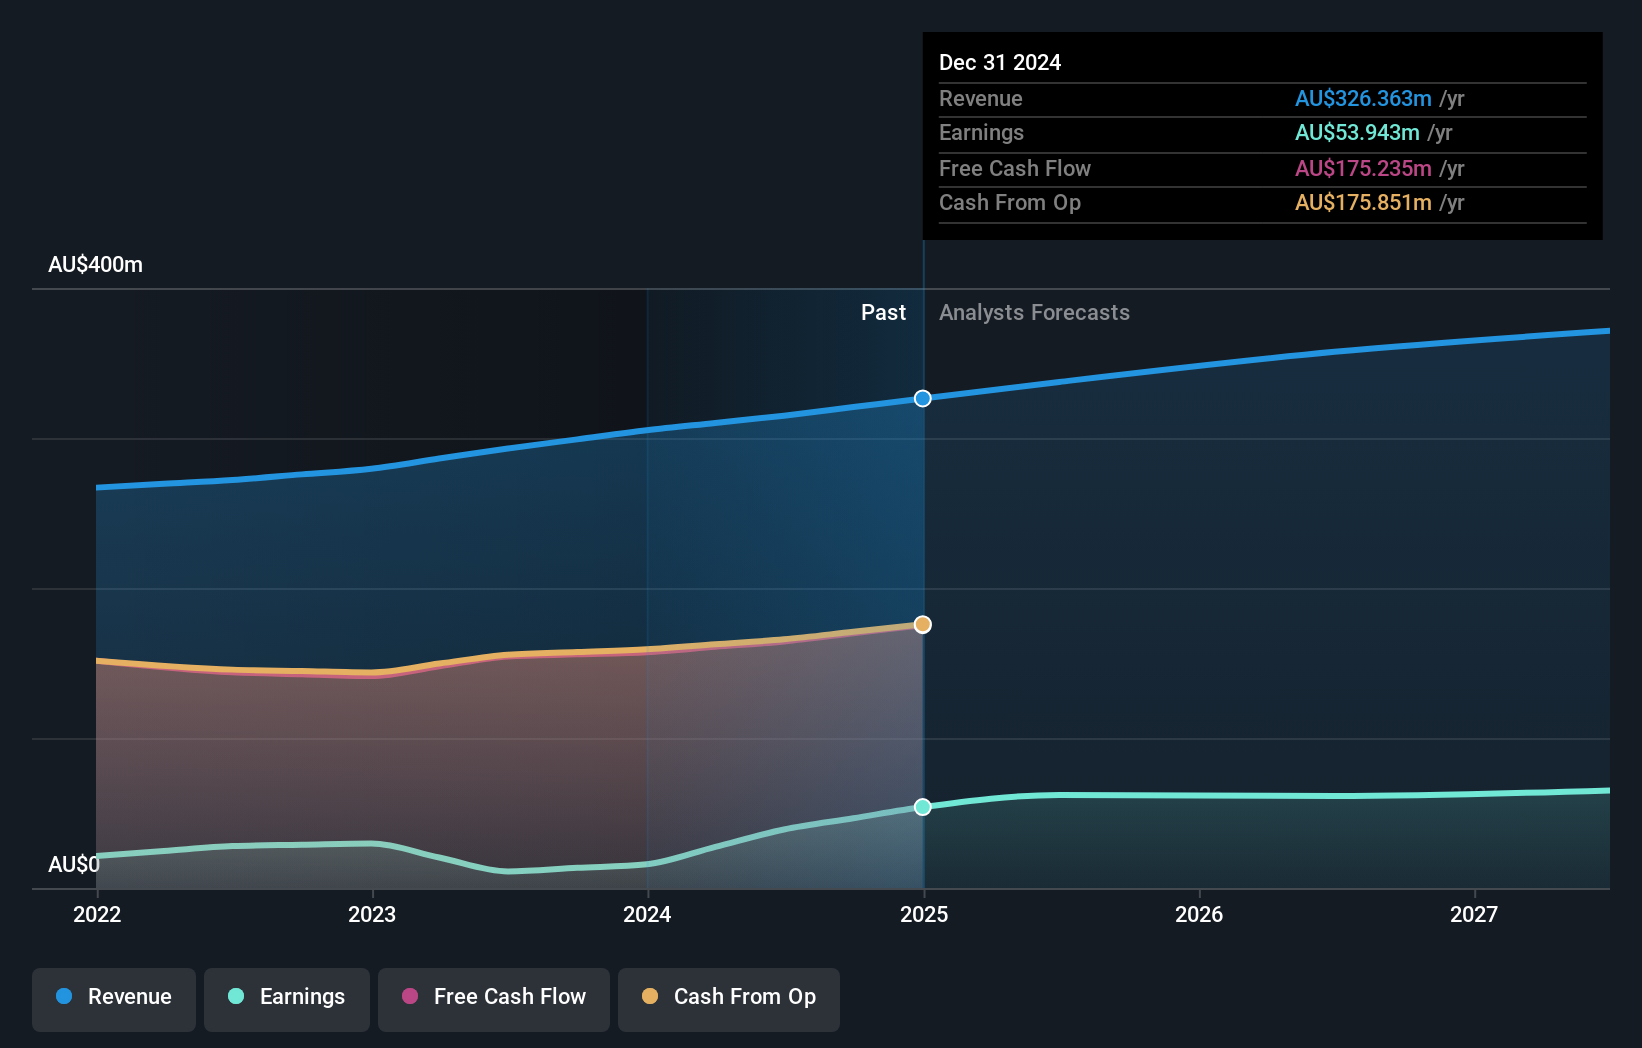
Overview: Servcorp Limited offers executive serviced and virtual offices, coworking spaces, and IT, communications, and secretarial services across various regions including Australia, New Zealand, Southeast Asia, the United States, Europe, the Middle East, and North Asia with a market capitalization of A$541.87 million.
Operations: Servcorp Limited's primary revenue stream is generated from real estate rentals, amounting to A$363.70 million. The company operates across multiple regions, with a market capitalization of A$541.87 million.
Servcorp, a nimble player in the office space solutions sector, stands out with its robust financial health and strategic positioning. Over the past five years, earnings have surged by 26% annually, reflecting strong operational performance. In the latest fiscal year ending June 2026, sales climbed to A$367.5 million from A$352.1 million previously, while net income rose to A$65.6 million from A$53.1 million a year prior—showcasing solid profitability despite industry challenges. The company remains debt-free and boasts high-quality earnings alongside positive free cash flow of approximately A$190 million as of September 2025, underscoring its financial resilience and growth potential within the competitive landscape.
- Get an in-depth perspective on Servcorp's performance by reading our health report here.
Gain insights into Servcorp's past trends and performance with our Past report.
West African Resources (ASX:WAF)
Simply Wall St Value Rating: ★★★★★★
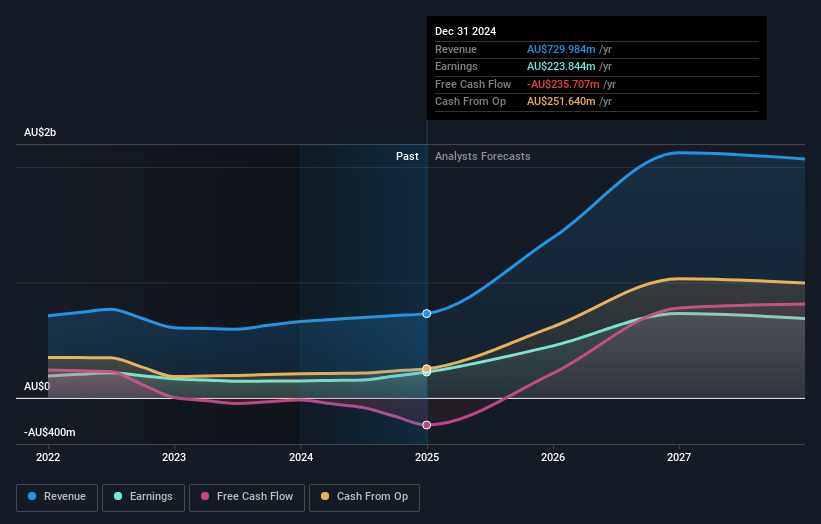
Overview: West African Resources Limited focuses on the mining, mineral processing, acquisition, exploration, and project development of gold projects in West Africa with a market capitalization of A$3.96 billion.
Operations: West African Resources Limited generates revenue primarily through its gold mining and mineral processing activities in West Africa. The company's market capitalization stands at A$3.96 billion, reflecting its position in the industry.
West African Resources, a dynamic player in the gold mining sector, has shown impressive growth with earnings surging 95% over the past year. Its debt-to-equity ratio improved significantly from 60.8% to 19.5% over five years, indicating strong financial health. The company reported sales of A$1.46 billion for the half-year ending June 2026, up from A$477 million a year prior, with net income reaching A$351 million compared to A$186 million previously. Despite these achievements and high-quality earnings, potential risks include operational challenges at Sanbrado and geopolitical tensions in Burkina Faso impacting future performance.
Summing It All Up
- Click through to start exploring the rest of the 2 ASX Undiscovered Gems With Strong Fundamentals now.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com