
Yakult HonshaLtd (TSE:2267) Buyback Keeps Fair Value In Focus
Yakult HonshaLtd (TSE:2267) has just wrapped up a share repurchase that gives investors a fresh data point on capital allocation. The stock now trades against a slightly slimmer share count.
Yakult Honsha Ltd’s buyback lands on a stock that has already logged a 16.94% year-to-date share price return and a 24.97% total shareholder return over the past year. However, the 3-year total shareholder return declined 14.15%, so recent momentum looks stronger than the longer-term trend.
Scan how Yakult HonshaLtd compares with other companies returning cash to shareholders by reviewing our hand picked list of 32 dividend fortresses in today's market.
Yakult HonshaLtd just used nearly ¥11 billion to shrink its share count, which points to confidence in the underlying business. The open question is whether that confidence is already fully reflected in today’s share price.
Most Popular Narrative: 16% Undervalued
Against a last close of ¥2,868.5, the most followed narrative for Yakult HonshaLtd points to a Fair Value of ¥3,400, which puts the recent buyback inside a broader capital return and profitability story.
Management’s explicit ROE objectives of 8% in the current fiscal year and 10% by FY2030, backed by large buybacks, share cancellations and ongoing sales of policy shareholdings that generated gains of JPY 8.9b in FY2026 and JPY 7.7b in FY2025 Q3 year to date, provide a concrete path for Yakult HonshaLtd to compress equity capital and potentially lift future ROE and earnings per share.
See why 0 investors see Yakult HonshaLtd as 16% undervalued.
Result: Fair Value of ¥3,400 (UNDERVALUED)
Still, the bullish Yakult HonshaLtd narrative leans heavily on overseas volume resilience and cost savings, which could be tested by weaker demand in Japan or higher input costs.
Find out about the key risks to this Yakult HonshaLtd narrative.
Another View on Yakult HonshaLtd's Valuation
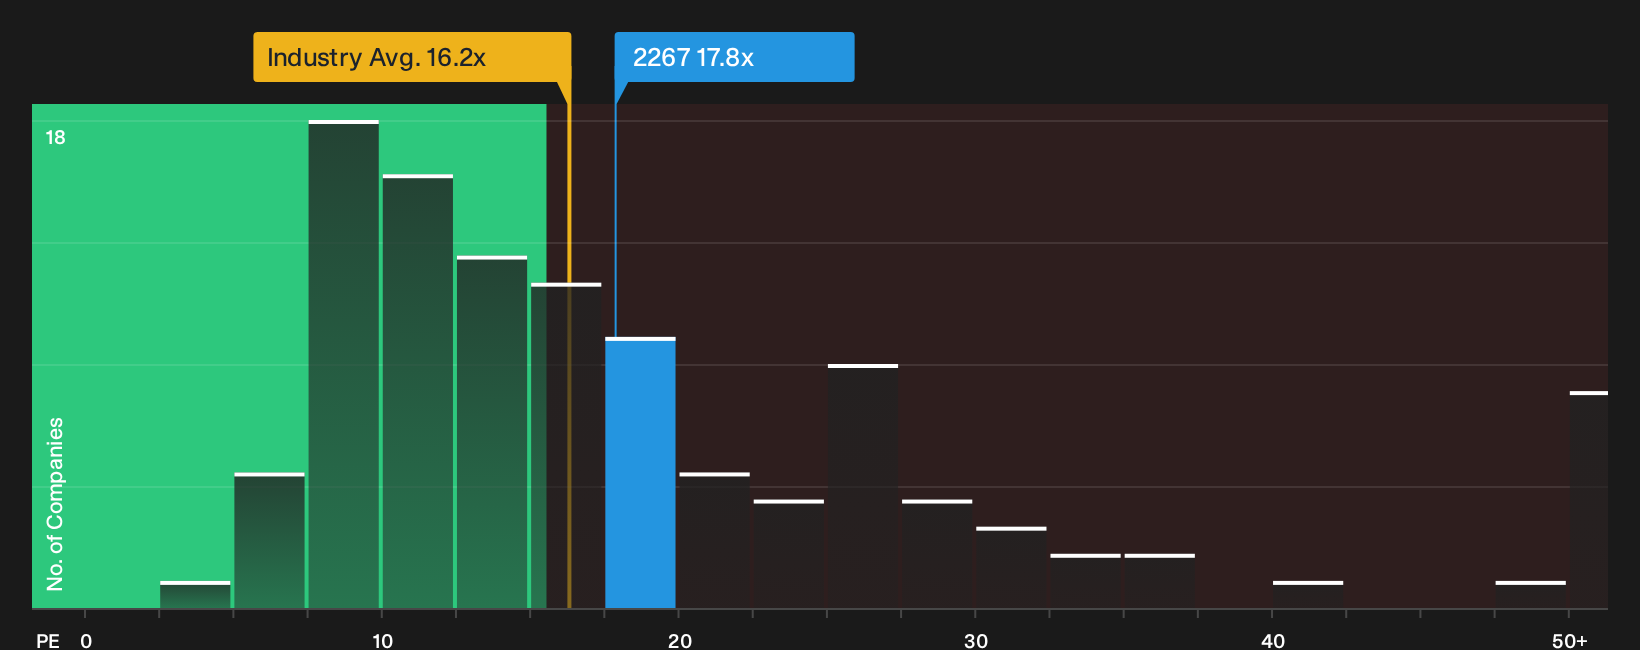
The bullish narrative leans on a Fair Value of ¥3,400, yet the current P/E of 17.8x sits above both the JP Food industry at 16.2x and the peer average at 17.2x. The fair ratio is 16.2x. That premium points to less of a clear bargain and more of a judgement call for you.
To see what this pricing gap might mean for future upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and concern around Yakult HonshaLtd feels balanced to you, consider acting promptly and testing that view against the data yourself with 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Yakult HonshaLtd?
Do not stop your research with a single ticker. Cast the net wider with data driven stock ideas that match what you want your portfolio to do next.
- Target potential mispricing by reviewing companies our tools flag as promising value opportunities through the 15 high quality undervalued stocks.
- Prioritize resilience by scanning businesses with stronger balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (21 results).
- Get ahead of the crowd by tracking underfollowed opportunities that still show solid fundamentals using the 72 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com