
3 Canadian Oil And Gas Stocks With Up To 6% Dividend Yield
Attacks on Saudi energy infrastructure have put global oil flows back in the spotlight, and that pulls Canadian oil and gas producers into sharper focus for investors. When supply routes look more fragile, assets tied to politically stable reserves can draw fresh attention. This article walks through three Canadian oil and gas stocks from our screener and explains what makes each business worth a closer look right now.
The three Canadian producers covered below are just a sample, since the full global screen flagged 41 more oil and gas companies with equally compelling stories that are not listed here.
If you want to identify potential outliers and analyze how they stack up by size, geography, and balance sheet strength, head straight to the Oil and Gas screener.
Topaz Energy (TSX:TPZ)
Overview: Topaz Energy is a Canadian royalty and infrastructure business that earns oil and gas linked income from vast acreage and processing assets.
Operations: Topaz Energy generates about CA$274.9 million from royalties and CA$94 million from infrastructure, all sourced from operations in Canada.
Market Cap: CA$4.6 billion
For investors focused on the Oil and Gas theme, Topaz Energy offers a direct line into production volumes without owning the wells themselves. This is why the structure of its cash generation model matters so much.
"The asset light royalty model with high cash conversion (91% free cash flow margin) and low operating expenses positions Topaz to maintain strong net margins and resilient earnings as investors continue to seek reliable, high-yielding income sources in a moderate interest rate environment."
What happens to that appealing royalty profile depends on how one unseen pressure ultimately filters through to future payout capacity and growth.
That pressure point is exactly what investors need to unpack in the full narrative for Topaz Energy which shows how Topaz Energy’s cash engine could accelerate or stall from here.

Headwater Exploration (TSX:HWX)
Overview: Headwater Exploration is a Calgary based upstream producer that develops and produces crude oil and natural gas from onshore Canadian fields.
Operations: Headwater Exploration generates CA$592 million from exploration, development and production of petroleum and natural gas, entirely from Canadian assets.
Market Cap: CA$3.4 billion
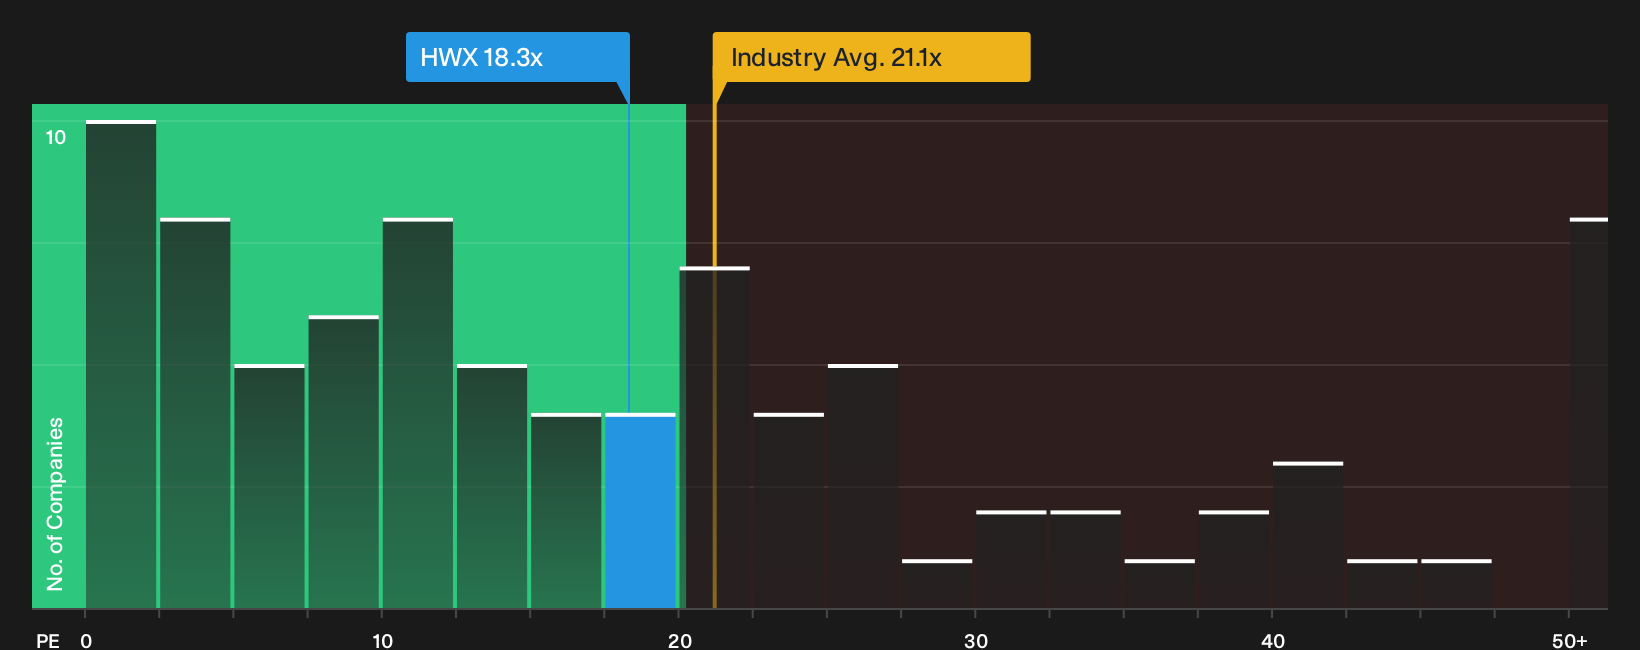
Headwater Exploration provides upstream oil exposure in Marten Hills and McCully Field, supported by 24,567 Boe/d Q2 production and a 22.9% ROE. The stock trades on an 18.3x P/E and a 3.36% dividend yield, so outcomes depend on how upstream cash flow pressures affect that payout and the value investors place on these wells.
That trade off around valuation and payout is exactly what you can stress test through the 2 key rewards and 1 important warning sign to see what the market might be missing.
Freehold Royalties (TSX:FRU)
Overview: Freehold Royalties acquires and manages oil and gas royalty interests in Canada and the U.S., collecting production-based income without operating wells.
Operations: Freehold Royalties generates about CA$322 million from oil and gas exploration and production royalties, roughly split between Canadian and U.S. acreage.
Market Cap: CA$2.8 billion
Freehold Royalties matters in this Oil and Gas screen because it gets a direct slice of production revenue from both Canadian fields and the U.S. Permian, tying your outcome closely to volumes and pricing rather than drilling budgets.
"The commissioning of new pipelines such as the Matterhorn Express facilitates the transport of Permian gas to the Texas coast and LNG terminals, narrowing the Waha-Henry Hub price gap."
One potential variable is how a single pricing shift in that key basin could quietly rewire Freehold Royalties’ royalty margins for the next phase of this cycle.
That pricing shift is exactly what the full narrative for Freehold Royalties unpacks, revealing how Freehold Royalties’ royalty mix could quietly accelerate cash potential while masking basin specific risks.

Seeking Alternatives Before Everyone Else
Fresh ideas move first. By the time momentum is flying, early entries are gone and spreads are already dropping. Scan these under the radar shortlists now and get in early.
- Spot potential early breakouts in dependable cash generators before they get fully priced by institutions through the curated 7 high quality undervalued stocks while it still matters.
- Track powerful trend shifts as money rotates into income payers by scanning a pre filtered pool of 3 dividend fortresses before yields get squeezed.
- Catch under followed operators before attention floods in by reviewing a focused batch of 10 high quality undiscovered gems that screens for quality first, hype second.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com