
SpaceX (SPCX) Stock Looks Above Fair Value After Recent Slide
Space Exploration Technologies has seen its share price slip recently after a strong run of headlines, which puts a sharper spotlight on a simple question for investors. Is the current valuation of SpaceX stock adequately supported by the company’s book value, or has sentiment moved ahead of the balance sheet?
- The stock is down 7.7% year to date, which puts recent enthusiasm around SpaceX under the microscope and raises the issue of how much fundamental asset backing investors are paying for today.
- Plans to raise about US$40b in debt to fund a large build out of AI infrastructure may support revenue potential but could also reshape the capital structure that underpins book value per share over time.
- There is a second opinion on Space Exploration Technologies worth weighing. See what analysts think Space Exploration Technologies's shares could be worth.
The issue now is whether the relationship between SpaceX’s share price and its book value, relative to the industry average, leaves the stock looking well grounded or stretched on this single yardstick.
To see how this book value question looks across other potential ideas, scan the solid balance sheet and fundamentals stocks screener (25 results).
Does Space Exploration Technologies Look Pricey on Book Value?
P/B is a useful yardstick for Space Exploration Technologies because so much of the story is tied to the hard assets and capital intensity behind its satellite and launch infrastructure.
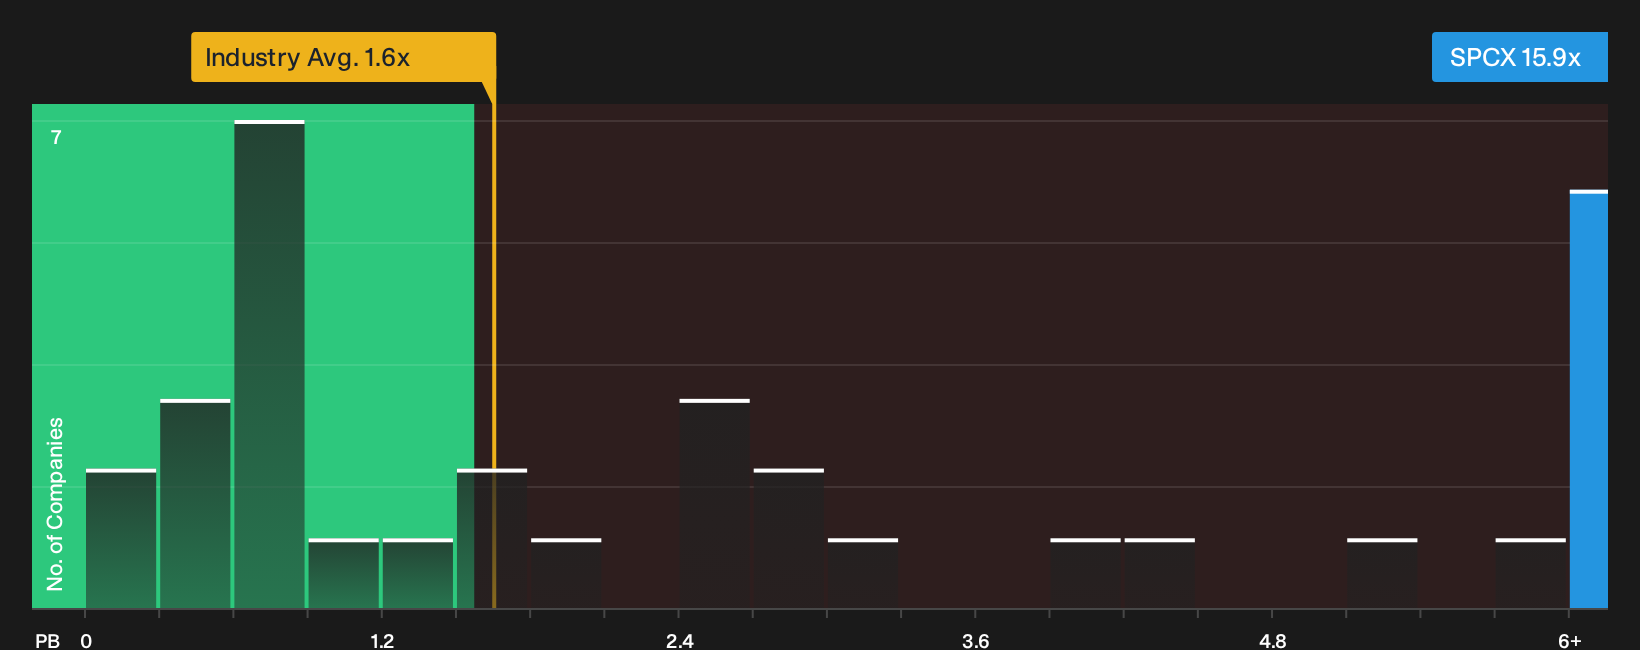
Right now Space Exploration Technologies trades on a P/B of 15.9x, compared with a telecom industry average of 1.6x and a peer group average around 13.9x. That is a steep premium to both the wider sector and closer comparables, which suggests the market is paying a high price for each dollar of stated equity on the balance sheet.
Because the valuation model is heavily penalising losses and balance sheet risk, this gap looks more like a warning flag about how expensively the stock screens on book value than a precise indication of where P/B "should" land. Despite the enthusiasm around SpaceX’s US$40b AI infrastructure debt plan, the current multiple already embeds a lot of optimism into the share price on this metric. Explore the numbers behind Space Exploration Technologies's P/B valuation.
The Space Exploration Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the price to book puzzle for Space Exploration Technologies leaves off. They do this by spelling out what combinations of growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than it is today. Each scenario ties a fair value estimate to a clear storyline about Space Exploration Technologies' potential catalysts and pressure points so you can track which version is aligning with reality over time on the Community page.
Community views on Space Exploration Technologies are split between a multi-layer infrastructure story and a tougher focus on current losses and capital strain.
Bull case: 28% undervalued
"Its emerging structure is more appropriately analyzed as a vertically integrated infrastructure platform built around Space, Connectivity, and AI..."
Discover why this Narrative puts Space Exploration Technologies at 28% undervalued.
Bear case: 10% overvalued
"Although SpaceX’s revenue is growing steadily, the company as a whole is generating a net loss..."
Explore why this Narrative puts Space Exploration Technologies at 10% overvalued.
One more question for Space Exploration Technologies before you move on
Asset values and storylines only go so far without a view on where the business might realistically sit a few years from now, and that is where professional projections give you another benchmark to test against the current price. Explore where analysts expect Space Exploration Technologies to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com