
Here's Why We're Not At All Concerned With Great Dirt Resources' (ASX:GR8) Cash Burn Situation
Just because a business does not make any money, does not mean that the stock will go down. For example, Great Dirt Resources (ASX:GR8) shareholders have done very well over the last year, with the share price soaring by 200%. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
In light of its strong share price run, we think now is a good time to investigate how risky Great Dirt Resources' cash burn is. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
When Might Great Dirt Resources Run Out Of Money?
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. When Great Dirt Resources last reported its June 2026 balance sheet in September 2026, it had zero debt and cash worth AU$3.8m. In the last year, its cash burn was AU$924k. That means it had a cash runway of about 4.1 years as of June 2026. A runway of this length affords the company the time and space it needs to develop the business. The image below shows how its cash balance has been changing over the last few years.
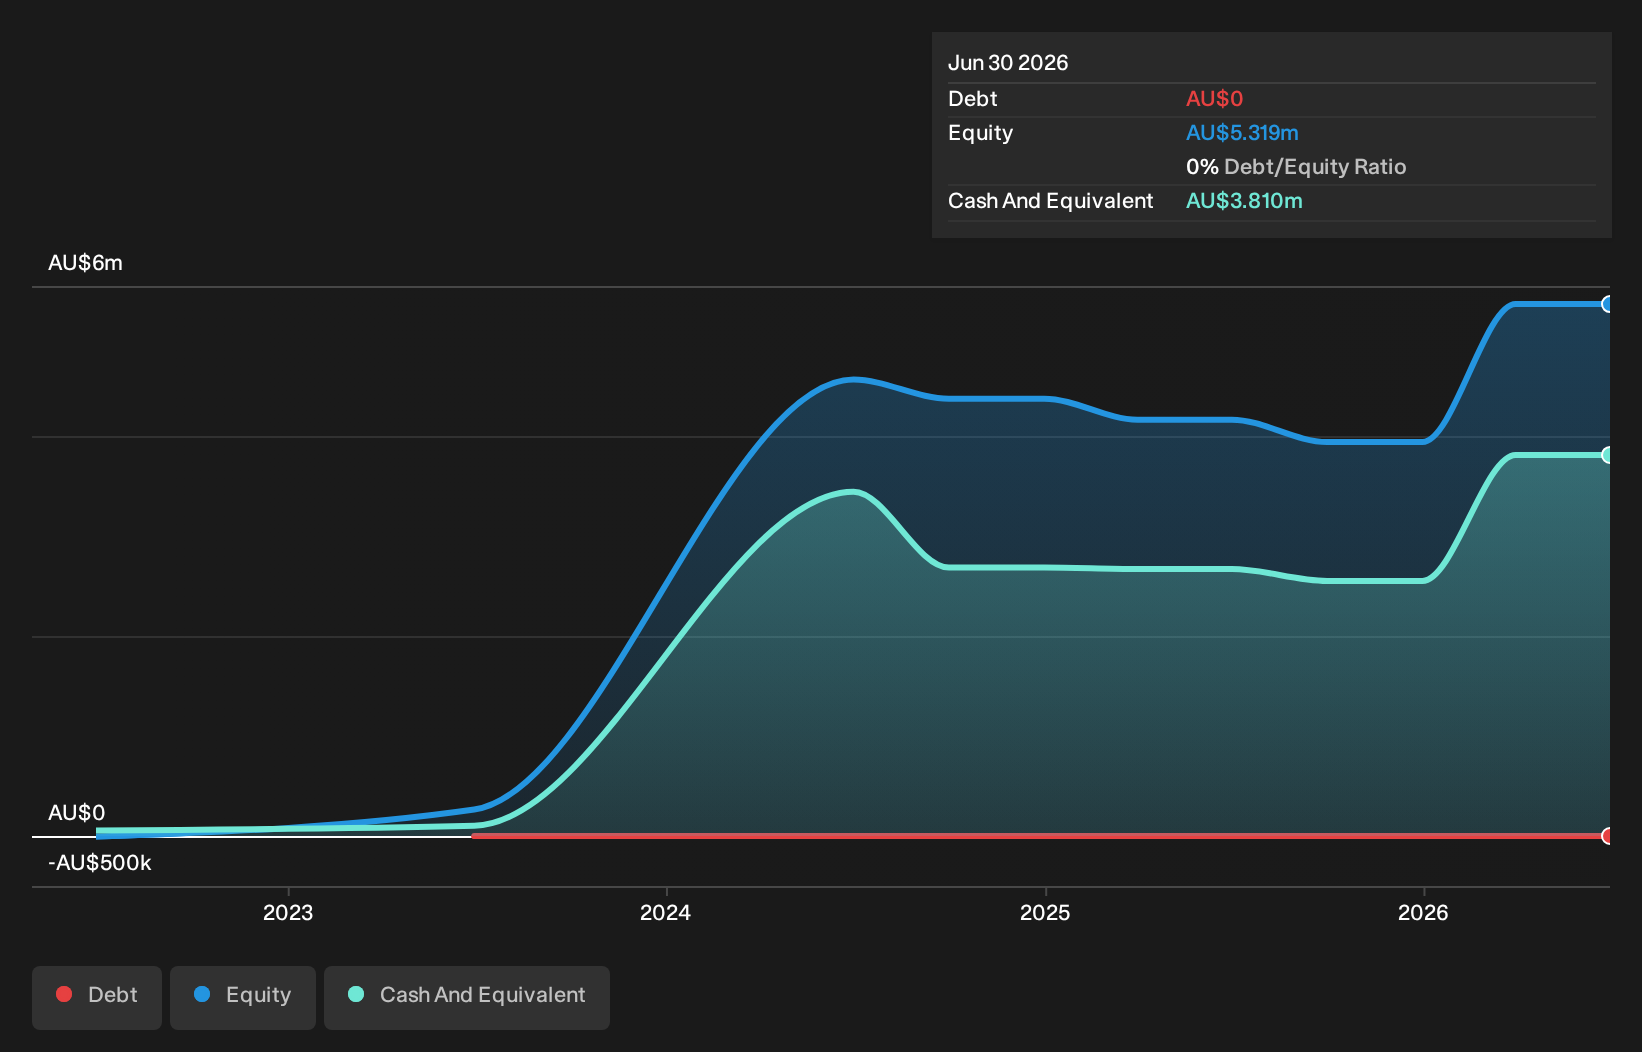
View our latest analysis for Great Dirt Resources
How Is Great Dirt Resources' Cash Burn Changing Over Time?
Great Dirt Resources didn't record any revenue over the last year, indicating that it's an early stage company still developing its business. Nonetheless, we can still examine its cash burn trajectory as part of our assessment of its cash burn situation. While it hardly paints a picture of imminent growth, the fact that it has reduced its cash burn by 20% over the last year suggests some degree of prudence. Admittedly, we're a bit cautious of Great Dirt Resources due to its lack of significant operating revenues. So we'd generally prefer stocks from this list of stocks that have analysts forecasting growth.
Can Great Dirt Resources Raise More Cash Easily?
While Great Dirt Resources is showing a solid reduction in its cash burn, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Companies can raise capital through either debt or equity. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Great Dirt Resources' cash burn of AU$924k is about 3.1% of its AU$30m market capitalisation. Given that is a rather small percentage, it would probably be really easy for the company to fund another year's growth by issuing some new shares to investors, or even by taking out a loan.
Is Great Dirt Resources' Cash Burn A Worry?
It may already be apparent to you that we're relatively comfortable with the way Great Dirt Resources is burning through its cash. In particular, we think its cash runway stands out as evidence that the company is well on top of its spending. Its weak point is its cash burn reduction, but even that wasn't too bad! Looking at all the measures in this article, together, we're not worried about its rate of cash burn, which seems to be under control. On another note, we conducted an in-depth investigation of the company, and identified 5 warning signs for Great Dirt Resources (3 are potentially serious!) that you should be aware of before investing here.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.