
SmartCentres Real Estate Investment Trust (TSX:SRU.UN), What Is Behind The Latest Attention?
SmartCentres Real Estate Investment Trust (TSX:SRU.UN) has just closed a CAD 450 million senior unsecured debenture offering, a financing move aimed at refinancing existing obligations, repaying its credit line, and funding general purposes.
For context, SmartCentres Real Estate Investment Trust’s units trade at CA$26.71, with the share price up 1.06% over the last day and 1.71% across the past week. The 90 day share price return has declined 11.94%, while the 1 year total shareholder return is 8.53% and the 3 year total shareholder return is 47.32%, which points to long term momentum despite more recent weakness.
Spot opportunities with a similar balance sheet focus by scanning our hand picked list of solid balance sheet and fundamentals (8 results) alongside SmartCentres Real Estate Investment Trust after this latest debenture raise.The fresh CAD 450 million in debentures gives SmartCentres Real Estate Investment Trust more breathing room. The key tension now is simple: has most of the upside already played out, or is valuation still offering real headroom?
Price-to-Earnings of 24.6x: Is it justified?
SmartCentres Real Estate Investment Trust changes hands at a P/E of 24.6x, which puts the CA$26.71 unit price at a premium to both its Retail REITs industry and peer averages based on earnings.
The P/E ratio compares what investors are willing to pay today for each dollar of current profit. For a real estate trust like SmartCentres Real Estate Investment Trust, that raises a practical question for you as a unitholder. Is the market assigning a higher tag because it expects steadier income, better asset quality, or simply because investors are paying up despite softer earnings trends?
Earnings have declined by 26.4% per year over the past 5 years and profit margins sit at 16.4%, lower than 24.3% last year. Return on equity is 3.1%, which is described as low. Revenue is forecast to grow 2.3% per year, slower than both the 20% threshold for high growth and the wider Canadian market at 4.6% per year. Against that backdrop, a 24.6x earnings multiple means buyers are paying more for each dollar of profit than the peer average of 18x, despite weaker historic profit growth and pressure on margins.
The comparison with the broader North American Retail REITs industry is also tight. SmartCentres Real Estate Investment Trust trades on a P/E of 24.6x against an industry average of 23.9x. That is a higher tag rather than a discount, even though interest payments are described as not well covered by earnings and recent earnings have been affected by large one off items, including a CA$124.5m loss. The market is therefore valuing the trust at a richer multiple than both sector and peer benchmarks without clear evidence in this data set of stronger historical earnings momentum.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 24.6x (OVERVALUED)
Still, two pressure points could flip the story quickly: interest costs straining earnings coverage, and any deterioration in occupancy that would challenge the current P/E premium.
Find out about the key risks to this SmartCentres Real Estate Investment Trust narrative.
Another View: Our DCF Model Flags Upside
The P/E suggests SmartCentres Real Estate Investment Trust looks expensive, yet our DCF model points in the opposite direction. At CA$26.71, the units trade around 34% below an estimated future cash flow value of CA$40.48. This frames the current price as undervalued rather than stretched.
Look into how the SWS DCF model arrives at its fair value.
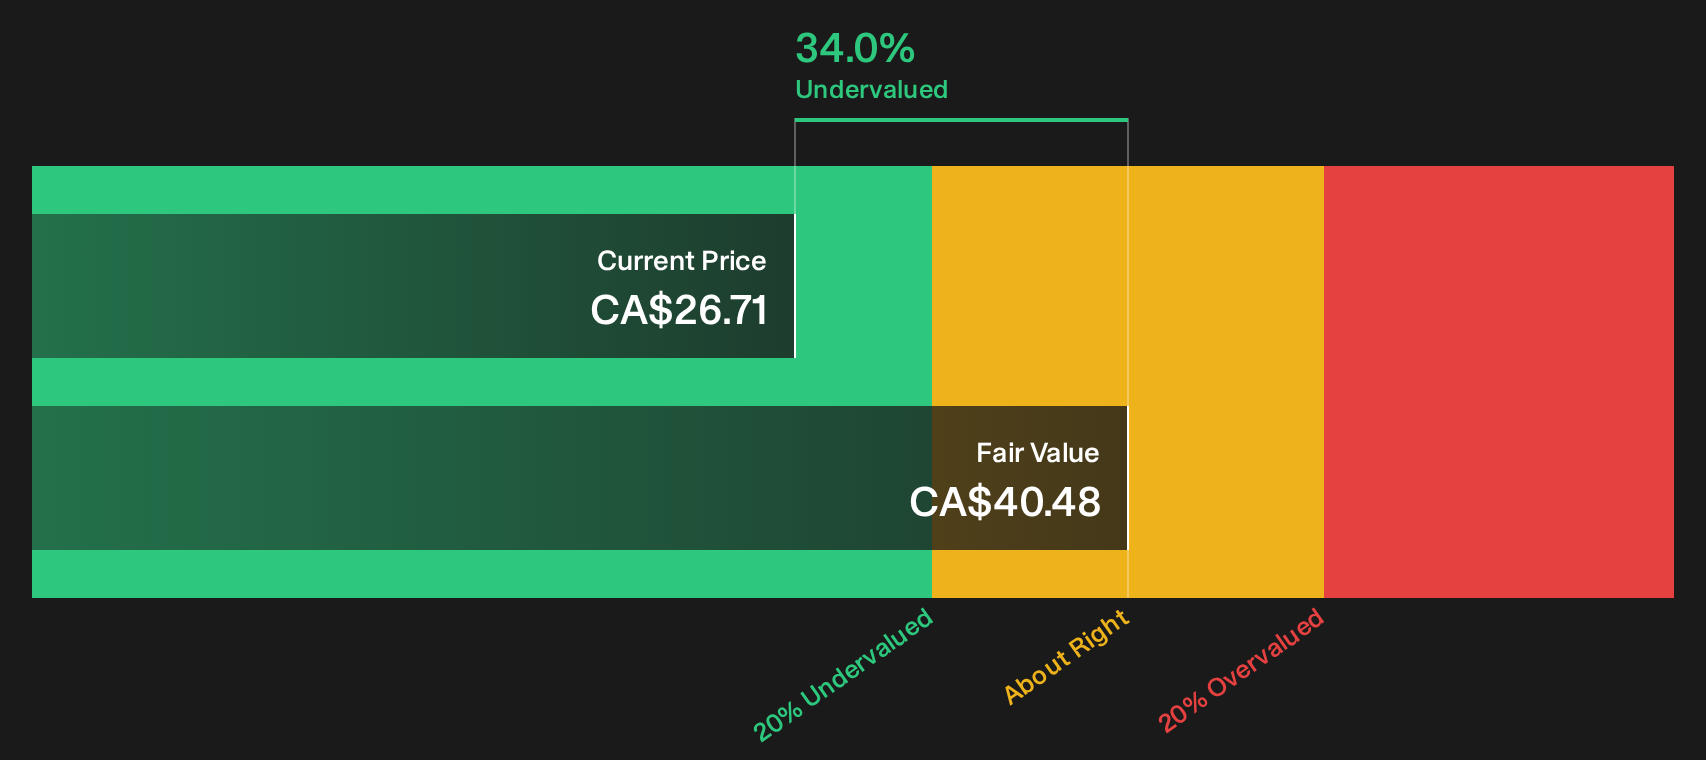
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SmartCentres Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on SmartCentres Real Estate Investment Trust so far. If you want to move quickly and decide where you stand, start by weighing its 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond SmartCentres Real Estate Investment Trust?
If SmartCentres Real Estate Investment Trust has you thinking harder about value and risk, broaden your watchlist now so you are not relying on a single story.
- Target stronger upside potential by scanning a hand picked set of undervalued opportunities through the 10 high quality undiscovered gems.
- Focus on capital preservation and steadier returns by filtering for companies that pass strict resilience checks using the 8 resilient stocks with low risk scores.
- Build a portfolio with healthier fundamentals by zeroing in on financially robust candidates in the list of solid balance sheet and fundamentals (8 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com