
Furoscix Data Could Shape The Case For MannKind Stock
- MannKind reported new clinical data for Furoscix ReadyFlow at the HFSA 2026 meeting, showing IV equivalent pharmacokinetics and diuretic effect across multiple subcutaneous injection sites, with generally well tolerated outcomes in adults with heart failure or chronic kidney disease.
- The analysis compared Furoscix ReadyFlow with the Furoscix On body Infusor and IV furosemide, indicating that both subcutaneous options delivered IV equivalent outpatient diuresis. The autoinjector provided a full 80 mg/mL dose in under 10 seconds, which could matter for workflow, patient adherence and resource use in outpatient care.
- We will now look at how MannKind's broader investment narrative is affected by Furoscix ReadyFlow's IV equivalent autoinjector performance data.
MannKind Investment Narrative Recap
For MannKind, the core belief is that Afrezza, Furoscix and the Technosphere pipeline can collectively carry the business from recurring losses into a self funding model. The short term swing factor is how quickly Furoscix ReadyFlow and Afrezza pediatric use translate into steadier product revenue while R&D and SG&A remain elevated.
The biggest risk is that operating costs tied to launches and pipeline work stay high for longer and keep net income in the red, especially with negative shareholders equity already on the balance sheet. The fresh Furoscix ReadyFlow data mostly reinforces an existing thesis rather than changing near term risk or reward.
The July 2026 FDA approval for Furoscix ReadyFlow appears to be the operational milestone most connected to this new HFSA dataset. Approval created the commercial pathway. The HFSA results now provide more clinical detail on bioequivalence, flexibility of injection sites and practical use in outpatient settings for heart failure and chronic kidney disease.
For catalysts, an investor watching MannKind is likely to focus on how ReadyFlow prescriptions, manufacturing economics and gross margin mix evolve from here alongside Afrezza momentum. Execution risk relates to whether higher Furoscix usage and broader Technosphere partnerships arrive fast enough to offset current losses and reliance on higher risk funding sources.
MannKind's narrative projects US$549.9 million revenue and US$33.5 million earnings by 2029. This aligns with analysts' expectations for 11.8% yearly revenue growth and implies a US$77.1 million earnings improvement from a loss of US$43.6 million today.
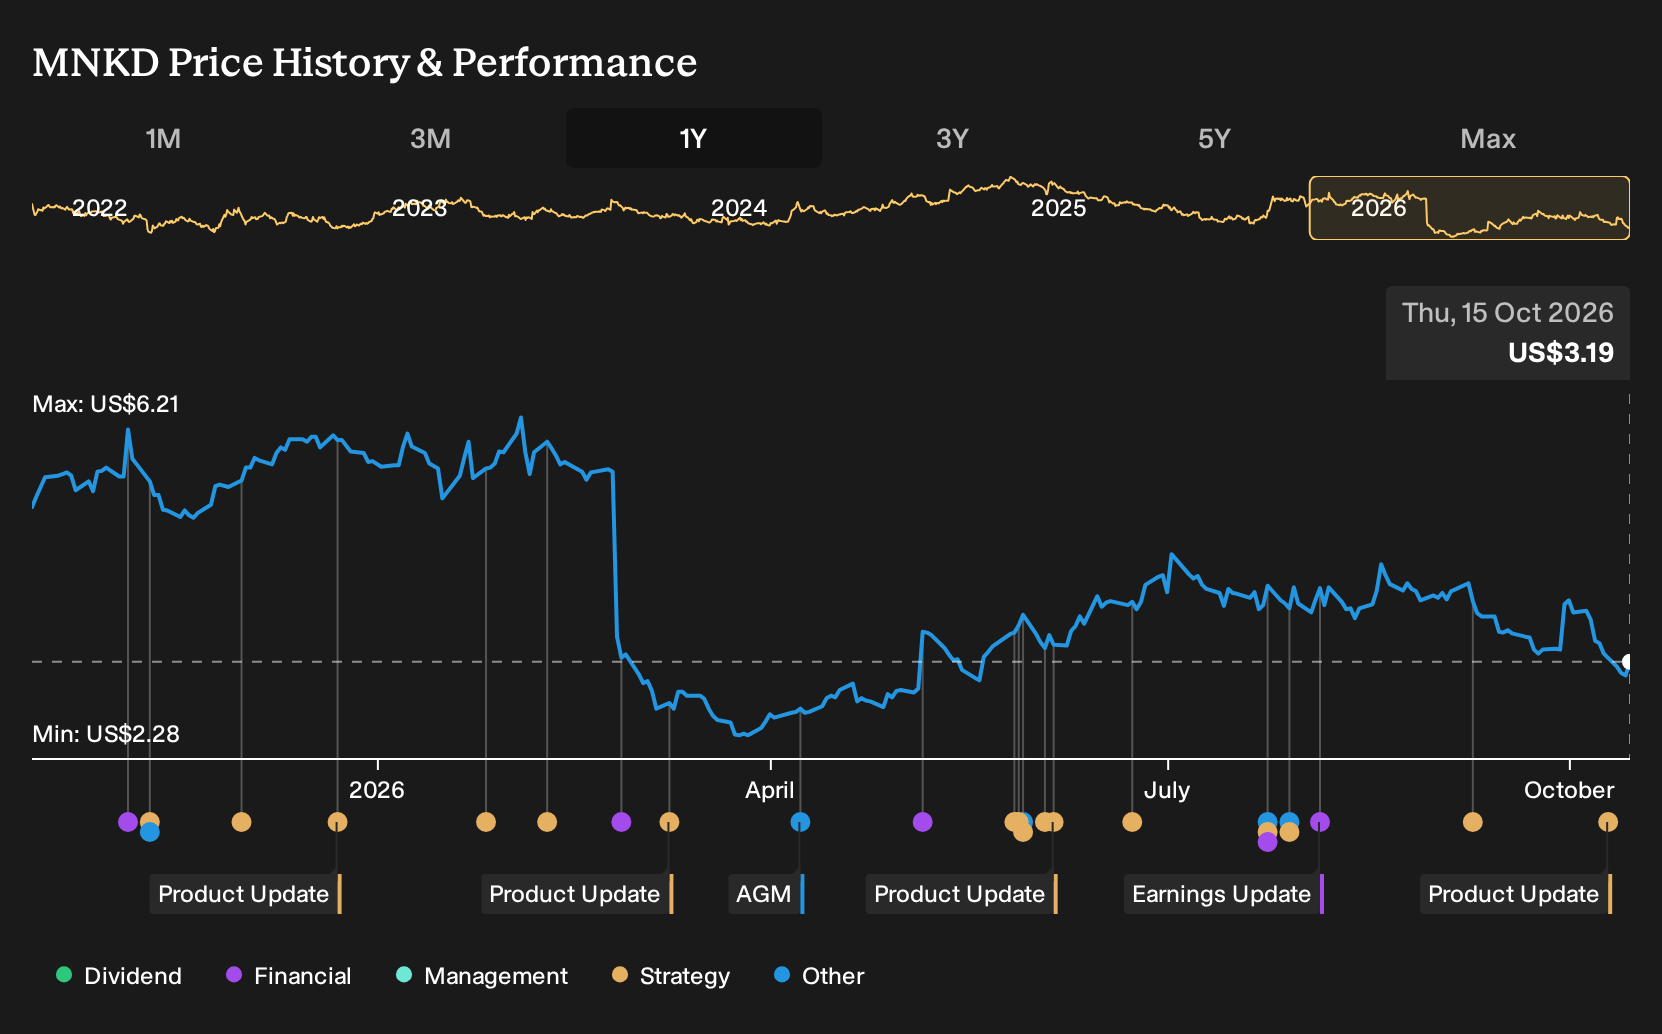
Uncover why MannKind's fair value indicates a 150% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate lens on MannKind focuses less on Furoscix ReadyFlow uptake and more on the risk that higher SG&A linked to Furoscix promotion sticks around. The lowest analysts were only assuming about 6.9% yearly revenue growth and pencilling in roughly US$480.4 million revenue by 2029. That is much more cautious than the consensus US$549.9 million view, and it shows how far opinions can spread before factoring in new HFSA data. You do not need to pick a side today. Use this spread in expectations as an invitation to compare several narratives and decide which assumptions feel closest to your own.
Explore 2 other MannKind fair value estimates, including one that suggests it could be worth just $4.29!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your MannKind research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MannKind. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MannKind's overall financial health at a glance.
Looking For More Investment Ideas Beyond MannKind?
Once you have a view on MannKind, it can help to compare it with other companies that fit different risk and return profiles using the Simply Wall St Screener.
- If you want income potential alongside resilience, scan for companies with stronger yield profiles using our 8 dividend fortresses that might complement a higher risk biotech position.
- For a focus on quality at a reasonable price, run a search using the 32 high quality undervalued stocks and see which businesses pair healthier fundamentals with more conservative valuations.
- When capital preservation matters most, concentrate on financial strength by starting with our 32 resilient stocks with low risk scores that filters for sturdier balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com