
How Global Impact Report Will Impact Hormel Foods Stock
- Hormel Foods released its 20th Annual Global Impact Report, detailing sustainability progress, over 420 new product launches and US$12.4 million in global food access donations, while Bauducco and SKIPPY introduced new co branded Chocottone flavors.
- The report links Hormel Foods' efficiency focus, such as full traceability of purchased palm oil, with its emphasis on higher value products and disciplined cost control, as profitability continues to improve despite softer Retail volumes.
- We will look at how Hormel Foods' investment narrative is shaped by its Global Impact Report and cost disciplined profitability gains.
Hormel Foods Investment Narrative Recap
For Hormel Foods, the core belief is that a wide mix of branded proteins, disciplined cost control and portfolio clean up can support healthier earnings even when retail volumes are under pressure. The key short term swing factor is still how efficiently the Brakebush integration and foodservice push offset weaker consumption in traditional retail channels.
The largest near term risk sits with input costs and pricing elasticity. Commodity volatility in pork, beef and nuts, combined with a lag between cost moves and shelf pricing, could keep margins tight. The latest Global Impact Report and product news do not materially change that near term risk reward balance.
The Bauducco and SKIPPY Peanut Butter Chocottone launch fits neatly into the catalyst of Hormel Foods leaning on higher value branded products and new occasions. It gives SKIPPY another use case in seasonal gifting and snacking, which ties back to the focus on mix and brand reach rather than just chasing volume.
That kind of collaboration also stresses execution risk. Hormel Foods needs these 420 plus recent launches, including Chocottone tie ins, to land with consumers without eroding pricing power or overcomplicating the portfolio. If these items scale smoothly, they can support margin mix and help offset any softness from commodity swings or foodservice slowdowns.
What The Hormel Foods Consensus Is Baking In
Hormel Foods' narrative projects US$13.3b in revenue and US$909.4m in earnings by 2029. This rests on analysts using a 3.2% yearly revenue growth rate and an earnings increase of about US$566.7m from the current US$342.7m base.
Uncover how Hormel Foods' fair value indicates a 28% potential upside to its current price before the discount closes.
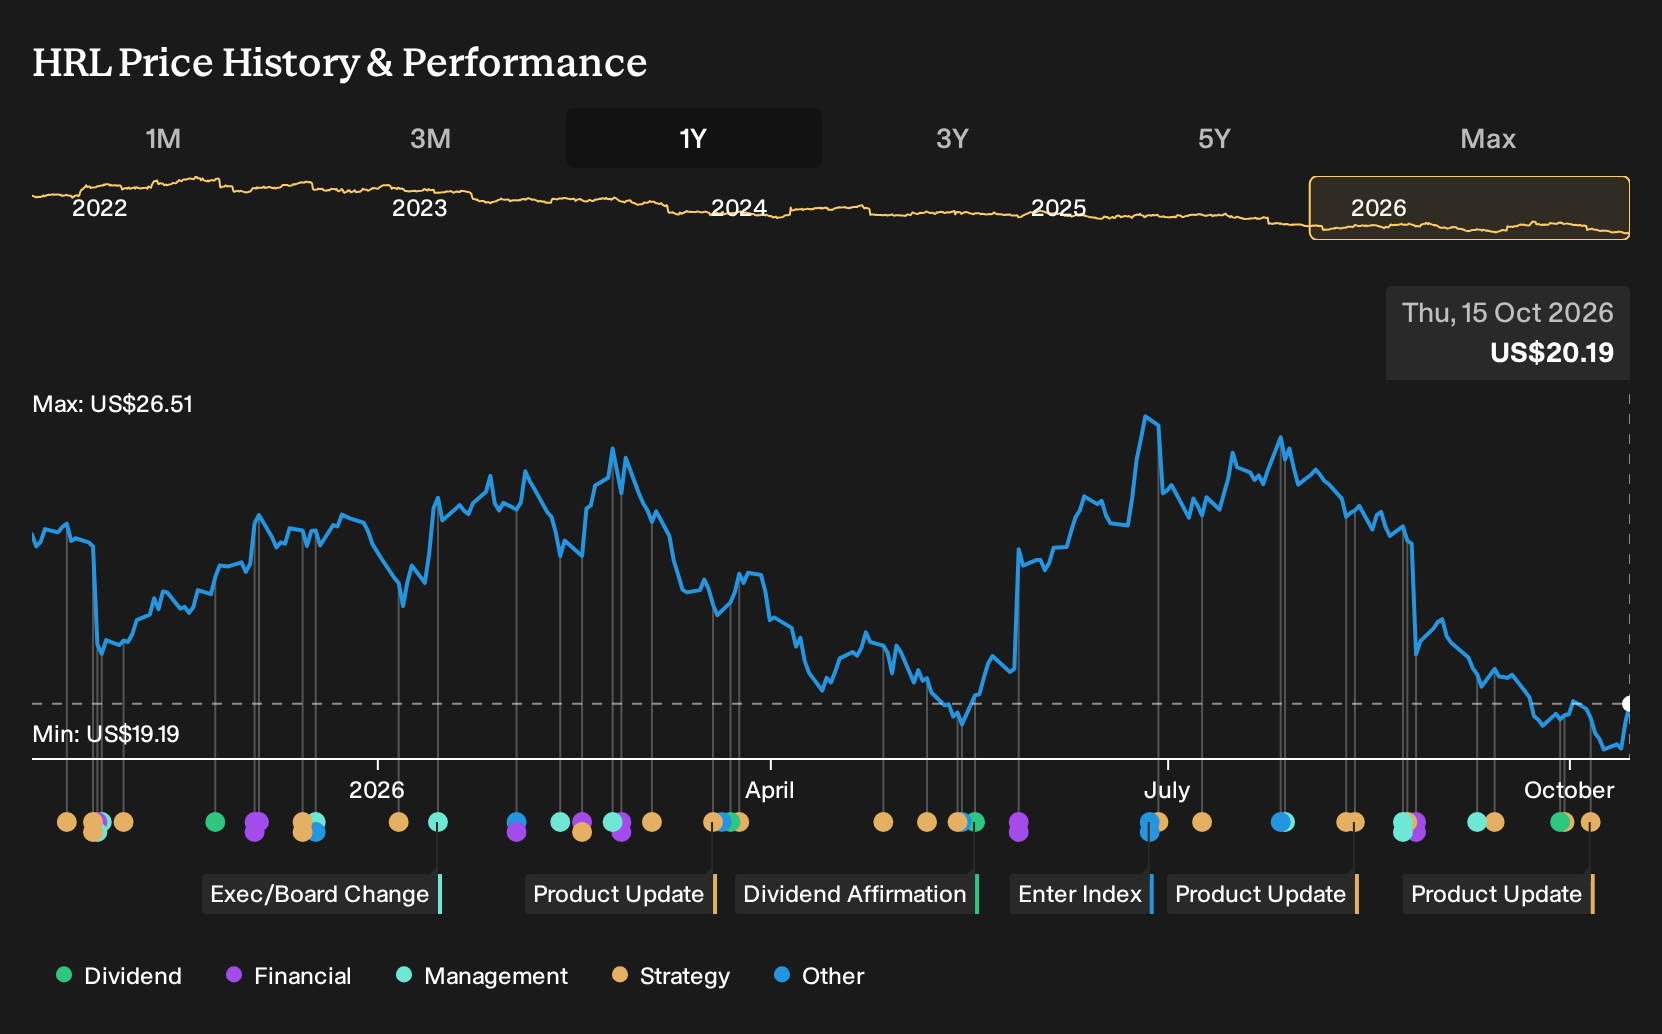
Exploring Other Perspectives
The Simply Wall St Community contributes three fair value views on Hormel Foods, ranging from approximately US$25.31 to US$47.99 per share, which already illustrates how wide the range of opinions can be. When you set that against risks such as commodity cost swings and foodservice reliance, it serves as a reminder that you should assess several viewpoints for yourself.
Explore 2 other Hormel Foods fair value estimates, including one that suggests it could be worth just $25.31!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hormel Foods research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hormel Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hormel Foods' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hormel Foods?
If Hormel Foods has you thinking about quality, income and resilience, it can be helpful to widen the lens and scan other businesses with similar traits using the Simply Wall St screener tools.
- If you want to lean into quality plus valuation, start with a curated set of companies that combine strong fundamentals with attractive pricing by scanning 32 high quality undervalued stocks.
- For investors who care most about steady income, focus on businesses that offer higher yields and robust payout profiles through the 8 dividend fortresses.
- If capital preservation and stability come first for you, narrow your search to companies with stronger financial resilience using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com