
VICI Properties (VICI) Stock Looks Undervalued After A 18% Slide
VICI Properties has seen its share price drift lower over the past year even as headlines focus on its dividend yield and casino lease exposure. That disconnect puts a simple question in front of you as an investor: Does today's US$23.46 price tag still line up with the earnings power backing this real estate investment trust?
- The stock has fallen 18.3% over the past year, which puts fresh pressure on the question of whether the current valuation matches the underlying earnings stream.
- Ongoing rent coverage debates around Caesars and a relatively high debt load can influence how much of VICI Properties' earnings end up available to equity holders and how dependable that cash flow looks over time.
- There is a second opinion on VICI Properties worth weighing. See what analysts think VICI Properties's shares could be worth.
For investors, the debate is whether VICI Properties' current market price is adequately supported by the earnings the business is generating today.
If you are weighing VICI Properties against other income ideas, it can help to compare it with 8 dividend fortresses.
Is VICI Properties Still Cheap on Earnings?
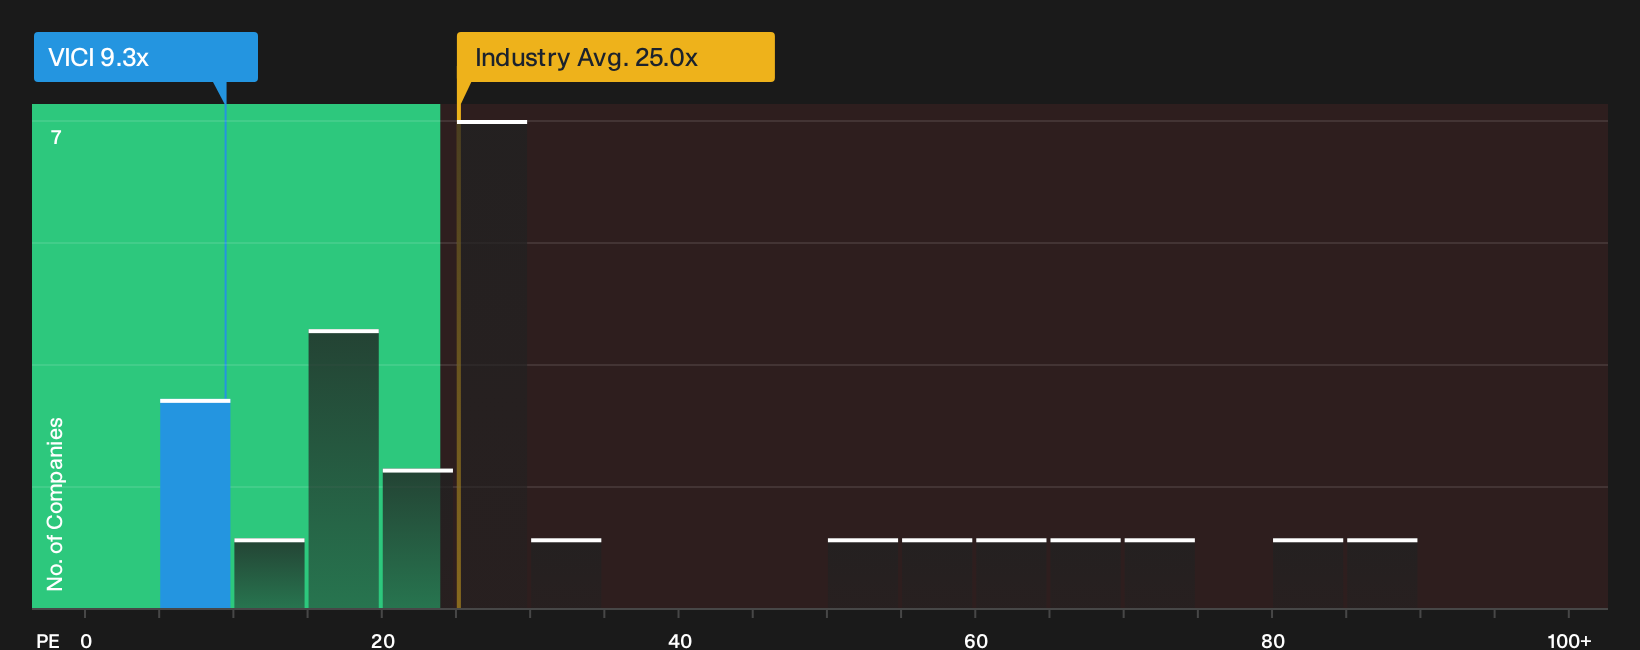
P/E works well for VICI Properties because investors focus heavily on the stability of its casino lease earnings. From this perspective, the stock trades on about 9.3x earnings, which is well below the Specialized REITs sector on roughly 15.1x and also below a broader peer group on about 35.2x. Compared with the multiple implied by the valuation model that blends its growth profile, margins, risk and size, the current P/E sits on the low side. This points to the shares being undervalued on this metric alone.
Because recent headlines have centred on Caesars lease coverage and the Fertitta deal, this discount suggests the market is already pricing in a fair amount of caution despite VICI Properties confirming that rent is being paid as agreed. For you as an income focused holder, the key question is whether those earnings streams remain resilient enough for the gap between price and the modelled fair multiple to look like an opportunity rather than a warning. Explore the numbers behind VICI Properties's P/E valuation.
The VICI Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation gap on VICI Properties' P/E leaves off and spell out what would need to change in growth, margins and earnings power for the stock to look materially higher or lower than today's price. Each scenario links its number to a clear view of how VICI Properties' cash generation, profitability and risk profile could evolve, giving you a reference point you can revisit as fresh information comes through.
One of the top community narratives on VICI Properties: 44% undervalued
"Overall it seems VICI is undervalued at its current market price…"
Discover why this Narrative puts VICI Properties at 44% undervalued.
VICI Properties’ valuation is only part of the story
Price and earnings explain a lot about VICI Properties, but the picture is not complete until you look at the specific risk checks that recent research has flagged for this business. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com