
Cheesecake Factory (CAKE) Rallies On Traffic And Flower Child Growth But Is It Fully Valued
Cheesecake Factory (CAKE) has drawn fresh attention after its shares climbed about 17% over the past month, as investors reacted to stronger guest traffic, improving profitability, and expansion of the Flower Child concept.
Momentum around Cheesecake Factory has been building for a while, with a 20.53% 1 month share price return and a 120.77% year to date share price gain at a recent price of $116.59. The 1 year total shareholder return of 118.76% and 3 year total shareholder return of 302.85% illustrate how strongly recent enthusiasm and earlier recovery have combined.
Look beyond Cheesecake Factory's surge and explore other hospitality and consumer names showing strong momentum and fundamentals with the hand picked 20 high quality undiscovered gems.
Cheesecake Factory has sprinted higher, yet fresh buyers now face a tougher call. Is this a late entry after a hot run, or does the current price still line up with the fundamentals?
Most Popular Narrative: 20% Overvalued
The most followed narrative pegs Cheesecake Factory's fair value at about $97, which sits well below the recent $116.59 share price and frames the rally as ahead of where that model suggests it should be.
The current valuation implies the market is pricing Cheesecake Factory as if digital demand drivers, high-return growth at Flower Child, and mid single digit net income margins will continue to support the share price, even though this narrative views the stock as overvalued and bearish.
See why 38 investors see Cheesecake Factory as 20% overvalued.
Result: Fair Value of $97 (OVERVALUED)
Still, Cheesecake Factory could surprise skeptics if Flower Child continues to deliver strong unit economics and the digital rewards ecosystem continues to support higher traffic and spending.
Find out about the key risks to this Cheesecake Factory narrative.
Another View On Cheesecake Factory Valuation
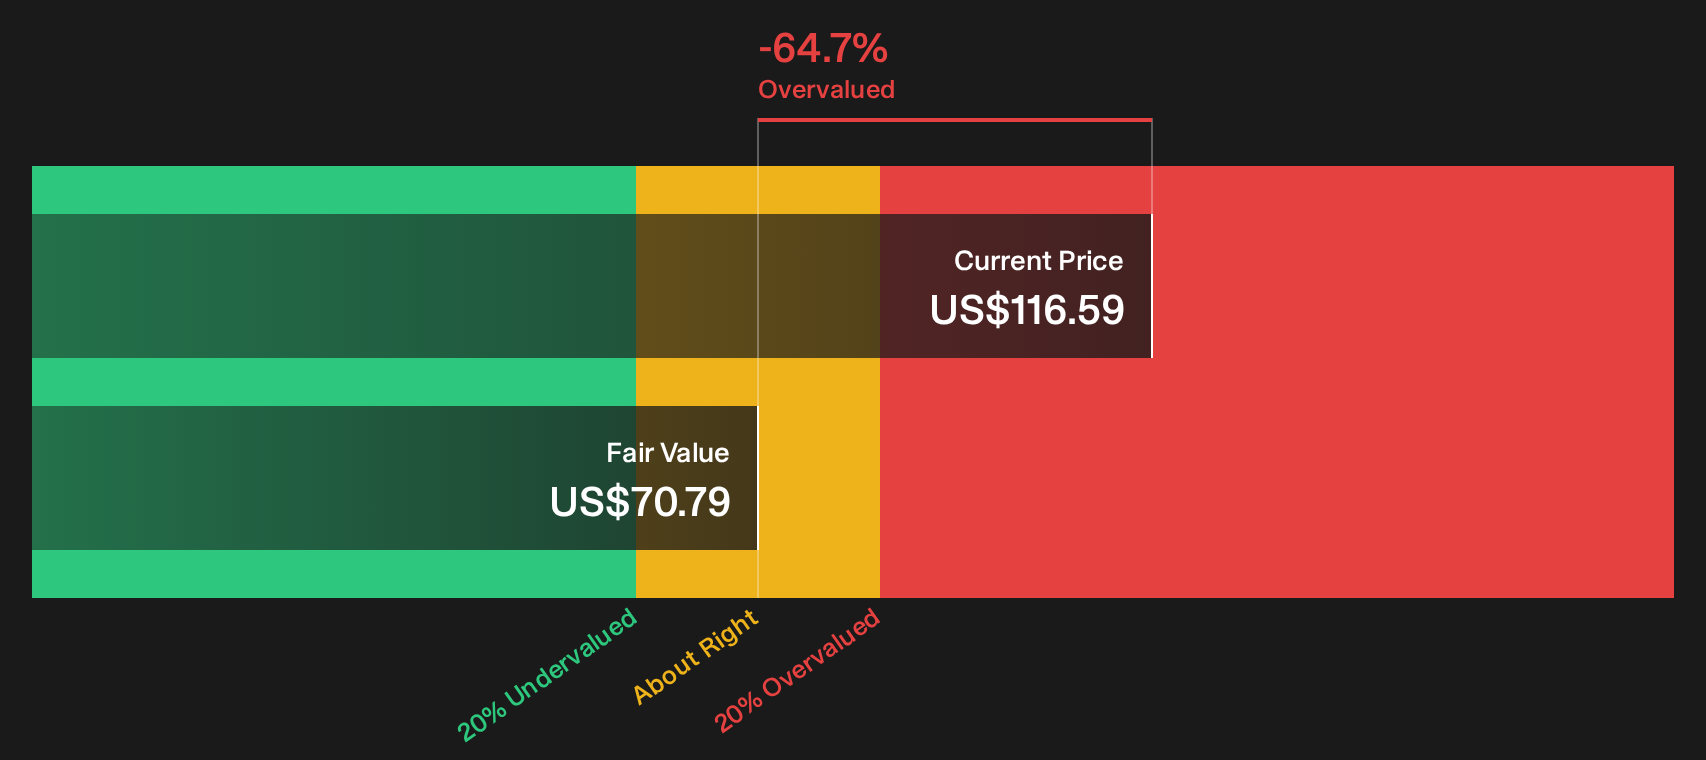
The price based narratives paint Cheesecake Factory as rich, yet the SWS DCF model also points to a premium. With the stock at $116.59 and an estimated future cash flow value of $70.79, this framework also flags the shares as overvalued. Which yardstick do you trust more for your own work?
For a closer look at how those cash flows are treated over time, and how sensitive the outcome is to small changes in assumptions, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Cheesecake Factory's value and risk can be confusing. Consider acting promptly, reviewing the underlying data, and weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cheesecake Factory?
If Cheesecake Factory has your attention, do not stop there. Use curated screeners to quickly surface fresh opportunities that fit your own risk and return preferences.
- Target steady compounders by focusing on balance-sheet strength with the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a sensible entry point by scanning the 32 high quality undervalued stocks.
- Reduce surprises and sleep easier by filtering for companies in the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com