
Woolworths Group (ASX:WOW) Following ACCC Egg Supply Case, Is It Fully Valued?
The ACCC’s new civil case against egg producer Sunny Queen and several peers, alleging cartel conduct that affected supply to major supermarkets, puts Woolworths Group (ASX:WOW) under fresh scrutiny regarding its grocery sourcing relationships.
Woolworths Group’s A$41.28 share price sits after a strong run, with a 30 day share price return of 5.90% and a year to date share price gain of 40.27% pointing to building momentum. A 1 year total shareholder return of 59.70% and 5 year total shareholder return of 20.89% show how recent strength compares with a more measured longer record.
Scan how other retailers and consumer stocks react to supply chain and pricing pressure by reviewing our curated list of 6 resilient stocks with low risk scores along with Woolworths Group’s recent run.
After a sharp move and fresh questions around supply relationships, Woolworths Group now asks something different of new buyers. Does the current valuation still offer enough upside for the risks on the table?
Most Popular Narrative: 5.3% Overvalued
Woolworths Group last closed at A$41.28 against a widely followed fair value estimate of about A$39.20. This frames today’s debate around how much future margin improvement is already baked into the share price.
The ongoing investment and upgrades in Woolworths' supply chain automation and distribution centers are expected to drive significant operational efficiencies and margin improvement over the next few years, as dual running and commissioning costs roll off and new facilities like Moorebank and Auburn CFCs deliver returns, likely supporting higher future EBIT and ROIC.
See why 85 investors see Woolworths Group as 5% overvalued.
Result: Fair Value of A$39.20 (OVERVALUED)
Still, wage pressure and heavier capital spending on automation could squeeze Woolworths Group margins if cost savings, pricing and volume do not line up as analysts expect.
Find out about the key risks to this Woolworths Group narrative.
Another View: DCF Pitches Woolworths Group As Underpriced
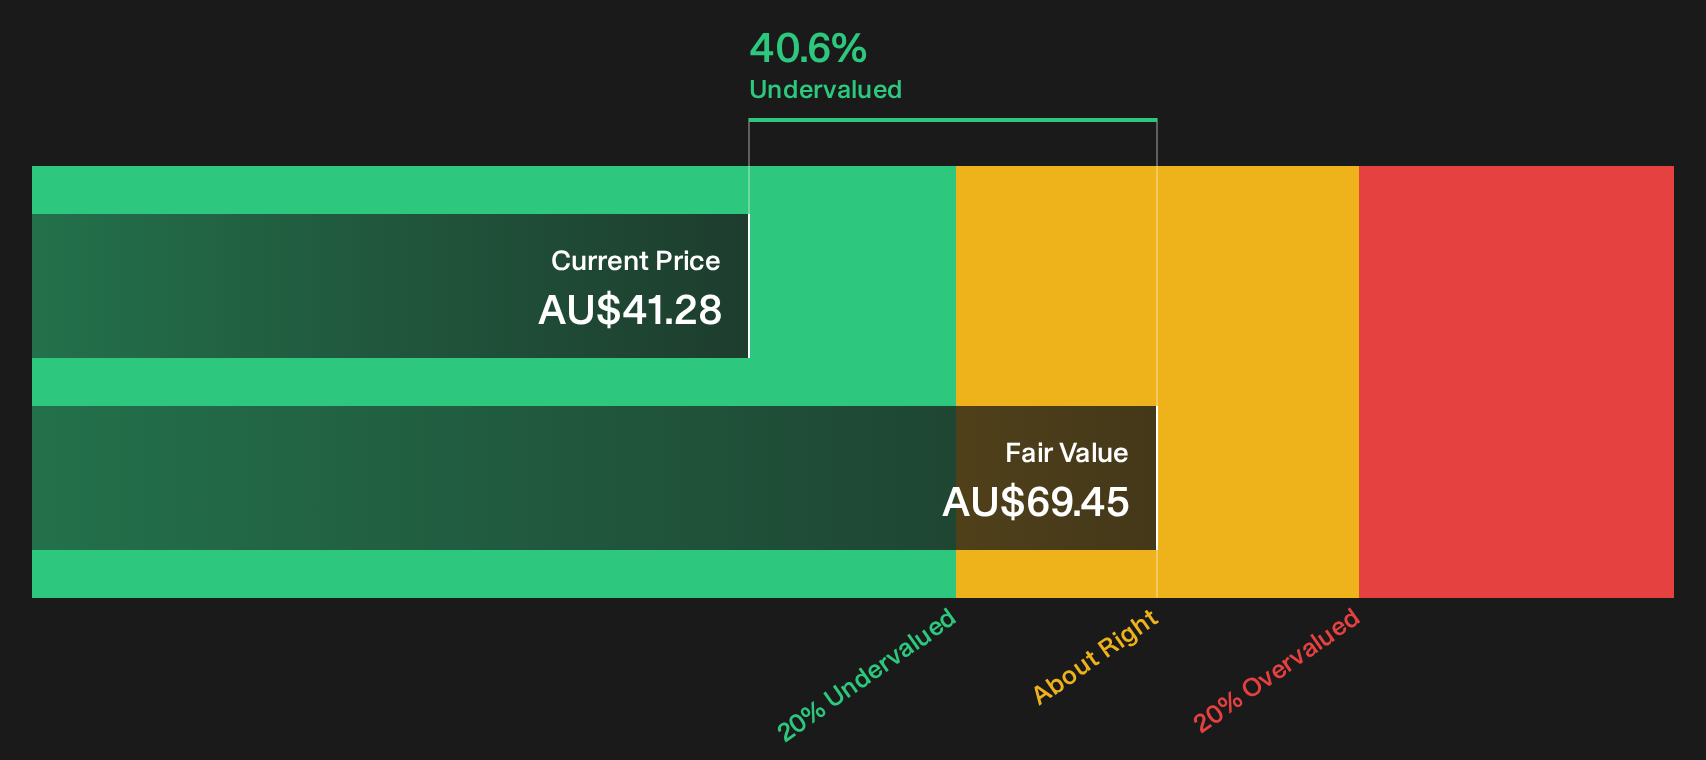
The earlier analyst consensus framed Woolworths Group as about 5.3% overvalued at A$41.28 against a fair value near A$39.20. A very different signal comes from our DCF model, which points to an intrinsic value of roughly A$69.45, suggesting the shares trade at about a 40.6% discount instead.
That gap is significant in practical terms. One framework treats Woolworths Group as fairly fully valued around current levels. In contrast, the SWS DCF model implies the market is heavily discounting its long term cash generation and return on equity profile. Which set of assumptions on margins, capital intensity and discount rate appears more realistic to you over a full cycle?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Woolworths Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Woolworths Group often create the most interesting setups, so move quickly through the data, weigh both sides and judge for yourself with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Woolworths Group?
If Woolworths Group has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist now or risk missing the next opportunity.
- Target resilient balance sheets and steady fundamentals by scanning our curated list of solid balance sheet and fundamentals (12 results), which can sit alongside a position in Woolworths Group.
- Hunt for potential mispricings with the focused 4 high quality undervalued stocks, which filters for quality businesses trading below their estimated worth.
- Strengthen your income ideas by reviewing the yield focused 3 dividend fortresses, which highlights companies offering higher dividend payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com