
Is Bunzl (LSE:BNZL) Fully Valued On Its Analyst Upgrade And Earnings Revisions?
Bunzl (LSE:BNZL) is back on investor radars after an analyst upgrade to a top rating, driven by several months of upward earnings estimate revisions and improving sentiment around its business outlook.
Recent trading reflects that optimism. Bunzl’s share price has climbed to £28.42, with a 1 month share price return of 9.73% and a year to date share price return of 37.69%. The 1 year total shareholder return of 21.59% suggests momentum has been strong over both shorter and longer timeframes.
Scan for other Bunzl like movers that are benefiting from upgraded earnings sentiment with a curated list of 9 high quality undervalued stocks.
Bunzl’s sharp move has already rewarded recent holders, which leaves you with a familiar dilemma: Is it worth paying up after this surge, or does patience for a cheaper entry make more sense once valuation is on the table next?
Most Popular Narrative: 2% Overvalued
Bunzl last closed at £28.42, slightly above the most followed fair value estimate of £27.79. This frames the current rally as leaving modest headroom on the upside based on that narrative.
The turnaround of the North America Distribution business, which suffered from over-centralization and execution missteps but is now regaining local autonomy, improving service and inventory levels, and re-energizing sales teams, sets the stage for a recovery in revenue growth and operating margin beginning in H2 2025 and accelerating through 2026, though current results do not yet fully reflect these improvements.
See why 34 investors see Bunzl as 2% overvalued.
Result: Fair Value of £27.79 (OVERVALUED)
Still, if Bunzl struggles to lift organic revenue, or if margin pressure in North America and Continental Europe persists, that fair value story could quickly look stretched.
Find out about the key risks to this Bunzl narrative.
Another View: Cash Flow Says Bunzl Looks Cheap
The analyst narrative frames Bunzl as 2% overvalued at £27.79, yet the SWS DCF model points in the opposite direction. On that method, the shares trade at £28.42 against an estimated future cash flow value of £31.42, which indicates that Bunzl is undervalued instead.
These two yardsticks rest on different assumptions and risk appetites. The key issue is which one aligns more closely with how you think Bunzl’s earnings and cash generation could change over time, and how much flexibility you want at today’s price.
Look into how the SWS DCF model arrives at its fair value.
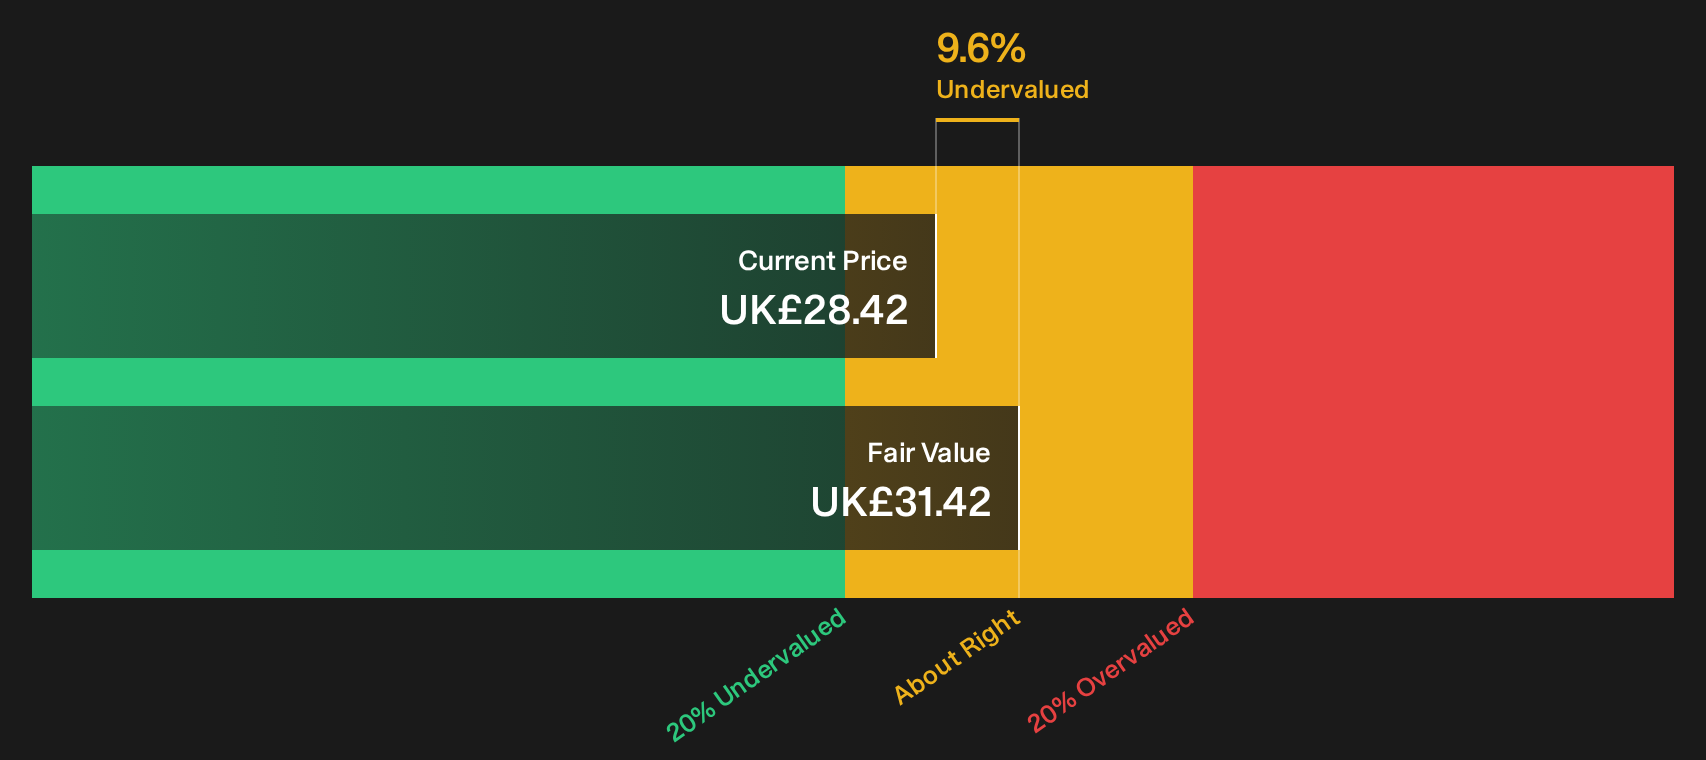
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bunzl for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 9 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If sentiment around Bunzl still feels divided, move quickly to review the underlying data yourself and decide where you stand on its mix of risk and upside potential. To help frame that view in a structured way, start with the balance of 3 key rewards and 2 important warning signs
Looking for more Bunzl style investment ideas?
Do not stop your research with Bunzl alone. The screener can surface other opportunities that fit your style before they move out of reach.
- Target quality at a reasonable entry by scanning a curated set of 9 high quality undervalued stocks that combine strong fundamentals with appealing pricing.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (9 results) that can help you focus on companies with sturdier financial footing.
- Get ahead of the crowd by uncovering a 5 high quality undiscovered gems that might not yet sit on every investor’s watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com