
What Bodycote Shareholders Got Right
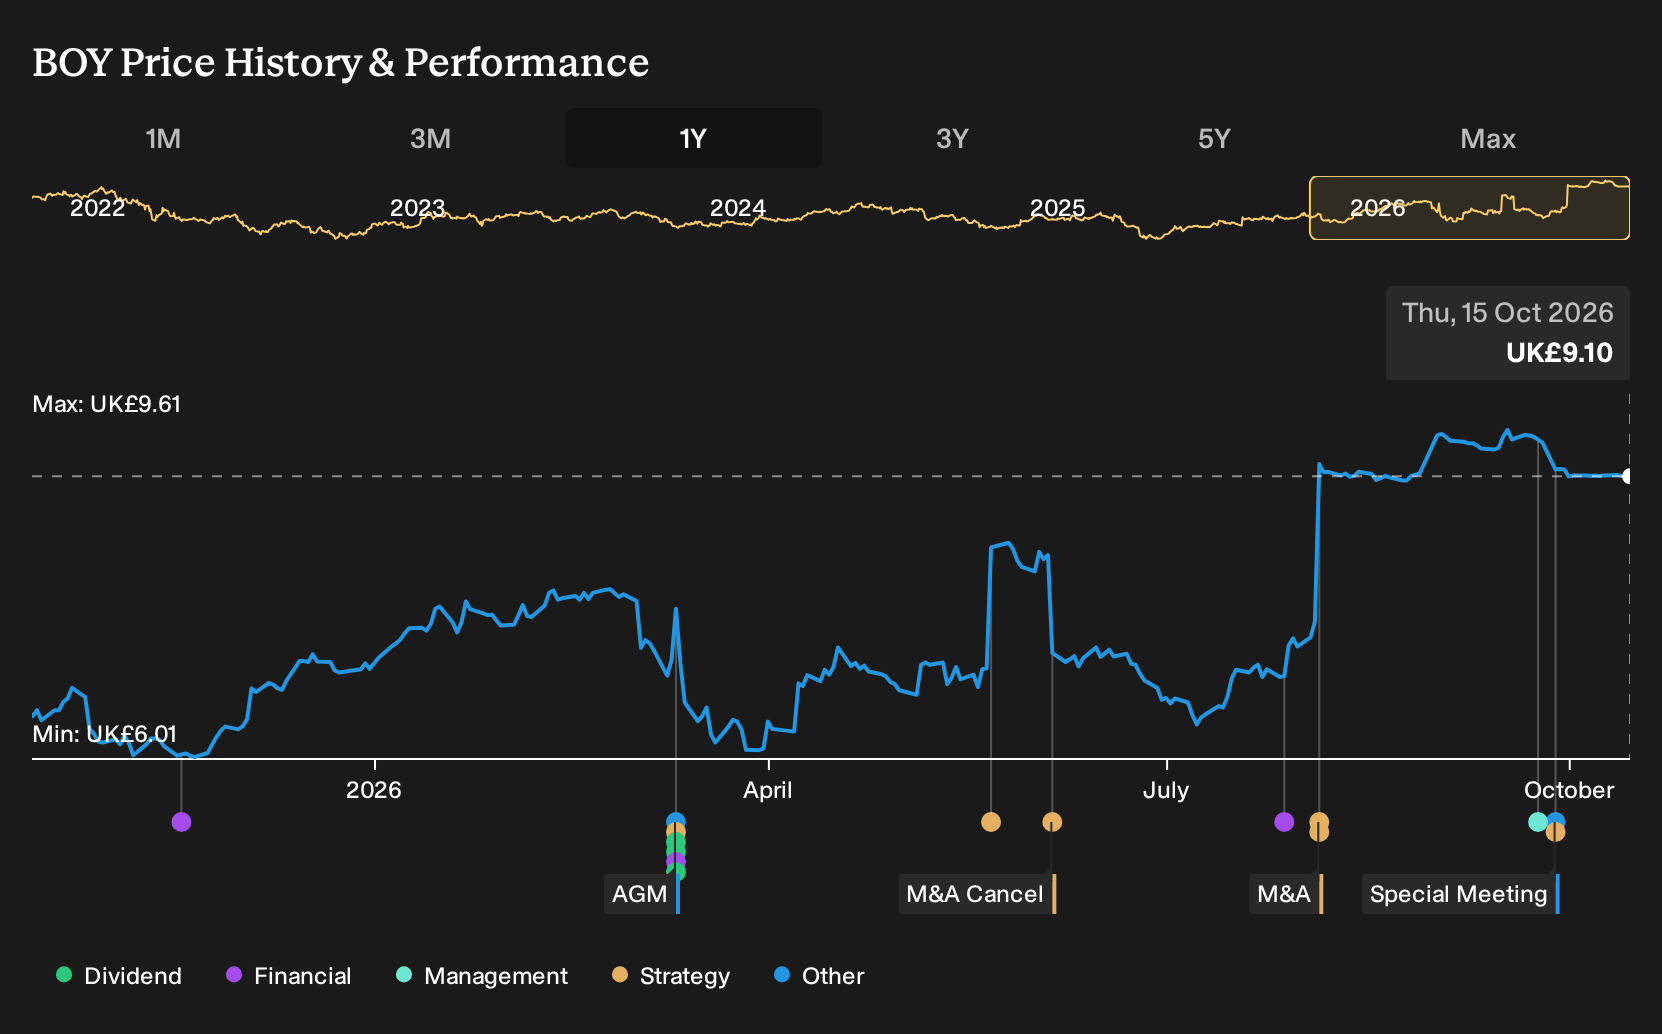
If you had picked up Bodycote on 15 October 2025, your patience would have been tested long before the recent flurry of stake-building disclosures from Millennium, JPMorgan, BNP Paribas and Vanguard hit the news. Holding Bodycote over the past year would have returned 43.9%, including dividends. If that decision were in front of you again, how much weight would you give to early worries about shrinking European markets compared with the potential of U.S. aerospace and Industry 4.0 Specialist Technologies?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Bodycote harder to judge, start where the gap is still open and scan 9 high quality undervalued stocks.
The Two Stories Bodycote Investors Had To Weigh
The shares cost £6.46 at the start of the period, and anyone looking at Bodycote then had to pick between two very different stories using the same set of facts.
On the bullish side, the Narrative put Fair Value at £7.41, about 15% above the start price. This view hinged on U.S. aerospace and defense capacity expansions, as well as Industry 4.0 Specialist Technologies such as HIP and vacuum treatments.
The bearish view pinned Fair Value at £6.10, around 6% below the start price. This perspective emphasized risks from reshoring, tighter environmental rules, and automation reducing demand for traditional thermal processing.
What The Results Changed For The Bodycote Story
The clearest new fact was Bodycote’s H1 2026 report. Revenue moved from £369 million in H1 2025 to £381.2 million, while net income rose from £27.7 million to £31 million and net margin edged up from 7.5% to 8.1%. Rising profitability supported the view that higher value work could improve the mix, although it did not remove regulatory or reshoring risks.
The practical lesson is simple. When a thesis depends on “better mix and higher-margin work,” track net margin and profit per pound of sales in each set of results and test whether they are really moving in that direction.
What Bodycote’s Run Up Already Assumes
Bodycote now trades at £9.1 after a 43.9% gain over the past year. The selected Narrative’s Fair Value sits below that level, so it treats today’s quote as embedding a demanding set of assumptions rather than a clear bargain.
The key argument is not that the business stalls, but that margin drag from restructuring, variable pay and bid led growth could offset mix improvement. Anyone paying today’s price is effectively assuming those programs translate into sustained, cleaner profitability. The question is how the highlighted execution risks might interfere with that outcome.
"Key Takeaways: Bearish analysts expect Bodycote's exposure to structurally challenged automotive and industrial markets, especially in Western Europe, to cap the benefits from aerospace, IGT and medical growth and to leave group returns under pressure even as the portfolio mix shifts toward higher margin activities. The main thing that has to go right is that Bodycote converts its portfolio pivot toward higher growth, higher margin end markets and Specialist Technologies, together with the Optimise and Perform programs, into durable margin gains that offset variable pay headwinds, ramp-up costs and restructuring complexity across the network."
One Narrative disagrees with today's price. → See where this Narrative says Bodycote should trade
Go Straight To The Source
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 24% below our estimate - uses a dispersed partner model and proprietary AI tools to reduce overheads and complexity.
- Company 2 - 28% below our estimate - channels pension and ISA inflows through a single low cost integrated technology platform.
- Company 3 - 17% below our estimate - adds automated manufacturing and warehousing capacity to support higher volume supplement contracts.
That is three of the list. See every one of the 9 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com