
Record Rents Raise Fresh Questions For Rightmove Stock
- Recent Rightmove data shows average advertised private rents across Britain excluding London have moved above £1,400 per month, with annual rental growth at 2.4% in Q3 as limited rental supply and elevated mortgage costs continue to pressure tenants.
- The combination of record asking rents and more measured rental demand puts fresh focus on how Rightmove’s portal can monetise rental activity beyond traditional listings while managing affordability pressures across its customer base.
- We will look at how Rightmove’s investment narrative is affected by record advertised rents and ongoing supply constraints in the UK rental market.
Scan how rental pressure plays out beyond Rightmove by reviewing hand-picked landlords, builders and service providers with list of solid balance sheet and fundamentals (9 results) in the current housing squeeze.
Rightmove Investment Narrative Recap
To own Rightmove, you need to believe its dominant UK portal keeps attracting consumers and property professionals, even as the housing market feels tight. The near term swing factor is still how much more value agents and landlords see in paid products as budgets strain. Record advertised rents look more like a neutral datapoint than a direct earnings catalyst right now.
The biggest operational risk remains agent churn and lower ARPA from new joiners, especially if competitors ramp up aggressively. Rental pressure could make some letting agents push back harder on fees or downgrade packages. That would test Rightmove’s ability to upsell tools and keep ARPA edging higher despite a softer backdrop.
Recent commentary around growth in rental services and mortgages is most relevant here, because it shows where Rightmove is already trying to capture more value from high rent levels. The business is leaning on adjacent services like tenant referencing, rent guarantee insurance and mortgage tools to deepen relationships with letting agents and landlords.
In the context of average advertised rents of more than £1,400 and measured tenant demand, those rental and mortgage products look closely tied to the key catalysts. Execution risk sits in proving these services genuinely help agents work through affordability strains rather than just adding another bill. Your focus should be on uptake, pricing power and whether churn stays contained while these extras scale.
Rightmove's analyst narrative points to forecast revenues of £598.4 million and consensus earnings of £292.3 million by 2029. This outcome assumes revenue growth of 10.9% per year, with earnings rising by about £73.9 million from £218.4 million today to reach that 2029 level.
Uncover why Rightmove's fair value indicates that the gap is in line with its current price.
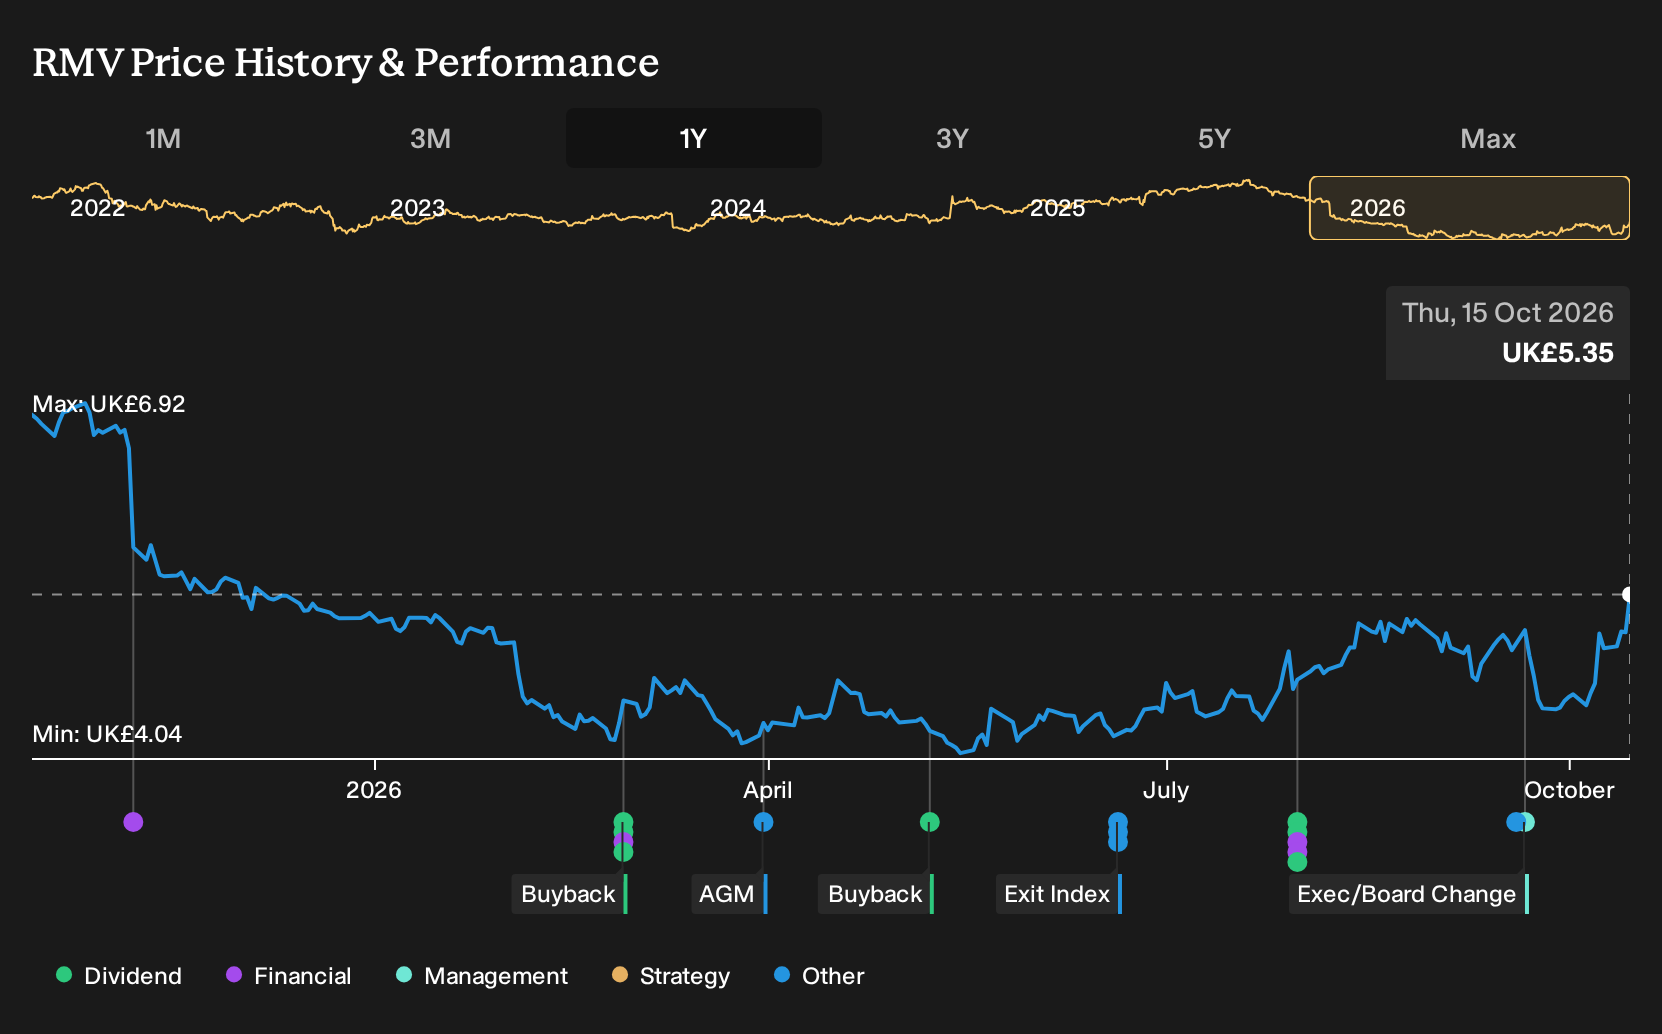
Exploring Other Perspectives
Some of the most optimistic analysts focus on Rightmove’s AI projects and data set as the main catalyst, not rental pressure itself. They were already pencilling in revenue of about £604.5 million and earnings of £283.7 million by 2029. With advertised rents now above £1,400, those pre news assumptions may shift. Expect strong views on both sides; treat this as one lens and explore a few others before you decide how the story fits your own view.
Explore 4 other Rightmove fair value estimates, including one that suggests it could be worth as much as £5.45.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Rightmove research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Rightmove. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rightmove's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rightmove?
If the Rightmove story has sharpened your view on housing and income risk, it can help to widen the lens and compare it with other opportunities that match different goals and risk levels.
- If you want potential growth with a smaller price tag, scan 13 elite penny stocks with strong financials that still clear a quality bar on fundamentals.
- For readers focused on quality at a reasonable entry point, review the 9 high quality undervalued stocks that our filters flag as having stronger business metrics than their current pricing implies.
- If resilience and balance sheet strength matter most to you, work through a curated 4 resilient stocks with low risk scores that may better align with a steadier approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com